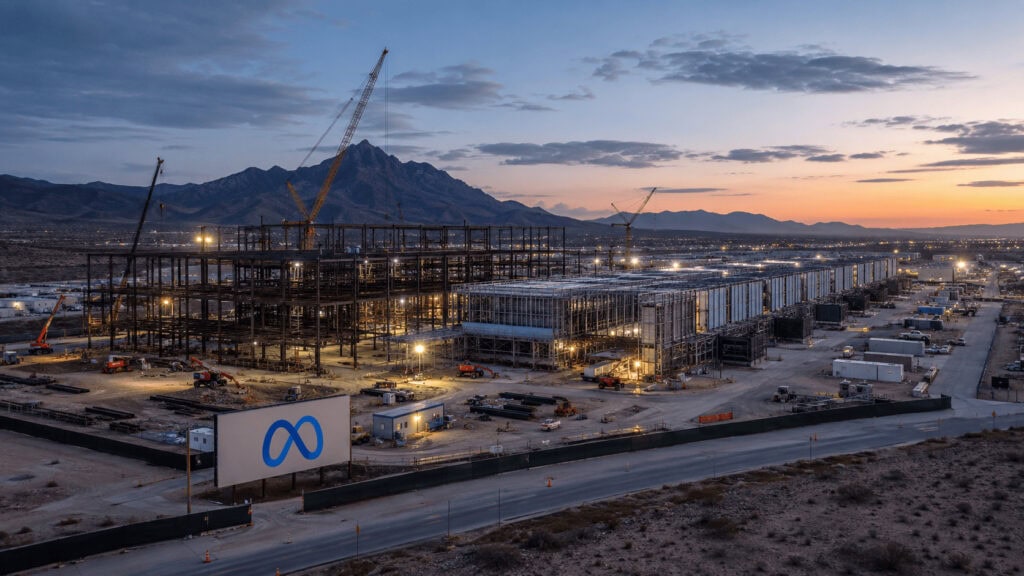

The world’s largest asset manager is bankrolling Meta’s El Paso compute build, and the ownership structure tells you how AI infrastructure now gets financed.
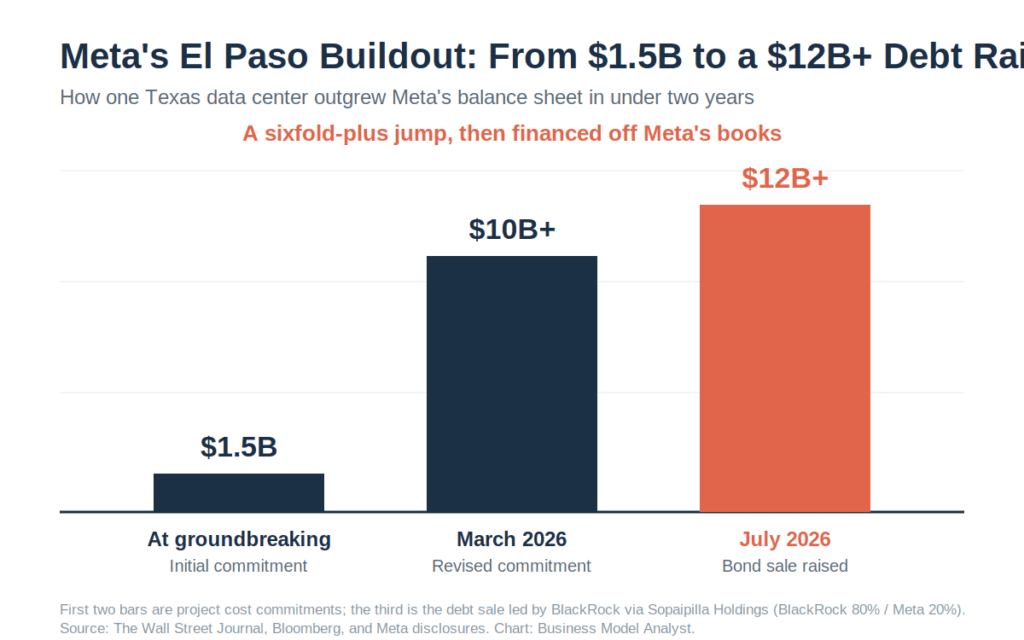
BlackRock is leading a bond sale of more than $12 billion to finance a Meta data center campus in El Paso, Texas, structured through a project entity called Sopaipilla Holdings. BlackRock and its infrastructure and private-credit arms own 80% of the project, while Meta owns 20% and gets to use the compute. JPMorgan and Morgan Stanley are arranging the debt, with pricing expected in late July 2026.
Here is the part everyone will skim past on the way to the big number: Meta is building one of the largest AI facilities in the country, and it will own just one-fifth of it. That is not a compromise. That is the design. The $12 billion is the headline, but the 80/20 split is the actual story, because it shows you exactly how hyperscalers have started paying for the AI boom without wrecking their own balance sheets.
What Happened
BlackRock is marketing more than $12 billion of bonds to fund a Meta data center campus in El Paso, according to reporting from Bloomberg and The Wall Street Journal. The debt is being issued by a holding company that owns BlackRock’s 80% stake in the project, formally named Sopaipilla Holdings. Meta owns the remaining 20% and will be the tenant using the finished compute.
JPMorgan and Morgan Stanley have been mandated to run fixed-income investor calls midweek, with the bonds expected to price early the following week. The deal joins a rapid string of jumbo debt offerings funding the physical layer of artificial intelligence, and it pushes single-project financing to a new ceiling.
The Backstory
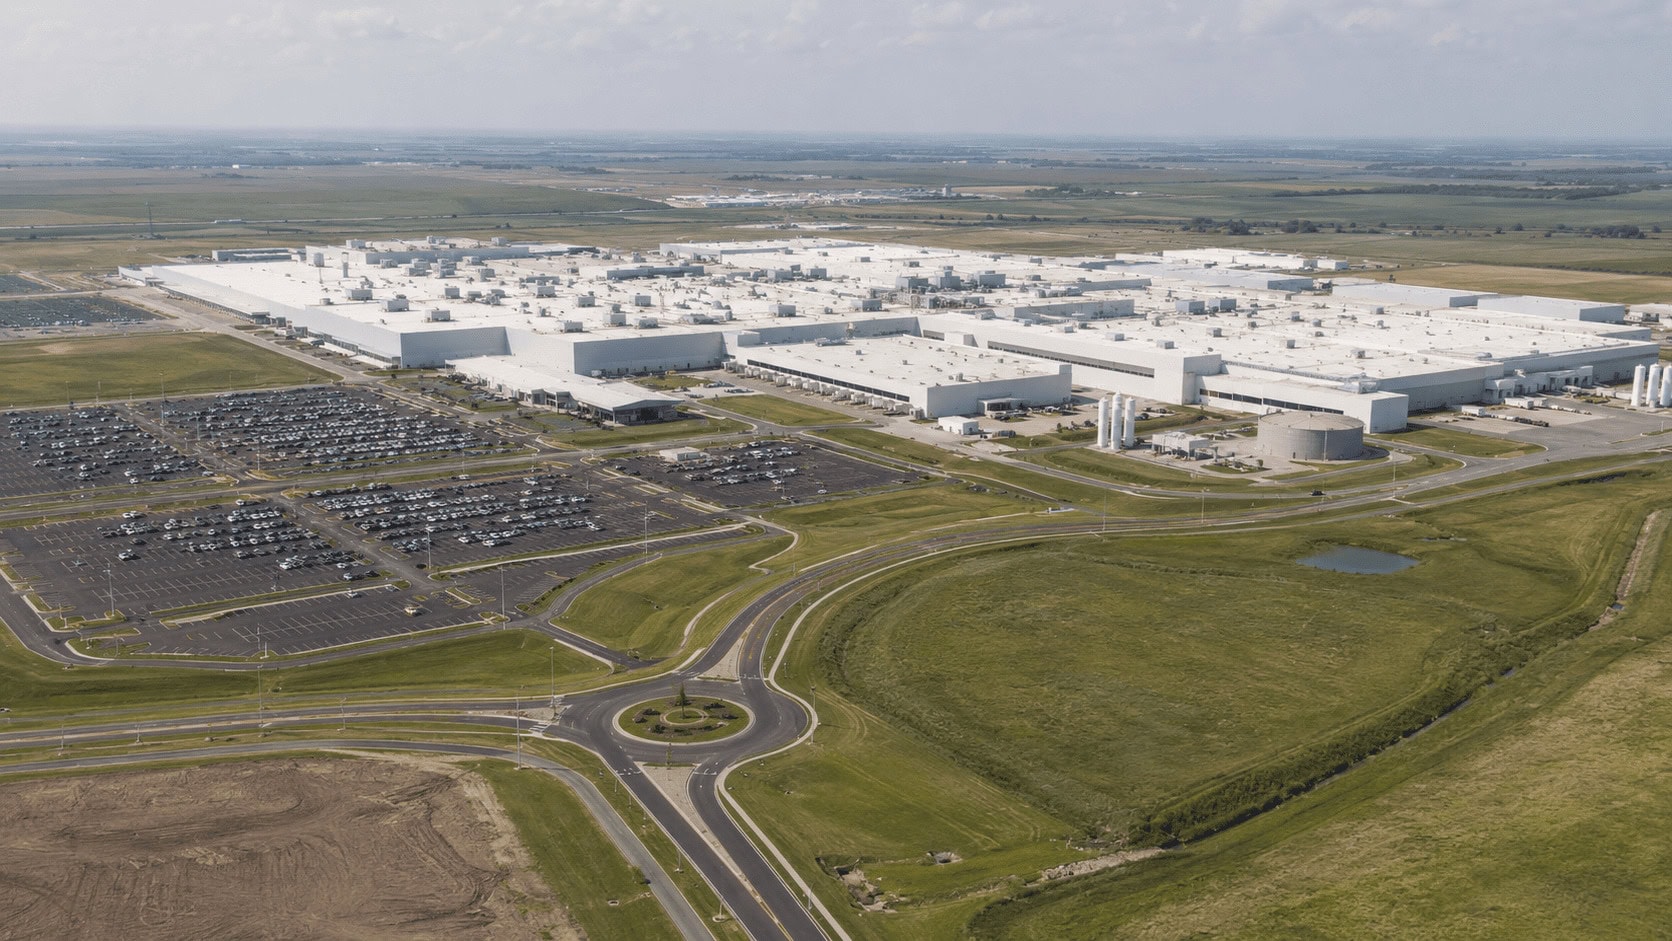
The El Paso campus did not start out this big. When Meta broke ground, the commitment was roughly $1.5 billion. By March 2026, mid-construction, that figure had passed $10 billion, a sixfold jump in a matter of months. The facility now targets one gigawatt of capacity, sits on a 1.2 million square foot site, and is scheduled to open in 2028 as Meta’s third data center in Texas.
That escalation is the whole reason the financing looks the way it does. Meta guided 2026 capital expenditures to a range of $125 billion to $145 billion. A company can fund a $1.5 billion project out of pocket without blinking. A single site that balloons past $10 billion, inside a total capex program north of $125 billion, is a different math problem. Funding all of it from the corporate balance sheet would bloat the debt load and drag on the metrics investors actually watch.
So Meta reached for a structure it had already tested. Its Louisiana campus, code-named Hyperion, was financed through a joint venture where private-credit firm Blue Owl held 80% and Meta held 20%, and that entity issued a roughly $27 billion private-debt package, the largest ever recorded. BlackRock was among the biggest buyers of that paper, picking up more than $3 billion of the bonds. El Paso runs the same play, with BlackRock now sitting in the majority-owner seat instead of the buyer’s seat.
The Plan
Strip out the jargon and the mechanics are simple. A separate company owns the data center. Meta takes a minority equity stake, signs on as the long-term user of the capacity, and that separate company raises the mountain of debt against Meta’s contracted usage. The building gets financed, Meta gets the compute, and the bulk of the debt lives outside Meta’s own financial statements.
For the lenders and equity holders, the appeal is a long-dated, contracted cash flow backed by one of the most creditworthy tenants on earth. For Meta, it is capacity without the full balance-sheet hit. This is project finance, the same category of structure used to build power plants, pipelines, and toll roads, now pointed at gigawatt-scale compute. AI infrastructure has quietly become national-infrastructure-scale project finance, and El Paso is the current high-water mark.
The Business Model Angle
The sharper story here is not Meta’s. It is BlackRock’s, and it is a textbook case of a company deliberately rebuilding what it is.
For decades, BlackRock ran a scale game. It collected thin fees on trillions of dollars parked in index funds and iShares ETFs. High volume, low margin, minimal capital at risk. A brilliant business, but a passive one. Larry Fink spent the past several years dismantling that limitation on purpose, buying Global Infrastructure Partners and private-credit shop HPS Investment Partners, and folding in a roughly $40 billion acquisition of Aligned Data Centers. Those deals turned a roughly $15 trillion index manager into something that actively owns and operates hard assets and originates private debt.
El Paso is that transformation cashing out. BlackRock is not clipping a management fee on this deal. It owns 80% of the equity in a real, revenue-generating asset. And its broader platform now spans the same capital stack this kind of project runs on: the equity ownership, the private-credit machinery, and a proven appetite for buying the resulting bonds, as the $3 billion-plus Louisiana purchase showed. Fink has maneuvered BlackRock into a position where it can touch nearly every layer of the AI infrastructure trade at once. That is vertical integration of the capital stack, and it is a fundamentally higher-margin, higher-control business than selling cheap index funds.
Meta’s side of the ledger fits its own pattern too. The company is spending like a utility to build the compute, financing it like infrastructure to protect the balance sheet, and, as its move to sell AI compute through a cloud business shows, looking to turn that same capacity into a revenue line rather than a pure cost center. The Meta ad engine still pays the bills, but the AI buildout is being run as its own financial operation.
The Risk
The obvious question is what happens if the AI demand curve bends. This entire structure rests on one assumption: that gigawatt-scale compute leased to a hyperscaler is a safe, long-dated, contracted cash flow. Right now, credit markets clearly agree. JPMorgan and Morgan Stanley are not arranging $12 billion into a market with thin appetite, and the fact that deals this size keep clearing signals that institutional demand for AI infrastructure paper is still deep.
But off-balance-sheet does not mean risk-free. It means the risk has moved. It now sits with the equity owners like BlackRock and the bondholders buying the paper, rather than with Meta. If utilization disappoints, if lease rates compress, or if the AI capex cycle cools before these decades-long amortization schedules play out, the pain lands on the financiers, not the tenant. BlackRock has concentrated a large and growing share of its newly acquired private-market firepower into a single, correlated bet on one theme. That is a very different risk profile than a company whose old reputation was built on boring, diversified index funds.
Quick Questions
Who actually owns the El Paso data center? BlackRock, through its infrastructure and private-credit arms, owns 80% of the project entity, Sopaipilla Holdings. Meta owns 20% and will use the completed compute capacity.
Why does Meta only own 20% of its own data center? The structure keeps most of the roughly $12 billion in project debt off Meta’s balance sheet. Meta gets to use the compute without carrying the full cost as its own debt, while outside owners and lenders fund the build.
How big is the El Paso facility? It targets one gigawatt of capacity across a 1.2 million square foot site and is expected to open in 2028. It will be Meta’s third data center in Texas.
Is this the first deal like this? No. Meta used a nearly identical structure for its Louisiana campus, Hyperion, where Blue Owl owned 80% and the project issued a record roughly $27 billion in private debt. BlackRock bought more than $3 billion of those bonds.
Who is arranging the bond sale? JPMorgan and Morgan Stanley are running investor calls and arranging the offering, with pricing expected in late July 2026.
The Business Model Analyst Take
The $12 billion number is the bait. The structure is the lesson.
Two of the most important business-model shifts in the market right now are colliding inside this one deal. Meta has figured out how to fund a national-scale AI buildout without putting all of it on its own books, treating compute like a power plant instead of a gadget. And BlackRock has spent years and tens of billions converting itself from a passive fee-collector into an active owner of the exact assets that boom requires. El Paso is where those two strategies meet.
For anyone building or investing, the takeaway is not that AI is expensive. Everyone knows that. It is that the winners are increasingly defined by who controls the financial plumbing, not just the technology. Meta is protecting its balance sheet. BlackRock is capturing margin across the whole capital stack. The company that owns the buildings, and the firm that figured out how to finance them, may end up capturing more durable value than whoever ships the best model. Watch the structures, not just the size.
Reporting on the financing details is based on coverage from The Wall Street Journal and Bloomberg. Project specifications and capex figures draw on Meta’s public disclosures and prior reporting.