
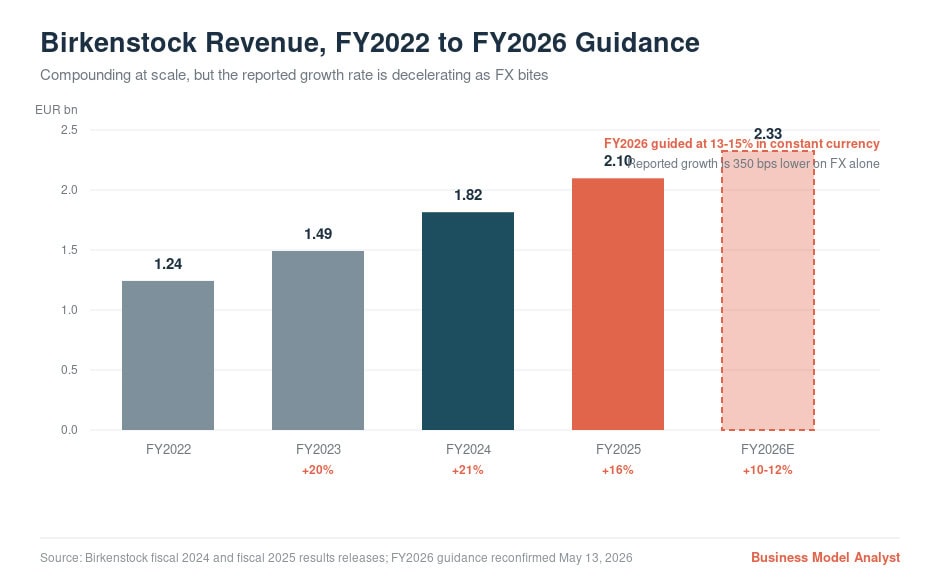
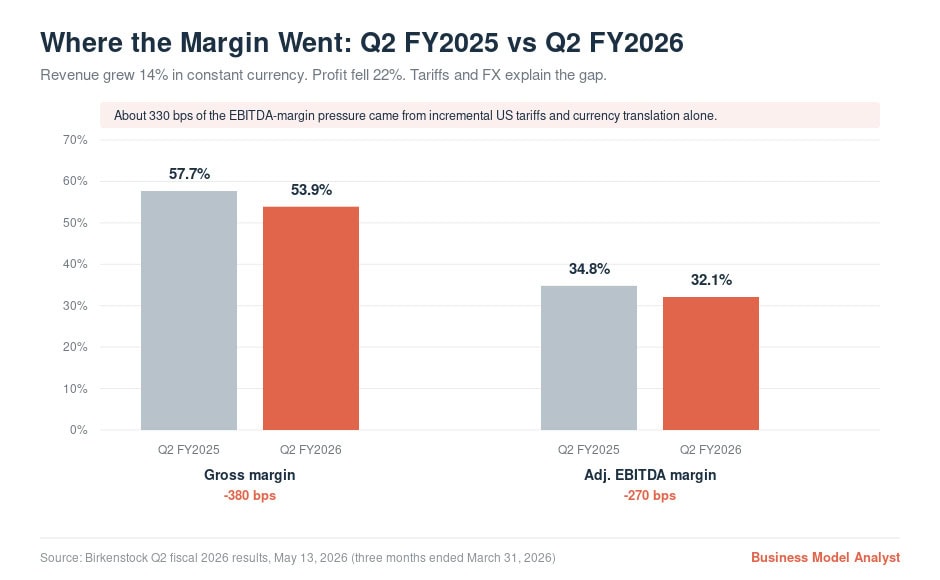
Birkenstock is the rare consumer brand that has spent 250 years selling essentially the same object and is still compounding revenue in the mid-teens. In fiscal 2025 it crossed EUR 2 billion in revenue for the first time, held a gross margin above 59%, and told investors that the only thing capping its growth was its own factory floor. Then fiscal 2026 arrived, the dollar weakened, US tariffs landed, and net profit fell 22% in a single quarter on 14% constant-currency revenue growth.
That gap between the operating business and the reported numbers is the entire story of Birkenstock right now. This SWOT analysis works through it using the FY2025 results, the Q2 FY2026 filings, and the three-year plan management laid out at its first Capital Markets Day in January 2026.
What is a Birkenstock SWOT analysis? A Birkenstock SWOT analysis is a structured assessment of the strengths, weaknesses, opportunities, and threats facing Birkenstock Holding plc (NYSE: BIRK), the German footwear company built around its cork-latex footbed. Strengths and weaknesses are internal, meaning they sit inside management’s control. Opportunities and threats are external.
Company snapshot (as of July 2026)
| Item | Detail |
|---|---|
| Legal entity | Birkenstock Holding plc (NYSE: BIRK) |
| Founded | 1774, Germany |
| CEO | Oliver Reichert |
| Controlling shareholder | L Catterton, through BK LC Lux MidCo S.a r.l. |
| FY2025 revenue | EUR 2.10 billion, up 16% reported and 18% in constant currency |
| FY2025 adjusted EBITDA | EUR 666.9 million, a 31.8% margin |
| FY2025 net profit | EUR 348.3 million, up 82% |
| FY2025 gross margin | 59.1% |
| Manufacturing | Six plants in Germany plus a component facility in Portugal, all footwear made in the EU |
| Own retail stores | 97 at the end of FY2025, up 30 net |
| FY2026 guidance | 13% to 15% constant-currency growth, EUR 2.30 to 2.35 billion reported |
The one-line answer: Birkenstock’s strength is pricing power on an unfashionable product that never goes out of style. Its weakness is that it earns in dollars and spends in euros, and it has no legal monopoly on the shape it sells.

Strengths
1. The footbed is a moat that competitors cannot copy quickly
The cork-latex footbed is not a design flourish. It is a physiological lock-in. Once a foot adapts to the contoured support, flat footwear becomes actively uncomfortable, which turns a discretionary fashion purchase into a replenishment purchase. The financial evidence for that is in the sell-through: management reported full-price sell-through above 90% in Q2 FY2026, which is the number that separates a healthy brand from one propped up by promotion.
Compare that with the promotional pressure visible across footwear peers. When we walked through the Crocs SWOT analysis, the risk was seasonal demand and fashion-cycle dependency. Birkenstock has bought its way out of both, and the sell-through number is the proof.
2. Elite margins, and they are structural rather than cyclical
FY2025 delivered a 59.1% gross margin and a 31.8% adjusted EBITDA margin on EUR 2.1 billion of revenue. For context, Nike runs a gross margin in the low forties. Crocs posted a stronger gross margin than Birkenstock on paper in FY2025 but shrank revenue while doing it, with consolidated Q4 revenue down 3.2% and full-year adjusted operating margin of 22.3%.
Birkenstock is the only one in that comparison set growing double digits and holding a 30%-plus EBITDA margin at the same time.
| Metric | Birkenstock (FY2025) | Crocs (FY2025) |
|---|---|---|
| Revenue | EUR 2.10 billion | Over USD 4 billion |
| Revenue growth | +16% reported | Declining, Q4 down 3.2% |
| Gross margin | 59.1% | 54.7% in Q4, down 320 bps |
| Profitability | 31.8% adjusted EBITDA margin | 22.3% adjusted operating margin |
3. Scarcity is a deliberate operating choice, not an accident
Reichert has been explicit that growth is limited by production capacity and by a decision to preserve scarcity, not by demand. That sounds like a humblebrag until you look at the pricing consequence: FY2025 revenue growth of 18% in constant currency broke down into 12% unit growth and 5% higher average selling price. Raising price into a soft consumer environment without denting volume is the cleanest possible test of pricing power, and Birkenstock passed it.
4. Vertical integration and an all-EU supply chain
Six German plants and a Portuguese component facility, with roughly 95% of production in Germany. That gives quality control, inventory control, and a “Made in Germany” story that supports the price architecture. The company also fast-tracked capacity in September 2025 by buying a bankrupt owner’s facility near Dresden for a net EUR 18 million, picking up 78,000 square meters of production and logistics space at roughly EUR 240 per square meter, well below the cost of a new build.
5. The seasonality problem has been solved
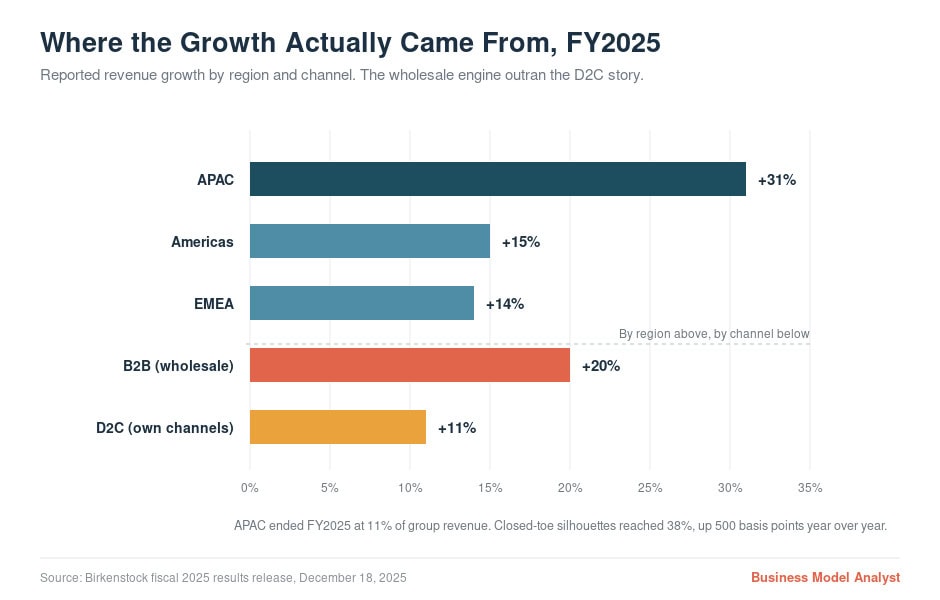
Closed-toe silhouettes reached 38% of revenue in FY2025, up 500 basis points year over year. That is the single most underrated number in the story. A sandal company is a summer business with a working-capital problem. A footwear company with a 38% closed-toe mix is a year-round business, and closed-toe shoes carry a higher average selling price.
Weaknesses
1. Costs in euros, revenue in dollars
Roughly 46% of revenue is denominated in US dollars while almost all production sits in the eurozone. That is a structural currency mismatch, and in FY2026 it is costing about 350 basis points of reported revenue growth. Guidance of 13% to 15% in constant currency translates to only 10% to 12% reported. Management is running the business well and the income statement is still getting worse in the currency investors read it in.
2. Capacity is the ceiling, and it takes years to raise
“Demand exceeds supply” is a flattering constraint until you need to accelerate. Factories take 17 months to build and years to ramp. Birkenstock is spending EUR 110 to 130 million of capex in FY2026 largely on capacity, but a company that cannot flex output quickly also cannot respond quickly if a competitor or a trend moves against it.
3. The direct-to-consumer story is thinner than the branding suggests
Birkenstock is often filed as a D2C success. The filings say otherwise. In FY2025, B2B grew 20% while D2C grew 11%, pulling D2C down to roughly 38% of revenue. Management also disclosed that its D2C business is about 80% online, which carries a high variable cost structure and little operating leverage, and that it takes roughly 2.5 wholesale pairs to generate the revenue of one D2C pair. The mix is drifting back toward wholesale, which is the lower-margin channel.
4. Product concentration around a single idea
Skincare, sleep systems, and accessories exist but are rounding errors. Essentially all of the revenue comes from footwear built on one footbed. That focus is a strength commercially and a weakness structurally, because there is no second engine if the first one stalls.
5. The register is not controlled by public shareholders
L Catterton, the LVMH-affiliated private equity firm, still controls the company through BK LC Lux MidCo. The June 2026 financing explicitly contemplates repurchasing up to USD 500 million of shares including from Midco itself. A controlled company whose sponsor is a persistent seller carries a structural overhang that has nothing to do with how many sandals get sold.
Opportunities
1. APAC is barely started
APAC finished FY2025 at just 11% of group revenue after growing 31% reported. In Q2 FY2026 it grew 30% in constant currency, with the highest closed-toe penetration and the highest average selling price of any region. Management expects APAC to grow at roughly twice the pace of the other segments through FY2028. This is the clearest growth lane the company has.
2. Own retail is still tiny
Ninety-seven stores globally is nothing for a brand this size, and the plan is roughly 40 new doors a year. Physical retail is also the fix for the D2C leverage problem, because four-wall economics improve as stores mature, unlike the 80% online mix that carries variable costs on every order.
3. The white spaces management already named
Orthopedics, professional footwear, and outdoor are all adjacent to the footbed and all under-monetized. Closed-toe at 38% has obvious runway toward parity with sandals. The February 2026 launch of the Highwood Moc Lace Low signals the company intends to keep pushing into closed shoes rather than treating them as a seasonal hedge.
4. The three-year plan is a real number, not a slogan
At its January 2026 Capital Markets Day, management committed to roughly EUR 1 billion of incremental revenue between FY2026 and FY2028, implying a path from EUR 2.1 billion to about EUR 3 billion at a 13% to 15% CAGR, with unit growth around 10% and a 30%-plus adjusted EBITDA margin maintained throughout. If tariffs and FX normalize, the reported numbers would re-rate without management doing anything differently.
Threats
1. US tariffs, and the strange way they got worse
Roughly 95% of production is in Germany. There is no cheap way to tariff-proof that. Management has said fully offsetting the tariff cost would require price increases of about 2.5 times the tariff itself, which it refuses to do. More awkwardly, the CFO told analysts in May 2026 that the US Supreme Court ruling striking down IEEPA tariffs actually increased Birkenstock’s exposure, at least temporarily, and that refund claims will run to roughly EUR 30 million with uncertain timing. Tariff policy is a threat that management cannot hedge, price away, or relocate around.
2. Currency, in the same direction, at the same time
Guidance assumes an average EUR/USD rate of 1.17. FX and tariffs together are baked in as about 200 basis points of pressure on both adjusted gross margin and adjusted EBITDA margin for FY2026. Two uncontrollable variables are pushing the same way at once.
3. The icons are not legally protected
On 20 February 2025, Germany’s Federal Court of Justice ruled that Birkenstock sandals are not works of applied art and therefore do not enjoy copyright protection. The court held that the designs were driven by technical and functional requirements and stayed within ordinary craftsmanship, dismissing three cases Birkenstock had brought against retailers selling lookalikes. The practical consequence is blunt. The Arizona and Madrid silhouettes, designed in the 1960s and 1970s, are outside copyright, and design registrations on shapes that old have long since expired. The moat is the footbed, the brand, and the manufacturing base. It is not the law.
4. Fashion-cycle risk is real even when management denies it
Birkenstock insists it is a purpose-driven brand rather than a trend. That is mostly true and completely unfalsifiable in the short run. But the brand’s revenue inflection coincided with a broad cultural moment for ugly-comfortable footwear, and cultural moments end. Adidas is currently riding the Samba wave and remembers exactly how fast the previous one ended. A 90% full-price sell-through rate is the metric to watch here. If it starts drifting toward the low eighties, the thesis is breaking.
5. The balance sheet got heavier while the margin got thinner
The June 2026 refinancing raised EUR 900 million of 4.500% senior notes due 2033, redeeming EUR 428.5 million of 5.25% notes due 2029 and funding buybacks. The coupon improved and the maturity extended, which is good. Pro forma total indebtedness of EUR 1,714.4 million is a larger number to carry into a period of compressing margins and a nervous consumer. Net leverage was 1.7x at the end of Q2 FY2026, up from 1.5x at fiscal year end.
Information Gain: The Numbers Most Birkenstock SWOT Analyses Miss
| Data point | Figure | Why it matters |
|---|---|---|
| FY2025 unit vs price split | 12% unit growth, 5% constant-currency ASP growth | Isolates pricing power from volume; both are working |
| Full-price sell-through | Over 90% (Q2 FY2026) | The single best leading indicator of brand health |
| D2C channel composition | Roughly 80% online | Explains why D2C growth does not drop to the bottom line |
| Wholesale-to-D2C revenue ratio | About 2.5 wholesale pairs equal 1 D2C pair | Quantifies the margin cost of the B2B mix shift |
| Q2 FY2026 gross margin | 53.9%, down from 57.7% | 380 bps of compression on 14% cc growth |
| Tariff refund claims | About EUR 30 million, timing uncertain | An asset nobody is modeling |
| Dresden facility | EUR 18 million net, about EUR 240 per sq m | Capacity bought at distressed pricing, below new-build cost |
| APAC share of revenue | 11%, targeted to grow at 2x group pace | The clearest structural growth lane |
| Pro forma total debt | EUR 1,714.4 million | Post-refinancing, with net leverage at 1.7x |
Frequently Asked Questions
Is Birkenstock profitable? Yes, and substantially so. Birkenstock reported FY2025 net profit of EUR 348.3 million, up 82% year over year, on revenue of EUR 2.10 billion. Adjusted EBITDA was EUR 666.9 million, a 31.8% margin.
What is Birkenstock’s biggest weakness? The currency and tariff mismatch. Roughly 95% of production is in the EU while about 46% of revenue is in US dollars. That mismatch cost the company 380 basis points of gross margin in Q2 FY2026 and turns 14% constant-currency growth into 8% reported growth.
Who owns Birkenstock? L Catterton, the private equity firm affiliated with LVMH, took a majority stake in 2021 and still controls the company through BK LC Lux MidCo S.a r.l. following the October 2023 NYSE listing.
Can other companies legally copy Birkenstock sandals? In Germany, largely yes. The Federal Court of Justice ruled in February 2025 that the sandals are not works of applied art and do not qualify for copyright protection. Trademark and unfair-competition claims remain available, but the shapes themselves are not locked up by copyright.
Is Birkenstock still a sandal company? Less and less. Closed-toe silhouettes reached 38% of revenue in FY2025, up 500 basis points in a single year, which has materially reduced the seasonality of the business.
What is Birkenstock’s growth target? Management is guiding to 13% to 15% constant-currency revenue growth for FY2026 and has committed to roughly EUR 1 billion of incremental revenue by FY2028, taking the company from EUR 2.1 billion to about EUR 3 billion.
The Business Model Analyst Take
The market is currently pricing Birkenstock as though something went wrong. Nothing did.
Strip out currency translation and tariffs and this is a business growing 14% to 18% in constant currency, selling more than 90% of its product at full price, raising prices without losing volume, and turning a seasonal sandal into a year-round shoe. That is not a broken company. That is a company whose income statement is being translated through a hostile exchange rate and taxed at the US border.
The honest bear case is not about demand. It is about protection. Birkenstock has no copyright on its icons, no cheap manufacturing option, and no second product engine. Its defenses are the footbed, the brand, and a factory network it cannot move. Those are real, but they are the kind of moat that erodes slowly and invisibly rather than collapsing in a quarter, which means the warning signs will show up in sell-through and average selling price long before they show up in revenue.
So watch two numbers and ignore the rest. Full-price sell-through, currently above 90%, tells you whether the brand still has permission to charge what it charges. Closed-toe mix, currently 38%, tells you whether the company is still successfully outgrowing its own seasonality. If both hold, the tariff and FX drag is a timing problem and the stock is a mispricing. If either one slips, the story was a fashion cycle after all, and every margin assumption in the three-year plan goes with it.
If you want to run this framework on another company, start with our guide on how to do a SWOT analysis.