
David Fox wrote the playbook that made Kirkland & Ellis the largest law firm on earth. His new venture runs on fewer than 10 people and a corporate structure that finally lets outsiders own a piece of a law firm.
David Fox, the dealmaker credited with turning Kirkland & Ellis into a $10.56 billion firm, has co-founded Irving Technology, a software company powering a new AI-based law firm called Irving. The venture splits into two entities: a lawyer-owned firm and an investor-owned technology company. That split matters more than the AI. It gives law firms their first real access to outside capital and their first asset that can be sold, and it puts a second profit engine next to the billable hour for the first time in a century.
Fox is 68. He has already flipped the legal industry once, and the firm he flipped it for is now the most profitable in history. So when he tells the Wall Street Journal he hopes he has one more revolution left in him, the interesting question is not whether AI can draft a merger agreement. The interesting question is what he plans to own.
What Happened
Fox co-founded Irving Technology, a software company that powers Irving, a newly launched New York law firm employing fewer than 10 people across lawyers and engineers. The firm has run in stealth for several weeks and has already advised on a handful of small deals ahead of a formal debut.
Irving Technology has raised a small sum from Narya Capital, the venture firm JD Vance co-founded before entering politics, the New York firm Addition, former Kirkland chairman Jeff Hammes, and Fox’s own venture outfit Antiportfolio Ventures. Three other co-founders are engineers who came out of technology and defense companies, including Palantir.
Fox says the software was trained on existing large language models with input from practicing deal lawyers, and performs at roughly the level of a strong senior associate. He will be involved in the firm without a defined role and is not practicing law himself.
The Backstory
Fox spent more than two decades at Skadden, rising to become its most senior partner and working on deals including the $6.6 billion buyout of Toys “R” Us. In 2009 he left for Kirkland & Ellis, which at the time barely had an M&A practice, and brought Daniel Wolf with him.
Working with then-chairman Jeff Hammes, Fox reset the culture of Kirkland’s New York office, recruited rising lawyers out of rival firms, and pushed the team toward bigger mandates. By 2020, when he stepped off the executive committee under the firm’s age rules, Kirkland was advising on more deals per year than anyone.
The scoreboard since: Kirkland posted $10.56 billion in 2025 revenue, up around 20%, becoming the first law firm to cross $10 billion. Profit per equity partner reached $11.1 million. Revenue per lawyer climbed 11% to $2.55 million. Fox built the machine, and the machine is running hotter than ever.
The Plan
Irving is not the only entrant. Norm Law, backed by an AI company with Bain Capital and Blackstone money behind it, has been hiring senior lawyers away from Ropes & Gray and Sidley Austin. General Catalyst is behind Eudia Counsel. Harvey, Legora and CoCounsel are already installed across the industry as off-the-shelf tools.
The incumbents are not standing still either. Kirkland has set aside $500 million to build its own AI platform rather than rent the same software its rivals use. Freshfields signed a deal with Anthropic to co-build specialised applications. Cleary Gottlieb bought Springbok AI outright and brought the engineers in-house.
Fox’s pitch is that AI removes the repetitive work and frees senior lawyers for the judgment calls, with clients paying less. As he puts it, a great partner’s superpower was always knowing what in a deal deserves attention and what does not.
The Business Model Angle
Strip out the AI and look at the corporate chart, because that is where the money is.
Irving uses a management services organization structure, or MSO. One entity is the law firm: lawyer-owned, takes the legal fees, holds the client relationships. The second entity owns the software, the intellectual property and the infrastructure, and it can take money from anyone. Private equity, venture funds, sovereign wealth, whoever. It can also go public.
American Bar Association Model Rule 5.4 has blocked non-lawyers from owning law firms for decades. Partners could earn enormous income but could never sell what they built. A retiring Kirkland partner cashes out a capital account, not a stake. The MSO routes around that rule without breaking it, and the accounting profession has already run the same play at scale.
The rules are loosening underneath it. Arizona scrapped Rule 5.4 in 2021 and had 114 licensed alternative business structures operating by the end of 2024, including a KPMG legal subsidiary. Utah runs a sandbox. Puerto Rico now allows non-lawyer ownership up to 49%. McDermott Will & Schulte, product of a 2025 merger, is among the established firms weighing an MSO conversion.
Now the part that should worry Big Law, and it has nothing to do with drafting speed.
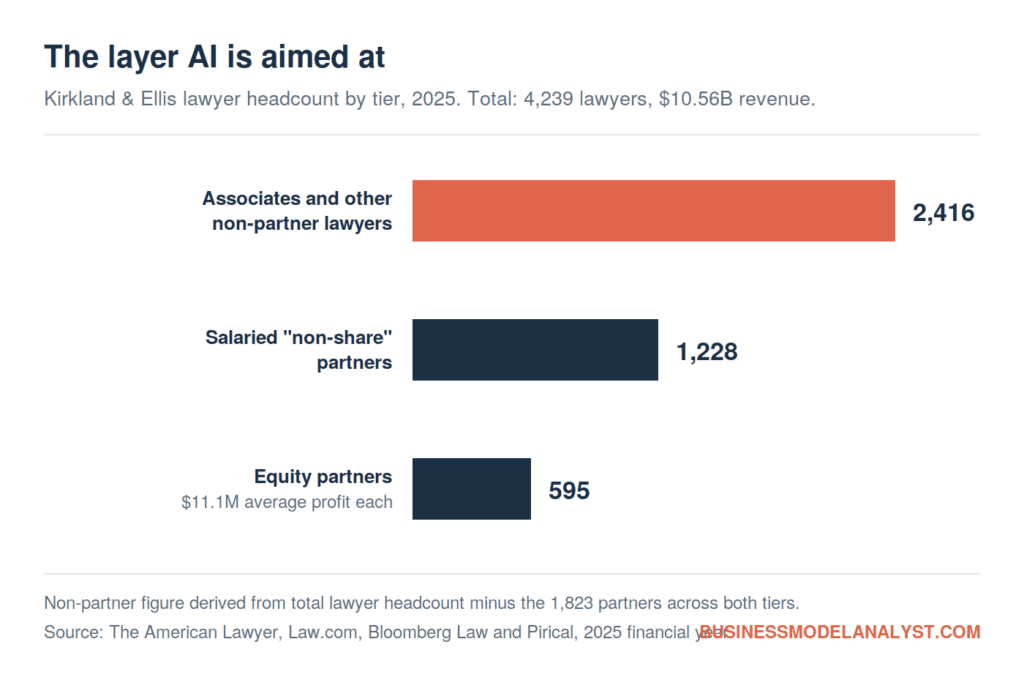
The Cravath system has powered elite law for a century on one mechanic: hire large numbers of expensive juniors, bill them out at a multiple of their salary, and hand the spread to a small group of equity partners. Kirkland runs 595 equity partners on top of roughly 2,400 associates and other non-partner lawyers, with another 1,228 salaried partners wedged in between. The pyramid is the profit engine.
An AI that works at senior-associate level attacks the widest part of that pyramid. Fox says the number out loud: does the job need 5,000 talented people, or can 20 do it?
Big Law’s answer to that has been to buy the technology. Kirkland’s $500 million goes into a cost center that protects billable hours it may end up cannibalising. Irving’s structure turns the same technology into an asset with a valuation, a cap table and an exit. A partnership that spends $500 million owns software. A company that raises $500 million owns equity someone else will pay for later.
The Risk
Irving has fewer than 10 people and a handful of small deals behind it. Kirkland advised on $427 billion of deals in a single year. The gap is not a rounding error.
Three things stand between the pitch and the outcome:
Clients buy scars, not throughput. A board handing over a $20 billion take-private is buying somebody who has seen the deal break in six previous lives. That judgment sits with partners who already earn $11 million a year at Kirkland. Poaching them requires the equity upside in the tech entity to beat guaranteed cash, and it requires clients to follow.
The regulatory ground is moving both ways. California’s AB 931 pushed back on MSO-supported firms. A Puerto Rico Supreme Court justice dissented on the grounds that non-lawyer owners sit outside the disciplinary system entirely. Every state that liberalises invites a state that clamps down, and a structure legal in Arizona can create ethics exposure in New York.
Cheaper legal work is a claim, not a moat. Fox says clients will pay less. If AI-native firms compete on price against incumbents who have already bought the same underlying models, the discount becomes the product and the margin goes to whoever raised the most capital. That is a venture-funded price war with law firms in it, and Big Law has $10 billion balance sheets and no investors demanding a return.
Quick Questions
What is an MSO in a law firm context? A two-entity structure. Lawyers own and control the firm that practices law and collects legal fees. A separate management services organization owns the technology, brand infrastructure and back office, and outside investors can own that entity.
Why can’t investors own law firms directly? ABA Model Rule 5.4 bars fee-sharing with non-lawyers and restricts firm ownership to practising lawyers. Arizona eliminated its version in 2021. Utah, Puerto Rico and Washington D.C. run partial exceptions. Most states still enforce it.
Does AI replace lawyers at Irving? Not in the current setup. Irving employs a mix of lawyers and engineers and uses software trained on large language models to handle research and drafting, with senior lawyers on judgment and client work.
Who else is doing this? Norm Law, backed by Bain Capital and Blackstone money, and Eudia Counsel, backed by General Catalyst. Established firms including McDermott Will & Schulte have considered converting to MSO structures.
The Business Model Analyst Take
Watch the ownership structure, not the technology.
Every established firm can buy the same models Irving uses. Kirkland is spending half a billion dollars to prove it. What Kirkland cannot do inside a partnership is convert that spending into equity someone will pay a multiple for, and that gap is the entire opportunity Fox has identified.
The pattern generalises past law. Any profession that bills hours through a leverage pyramid runs into the same wall: accounting, consulting and medicine have all met private capital through some version of the same two-entity workaround. The constraint was never regulatory in the way partners told themselves. Partners liked owning all of the profit. Once one firm converts its technology into a sellable asset and its competitors keep treating the same technology as overhead, the choice stops being philosophical.
Fox is 68, not practicing, and has no defined role. He is not trying to run a law firm. He is trying to own the thing law firms will have to buy, which is the same trade Harvey ran to a $3 billion valuation by selling to firms rather than competing with them. Irving does both at once. If it works, the law firm was the distribution channel and the software company was the business.