
Conagra, General Mills and Kraft Heinz are loading protein into frozen dinners for shoppers who have lost their appetite. Nestlé’s own numbers say the category’s flagship brand sells mostly to people taking nothing at all.
Packaged food companies are not building a defensive product line for a shrinking cohort of medicated eaters. They are using GLP-1 drugs as permission to charge more per calorie to the entire store. Nestlé says only 20% of Vital Pursuit buyers take a weight-loss medication, and 40% had never bought frozen food before. The badge recruits shoppers. The protein inside it costs three times what the starch it replaces costs, and at Conagra’s disclosed margins, every dollar of that protein needs $1.32 of manufacturer price before a retailer adds anything.
The Scene in Omaha
Executives at Conagra stood over trays of microwaved eggs, potatoes and sausage in an Omaha test kitchen, pouring cheese sauce out in a slow orange ribbon. Nobody had eaten anything. Ashley Lind, who runs behavior science at the company, studied the breakfast bowl and asked herself whether it looked satisfying.
The Wall Street Journal reported that scene on August 18, and it is a good one. It is also a scene about appetite, and appetite is the wrong variable. The number that decides whether any of this works sits in Conagra’s fiscal 2026 income statement, filed six weeks earlier, where adjusted gross margin came in at 24.0% and the new chief executive halved the dividend.
What Happened
Amira McKee and Jesse Newman reported that Conagra is running dozens of product tests aimed at people whose hunger the drugs have erased. Bob Nolan, the company’s senior vice president of growth science, told them his team has been reading credit-card data, social posts and late-night delivery orders to work out what a medicated eater still wants.
The forecasts behind the effort are large. Morgan Stanley projects 55 million Americans, or 15% of the population, on GLP-1 drugs by 2035. KPMG estimates users eat about one-fifth fewer calories. JPMorgan sees the drugs draining $30 billion to $55 billion of annual food and beverage revenue as soon as 2030, which is three to five times Conagra’s entire yearly sales. PwC counts a GLP-1 user in one of every five US households, double the share at the start of 2025.
Tom Frain, Conagra’s vice president of culinary innovation, expected to be told to design kale and fiber supplements. He got the opposite brief: familiar food, smaller portions, more protein. He is now working on a buffalo mac and cheese carrying 40 grams of it, with a custom marinade and grill marks printed onto the chicken. A frozen burrito at the same protein load died in development because the tortilla could not hold the filling. A Duncan Hines “protein boost” brownie recipe doubles the protein by adding blended cottage cheese and peanut butter, and raises the calorie count while it does so.
General Mills went a different route and built an AI persona. “Lisa,” assembled from consumer interviews and sales data, is a woman in her late thirties or forties with a long dieting history who now eats small meals through the day. A second persona, “Josh,” told the company a bar needs more than 15 grams of protein to earn a place in his daily stack. General Mills plans to test a protein bar under a new brand called Prot Edge. Kraft Heinz is chasing the household rather than the patient, targeting what its executives call the “GLP-1 adjacent.”
The Backstory
The industry has been bracing for this since late 2023, when Walmart’s then-US president John Furner told Bloomberg that customers on hunger suppressants were buying slightly fewer calories. Packaged food shares fell on the remark.
The measurement arrived two years later. Sylvia Hristakeva and her Cornell co-authors, publishing in the Journal of Marketing Research on December 18, 2025, matched Numerator transaction records for roughly 150,000 households against repeated surveys about medication use. Households cut grocery spending 5.3% within six months of starting a GLP-1, more than 8% among higher earners, and cut spending at fast-food and coffee chains by about 8%. Savory snacks fell around 10%. Sweets and baked goods fell about as far. Yogurt and fresh produce went up.
The drug side kept getting cheaper and easier to start while all this was measured. Novo Nordisk’s oral Wegovy landed in January at as little as $149 a month against $349 for the injection, a repricing we covered in Novo Nordisk’s Wegovy Pill Is Winning Back Share by Undercutting Novo Nordisk. Cheaper entry points widen the cohort that stops eating.
Nestlé moved first on product. In May 2024 it announced Vital Pursuit, its first major US brand in nearly three decades, a line of portion-aligned frozen meals carrying at least 20 grams of protein each. Conagra followed with a “GLP-1 Friendly” badge on 26 Healthy Choice meals in early 2025. Lactalis launched Ratio Pro Fiber yogurt at 20 grams of protein and 10 grams of fiber. Danone put out an Oikos drink aimed at muscle retention. Kraft Heinz will ship PowerMac, a version of Kraft Mac & Cheese at 17 grams of protein and 6 grams of fiber, this year.
Every one of those companies is doing this from a weak financial position. Conagra closed fiscal 2026 on May 31 with net sales down 2.9% to $11.3 billion, a reported diluted loss of $4.00 a share after goodwill and brand impairments, free cash flow down 24.9%, and net leverage at 3.83 times. John Brase took over as chief executive and cut the quarterly dividend from 35 cents to 17.5 cents. General Mills reported net sales down 5% to $18.4 billion, an operating profit down 73%, and a net loss for the year, while announcing a $3 billion cost-savings target by fiscal 2030. Kraft Heinz posted second-quarter net sales down 1.4% with price up 1.3 points and volume and mix down 2.6, paused the breakup it announced in September, and redirected $600 million into US marketing and R&D instead.
Read those three prints side by side and one pattern repeats: price up, volume down. That is the condition the protein program has to fix.
The Plan
Each company picked a different amount of money to bet, and the amounts track balance sheets rather than conviction.
Conagra chose the cheapest option available. The “GLP-1 Friendly” badge went onto Healthy Choice meals that, in the company’s own account, already met the criteria. No reformulation, no new brand, no capital. Company executives told the Journal they do not yet see enough GLP-1 demand to justify dedicated products, and are folding the medicated shopper into the broader health-conscious one.
Kraft Heinz chose the middle. PowerMac extends an existing megabrand into the protein claim without building anything new around it, and the “GLP-1 adjacent” framing quietly widens the target from the patient to whoever else eats in that kitchen.
General Mills is spending the most, on a new bar brand plus what its Q3 call described as a Protein One and Fiber One renovation, sitting alongside Cheerios Protein. Jeff Harmening has told investors that fiscal 2027 growth will come from protein, fiber, bold flavors and pet humanization, in that order.
Nestlé, two years ahead of all of them, is escalating. Its newest Vital Pursuit pizzas carry 33 grams of protein and 17 grams of fiber against 22 and 4 in the originals.
Nobody agrees on the dose because there is no dose. The US Department of Agriculture’s Food Safety and Inspection Service approved “GLP-1 Friendly” for Conagra and Nestlé on the narrow ground that the labels also carry accurate protein and fiber statements, and the agency has said plainly that no regulatory standard exists for the term. Seventeen grams qualifies at Kraft Heinz. Forty grams qualifies at Conagra. Both are legal.
The Business Model Angle
Start with who is buying. A Nestlé USA executive told Food Dive in March that only 20% of Vital Pursuit consumers take a GLP-1 medication, and that 40% of the brand’s buyers had never purchased frozen food before. Associated Press reporting put the same finding from the revenue side: 77% of Vital Pursuit sales come from households where nobody is on the drug.
That single split rewrites the strategy. Nestlé did not build a lifeboat for a category losing calories. It built a recruitment tool, and the recruitment worked on people the drug never touched. For the wider portfolio context behind that bet, see our Nestlé SWOT analysis. Conagra’s own executives described the same logic to the Journal when they said they are wrapping GLP-1 needs into the preferences of health-conscious shoppers generally. The badge is a price and mix lever wearing a pharmacology costume, and it pulls buyers into frozen food who had been avoiding the aisle.
Now the cost side, which nobody in the coverage has priced.
Boneless skinless chicken breast traded at a weighted average of 122.41 cents a pound in the USDA’s Weekly National Chicken Report for the week ended July 31, against 197.93 cents a year earlier. At 23.1 grams of protein per 100 grams of raw breast, putting 40 grams into one entrée takes about 173 grams of raw meat, or roughly 47 cents of ingredient. Go the dairy route instead and it gets worse fast. USDA Dairy Market News quoted whey protein isolate between $14 and the upper $14s a pound in the week of August 10, with whey protein concentrate 80% at $12 to $13. Forty grams of protein from isolate costs about $1.40. One truckload of WPC 80% now approaches half a million dollars, and the same report notes buyers pushing back on price.
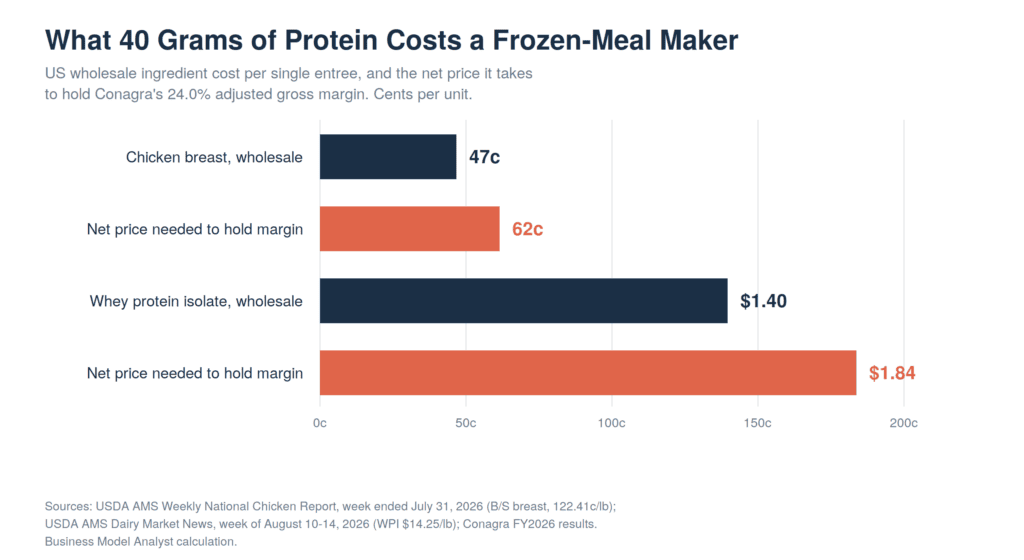
Conagra reported a 24.0% adjusted gross margin for fiscal 2026, which puts cost of goods at 76 cents of every sales dollar. Every dollar of added ingredient cost therefore needs $1.32 of manufacturer net price to leave the margin rate untouched. The chicken route needs 62 cents. The isolate route needs $1.84. A retailer then applies its own markup on top of that, so the shopper carries more.
Set that against demand. KPMG puts the calorie cut at about one-fifth. Cornell puts the grocery dollar cut at 5.3%. Divide one by the other and the medicated shopper is already paying about 18% more for every calorie she buys. The protein program is a bid to be the seller on the receiving end of that trade rather than the loser on the other side of it.
Which explains the Duncan Hines brownie. A company responding to a calorie-suppression drug launched a recipe that raises the calorie count. That is not incoherent. The objective function was never calories. It is revenue per eating occasion, and protein is the only ingredient shoppers currently pay a premium for. If you want the general version of this mechanic, our cost structure in the Business Model Canvas breakdown covers how input mix decides which price moves a company can survive.
The Risk
The 18% figure stitches two studies together. KPMG measured calories across all eating occasions; Cornell measured dollars in one panel over one window. The gap is directionally sound and it is not a clean same-panel measurement, so treat it as an order of magnitude rather than a coefficient.
The aggregate hit may be smaller than the headline forecasts imply. Colin Guheen and Paul Baisley of Capital One’s food and agribusiness group did the arithmetic bluntly: 10% of the population buying 20% less food produces a 2% drop in total food purchases. JPMorgan’s $30 billion to $55 billion looks enormous next to Conagra. Next to US food spending it is a rounding adjustment, spread unevenly.
Persistence cuts the other way too. Hristakeva found the effect fading over the year and becoming hard to separate from baseline after patients quit. Earlier work in the same dataset showed candy and chocolate rebounding above pre-adoption levels post-discontinuation.
The counterweight to the whole cautious reading comes from Circana, which projects that households containing a GLP-1 user will account for more than a third of US food and beverage sales within five years. Numerator’s panel work for Morgan Stanley adds the sharper point: these households were already spending more than $150 a month above everyone else on groceries before they started. The drugs are removing the heaviest buyers from the heaviest categories, which is worse for the industry than a flat 5.3% suggests.
Protein pricing is the other exposure. Nonfat dry milk is at record highs and whey markets are tight, so a company that reformulates its portfolio around dairy protein is taking a commodity position it cannot exit quickly. Chicken looks cheap at 122 cents because the industry is in a glut, and gluts end. We walked through how that pass-through actually moves in Chicken Got 37% Cheaper. Your Grocery Bill Got 1.4% Cheaper.
Then there is the claim itself. No agency defines “GLP-1 Friendly,” which makes it free to use and free for private label to copy. Store brands can print protein grams as cheaply as Conagra can, and they do not carry a 3.83 times leverage ratio. A term nobody owns produces no defensible margin, which is the same trap the industry walked into with flavor, covered in Everything Tastes Like Pickle Because Price Cuts Stopped Working.
One last wrinkle worth watching. Conagra abandoned focus groups years ago because testers loved products that later flopped. General Mills responded to the same reliability problem by building a simulated focus group out of historical consumer data. Whether a persona trained on pre-drug behavior can forecast post-drug behavior is an open question, and the company is shipping brands on the answer.
Quick Questions
Are GLP-1 drugs actually shrinking packaged food sales? Yes, and less than the forecasts suggest. Cornell measured a 5.3% grocery spending cut in affected households and about 8% at limited-service restaurants. Capital One’s analysts translate current adoption into roughly a 2% drop in total food purchases.
Why protein specifically? Doctors tell GLP-1 patients to raise protein intake to limit muscle loss during rapid weight loss, and patients talk about it constantly online. It is also the only nutrient shoppers currently pay a premium for, which makes it the one reformulation that can carry a price increase.
Does “GLP-1 Friendly” mean anything legally? No. USDA’s Food Safety and Inspection Service cleared the term for Conagra and Nestlé because their labels also carry accurate protein and fiber statements, and the agency has stated there is no regulatory standard for the phrase itself.
Who is buying these products? Mostly people not on the drugs. Nestlé reports that 20% of Vital Pursuit consumers take a GLP-1, with 77% of sales coming from non-user households, and that 40% of buyers were new to frozen food.
Is this a defensive move or a growth move? The buyer data says growth. The companies are recruiting health-conscious shoppers with a label the medicated cohort inspired, which is a better business than replacing lost calories one for one.
The Business Model Analyst Take
Watching chefs in Omaha argue about whether a breakfast bowl looks satisfying, you would think the problem is culinary. It is procurement.
Big Food built a machine that turns the cheapest calories on earth into shelf-stable pleasure and sells as much of it as possible. The GLP-1 shopper breaks that machine at the input, not the output. Replacing starch and fat with protein means swapping the cheapest thing the industry buys for one of the most expensive, in smaller portions, to a customer eating a fifth less, at three companies whose combined story this year is impairments, a halved dividend, a paused breakup and a net loss.
The honest read is that nobody at Conagra, General Mills or Kraft Heinz expects the medicated cohort to pay for this on its own. Nestlé already ran the experiment and published the answer: four in five buyers of the flagship GLP-1 brand take no medication. What the drugs supplied was not a customer segment. They supplied a socially acceptable reason for the packaged food industry to raise price per calorie in a year when raising price the ordinary way stopped working.
That is a real strategy and it may well work. It is also a strategy with no moat. The term is unregulated, the protein is a commodity anyone can buy, and the private label brand two shelves down can print the same grams for less. Conagra is formulating products for 2028 while watching the obesity drug patent pipeline. The pipeline it should watch more closely is the one at ALDI.