
A consortium bought roughly a third of Liverpool at about $7.1 billion. The largest single contributor is the one investor with no seat in the room, and the structure that put him there is the thing worth studying.
Fenway Sports Group agreed on 14 August 2026 to sell a minority stake in Liverpool FC to 1892 Holdings, a consortium managed by Amit Bhatia. K5 Sports, a fund inside K5 Global with Jeff Bezos as its lead investor, supplied the largest contribution at more than $1 billion. Bhatia becomes vice chairman. Elaine Saverin and K5 co-founder Bryan Baum join the board. Bezos does not.
Three people take board seats out of this transaction. The person who put in more money than any of them takes none, and the paperwork suggests he never asked for one.
What Happened
FSG announced a definitive agreement to sell a minority equity stake in Liverpool to 1892 Holdings, named for the year the club was founded. The consortium is led and managed by Bhatia, with money from Bhatia and the Mittal Family Trusts, K5 Sports, and EE Capital, the family office of Elaine and Eduardo Saverin.
Reuters and ESPN put the stake at about one third. CNBC reported a valuation near $7.1 billion and said K5 Global’s contribution of more than $1 billion was the largest in the group. ESPN’s sourcing puts the club nearer £5.5 billion, or $7.45 billion. The Wall Street Journal said more than $7 billion. Sky Sports landed around £6 billion.
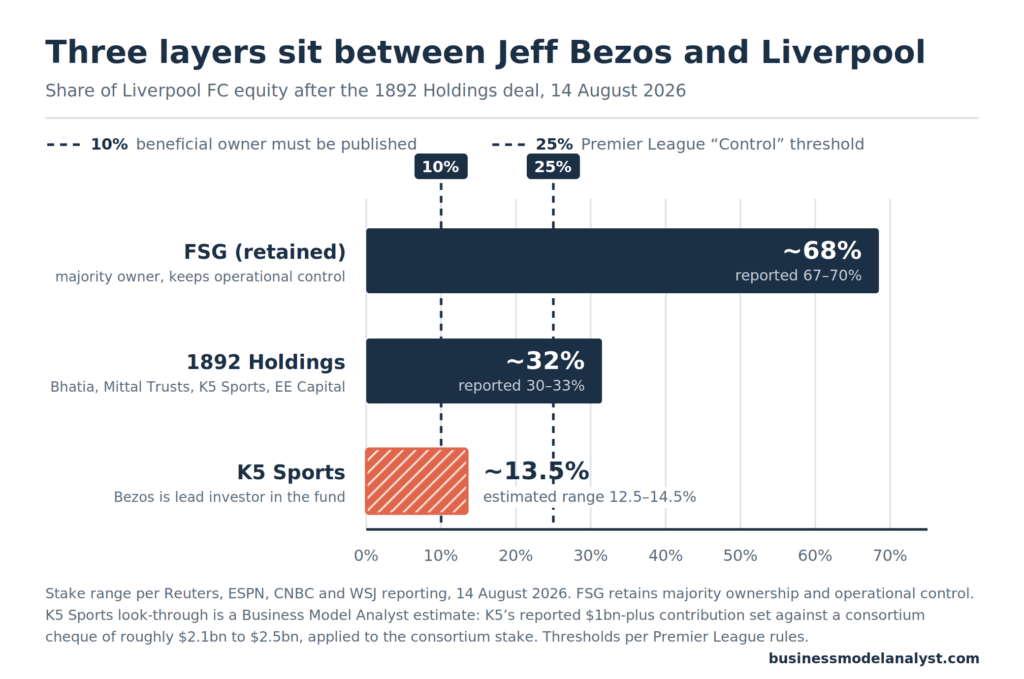
FSG president Mike Gordon framed the sale around long-term thinking and said the consortium shares the group’s philosophy. FSG keeps majority ownership and operational control. Bhatia becomes vice chairman and joins an expanded board alongside Elaine Saverin for EE Capital and Baum for K5 Sports. Bezos will not sit on the board, with Baum acting as his representation. Corestone Capital Advisors introduced the parties. A&O Shearman advised FSG and Liverpool with support from Deloitte, and Latham & Watkins acted on the buy side.
The club has said the money does not change its transfer plans for the current window.
The Backstory
FSG, then New England Sports Ventures, bought Liverpool out of a lender-forced sale in October 2010 for around £300 million, roughly $480 million at the time. Anfield has taken outside money before. LeBron James bought about 2% of the club in 2011 for £4.7 million and later converted into a minor FSG partnership. RedBird Capital Partners paid roughly $735 million for a stake in FSG in March 2021. Dynasty Equity paid a reported £164 million for a small slice in September 2023. None of those buyers took control, and none of them ran the club.
The financials underneath the price are healthier than the league table suggests. For the year to 31 May 2025, Liverpool booked record revenue of £703 million, up £88 million, with media income rising £60 million to £264 million on the back of a Champions League run. The club reported a £15 million pre-tax profit and £8 million after tax, reversing a £57 million loss the year before, and carried the highest wage bill in the Premier League. Then Liverpool finished fifth, spent more than £400 million on players in a single window, changed managers, and lost Mohamed Salah.
K5 Global is the newer name here. Michael Kives and Baum founded it in 2018. Kives came out of CAA as a talent agent with a client list that ran from Arnold Schwarzenegger to Warren Buffett, after a stint in Bill Clinton’s post-presidential office. The firm registered with the SEC in 2021, runs early-stage, growth and pre-IPO vehicles alongside K5 Sports, and had deployed roughly $1 billion across about 174 direct investments as of early 2024. Adviser filings put the wider platform around $5.8 billion.
K5 also spent 19 months inside the FTX wreckage. Alameda Research bought about a third of K5’s general partnership in mid-2022, and the FTX estate sued the firm and both founders in June 2023 seeking to claw back some $700 million. They settled on 31 January 2025, with the estate retaining its investment in the firm. FTX Recovery Trust chief executive John Ray called K5 a bright spot in the portfolio.
The Plan
FSG is selling economics and keeping the operating business. Bhatia runs the consortium and takes the vice chairmanship, which is the visible job. The buyers also hold an option to move to majority ownership at a valuation near $8 billion inside the next 12 months, a term we covered when the deal was still in draft.
For Bezos, the plan is narrower. He gets exposure to a Premier League franchise, a relationship with Bhatia and the Mittal family, and none of the administration. K5 handles the vehicle, the reporting, the seat, and the regulatory correspondence. He pays fees for that.
The Business Model Angle
Run the arithmetic the coverage skipped.
At a $7.1 billion valuation and a stake between 30% and 33%, the consortium wrote a cheque of roughly $2.1 billion to $2.5 billion. K5’s reported contribution of more than $1 billion is therefore somewhere between 40% and 47% of the group’s money, and possibly more. Push that through the consortium’s stake and K5 Sports holds a look-through position in Liverpool of about 12.5% to 14.5%.
Now set that against the two numbers the Premier League cares about. The league lowered its “Control” threshold to 25% from 30%, so 1892 Holdings at roughly a third clears it and the consortium sits inside the Owners’ and Directors’ Test as an owner. Beneficial owners at 10% or more must be published. K5’s look-through clears that line too. Bezos, sitting one layer further down as an investor in the fund, is the only principal in this deal whose position gets divided twice before anyone measures it.
Directors get measured differently. The Premier League maintains a public register of club directors, requires a signed Owners’ and Directors’ Declaration, and applies the test on a continuing basis rather than once at appointment. Its list of triggers includes a Potential Disqualifying Event, which reaches any live investigation by a competent authority anywhere in the world into conduct that would disqualify if proven. A board seat is a permanent, personal, cross-border disclosure obligation attached to a name.
That obligation has a specific cost for this particular name. Amazon walked away from UK Premier League rights after the 2024-25 season and did not bid in the current cycle, but Prime Video holds first-pick Champions League Tuesday rights in the UK, Ireland, Germany and Italy through 2030-31, and buys Thursday Night Football and NBA packages in the United States. The company Bezos founded and still chairs is one of the largest buyers of the inventory that European clubs sell collectively. Putting an Amazon-affiliated director inside a club boardroom while media strategy, UEFA distributions and European Club Association positioning get discussed creates a conflict that lawyers price.
So look at what K5 sells. Kives spent a career converting a contact list into deal flow, and the Liverpool position is that model at full scale. K5 supplied close to half the consortium’s capital and took one of three consortium board seats. The investor who supplied most of K5’s share took zero. In exchange, Bezos gets participation without a register entry, without a declaration form, and without a continuing personal test administered by a league his company negotiates against elsewhere.
There is a second thing K5 gets. This one position is larger than everything the firm deployed across its first six years. K5 turned a client relationship into a fee-bearing, carry-bearing anchor asset and a permanent reference for its next sports fund. Bezos wrote a cheque worth about 0.4% of his net worth. Kives wrote his firm a new business line.
The Risk
The simple explanation is that Bezos did not want the job. He runs Blue Origin, owns The Washington Post, and a Premier League board seat is unpaid committee work in a city he does not live in. That reading is fair, and it explains the empty chair. It does not explain the fund. A billionaire who wanted a passive position could have taken one directly and skipped the management fee.
The option is the bigger threat to this structure. If 1892 Holdings moves to majority at around $8 billion inside 12 months, control changes the regulatory picture and the layers stop working as insulation. Distance is cheap while you are a minority holder and expensive once you are the owner.
Then there is what the money can do. The club has already said the investment does not alter transfer plans, and the squad cost ratio regime arriving for 2026-27 caps how much of any equity injection can reach the pitch. Value has to come from commercial growth, stadium yield and media, which is the slow part.
Concentration cuts against K5 harder than against Bezos. Over $1 billion in one illiquid asset, held by a firm whose entire prior deployment was about the same size, is a bet that elite football valuations keep compounding on the same scarcity logic that repriced the Lakers at 22.7 times revenue. If they flatten, the fund carries the mark.
And the price itself remains unsettled. Reported valuations moved from $5.9 billion to $8 billion inside one week from outlets with good sourcing. Every ratio above inherits that spread.
Quick Questions
How much of Liverpool did the group buy? Roughly 30% to 33%, per Reuters, ESPN and CNBC. FSG keeps the majority and operational control.
What is Liverpool worth now? Reporting on 14 August clustered around $7.1 billion to $7.45 billion. The Wall Street Journal said more than $7 billion. The option to buy control is priced nearer $8 billion.
Why does Bezos have no board seat? He invested through K5 Sports rather than directly, and K5 co-founder Bryan Baum takes the seat on the fund’s behalf. Premier League directors go on a public register and stay inside a continuing eligibility test.
What is 1892 Holdings? The consortium vehicle, named for Liverpool’s founding year, managed by Amit Bhatia with capital from Bhatia and the Mittal Family Trusts, K5 Sports and EE Capital.
Does this money buy players? No. Liverpool has said the investment does not change transfer plans for this window.
The Business Model Analyst Take
Every story about this deal leads with the richest name on the cap table, which is the least interesting fact in it. Bezos spent about 0.4% of his net worth on a minority slice of a football club and took no operating role. That is a rounding error dressed as a headline.
The transaction that matters is the one Michael Kives closed. He assembled somebody else’s billion dollars into a fund, placed it inside a consortium he does not manage, took a board seat his firm could not have earned on its own balance sheet, and now charges fees and carry on the largest position K5 has ever held. Access was the scarce input, and K5 sold it at institutional priciFng.
Buyers at this level are not short of money. They are short of clean ways to hold things. FSG understood that and split the asset into economics and control. K5 understood it and split the buyer into capital and identity. The empty chair at Anfield is not an oversight, and it is worth more to Bezos than the seat would have been.