
The incoming CEO says the small-format push is about reaching more customers. Read the margin math and it is really about feeding a retail media network with a structural weakness only more stores and a marketplace can fix.
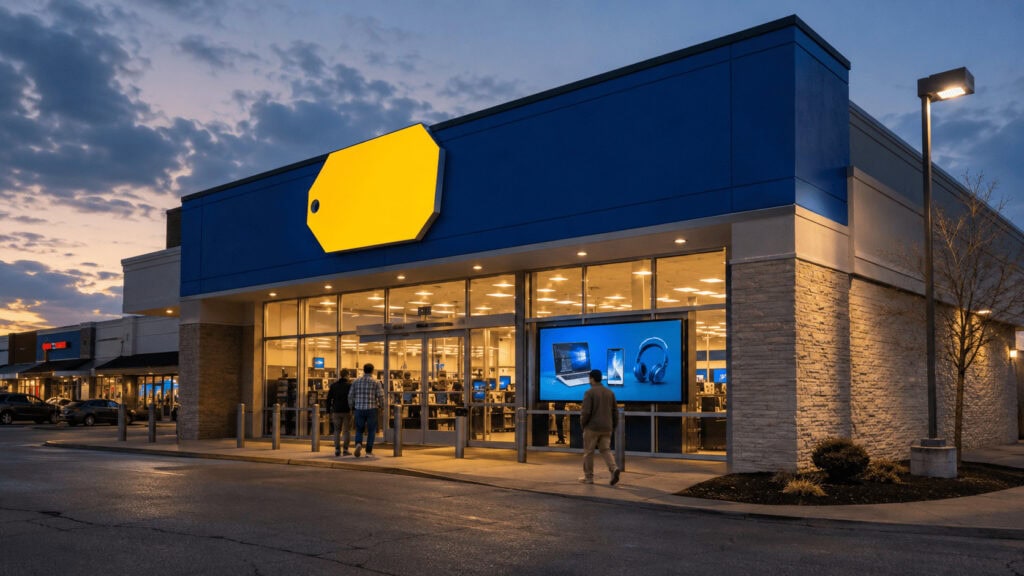
Best Buy is opening 12,000 to 15,000 square foot stores in towns its 40,000 square foot boxes never served, and incoming CEO Jason Bonfig is selling it as a reach story. The sharper read: every new store is a first-party data node and an ad-inventory surface for Best Buy Ads, a business already collecting more than $900 million a year at margins the core retail operation cannot touch. The stores are the cheap part. The ad network is the point.
Best Buy told CNBC this week that it is shrinking to grow. Bonfig, who takes over from Corie Barry on November 1 as the company’s sixth CEO, described compact stores that let the chain enter markets too small to carry a full-size showroom. Reopening in Jonesboro after a tornado, a 28,000 square foot location on Cape Cod, Canadian stores as small as 7,000 square feet. It sounds like a real estate tweak. It is the visible edge of a much larger repositioning, and Bonfig is the executive who built the invisible part.
What Happened
Bonfig used his pre-CEO media run to lay out a small and medium format store strategy. Small stores run 12,000 to 15,000 square feet, medium ones 20,000 to 25,000, against a traditional footprint near 40,000. He was explicit that the small stores add to the fleet rather than replace it, calling them an enhancement that reaches customers and markets Best Buy was simply not in before.
The framing landed at a delicate moment. Best Buy stock sits roughly 20% below its late-2021 peak of $138. The company guides full-year comparable sales to a range of minus 1% to plus 1%, which is a polite way of saying flat. CNBC noted that in the third quarter of fiscal 2026 net income fell to $140 million from $273 million a year earlier. Tariffs and a spike in memory chip prices are pushing electronics costs up. This is not a growth business in its core category, and everyone on the call knows it.
The Backstory
Bonfig’s resume is the tell. Before the CEO nod he was chief customer, product and fulfillment officer, and before that chief merchandising officer. He led the creation of Best Buy’s US Marketplace and the scaling of Best Buy Ads, and he oversees Best Buy Canada. The board did not pick a store operator to run a store turnaround. It picked the person who built the two highest-margin businesses inside the company and told him to make them the center of gravity.
He has said the quiet part in public. “We’re not just a retailer anymore.” His stated pillars include turning Best Buy into a retail, media, advertising and technology company. That is not a line about square footage. That is a line about where the profit is supposed to come from over the next five years.
The Real Play
Best Buy Ads is a retail media network. It sells brands like Samsung, Sony and LG access to Best Buy’s shoppers, on the website, on store screens, on the building itself, and increasingly across connected TV and sports content. The network runs about 750 advertisers and collects more than $900 million a year. It claims a 93% revenue identification rate, meaning it can tie an ad someone saw to a purchase they made, which is the currency advertisers actually pay for.
Now connect it to the stores. A retail media network monetizes two things: shopper data and attention. Every Best Buy location is a machine that produces both. A new 12,000 square foot store in a market Best Buy skipped is not mainly a place to sell televisions at a thin margin. It is a new stream of high-intent shopper data and a new set of physical ad surfaces, the in-store “takeover” formats the network already sells. The smaller stores lower the cost of adding those nodes, because you no longer need enough local demand to justify a 40,000 square foot lease. Bonfig is not shrinking the retail footprint. He is cheapening the cost of expanding the data-and-attention footprint.
The Margin Math
Look at the two businesses side by side and the strategy explains itself. Best Buy’s fiscal 2026 gross margin was about 22%, operating margin barely above 3%, net margin around 2.5% on $41.7 billion of revenue. Selling electronics is a business where you keep two or three cents on the dollar. Product margins are still falling as tariffs and component costs bite.
Retail media is the opposite kind of business. It carries no cost of goods, and its incremental margins run far higher than any box of hardware. Best Buy’s own earnings language is unusually blunt about this. In both its most recent quarters, the company said its gross profit rate held up because growth in Best Buy Ads and Marketplace offset lower product margins. In plain terms, the ad and marketplace layer is the only thing keeping the margin line from sinking. A dollar of ad collections does more for operating profit than many dollars of TV sales. That is why a $900 million-plus ad business matters more to the P&L than another point of comparable store sales, and why the store strategy is bent toward feeding it.
The Risk
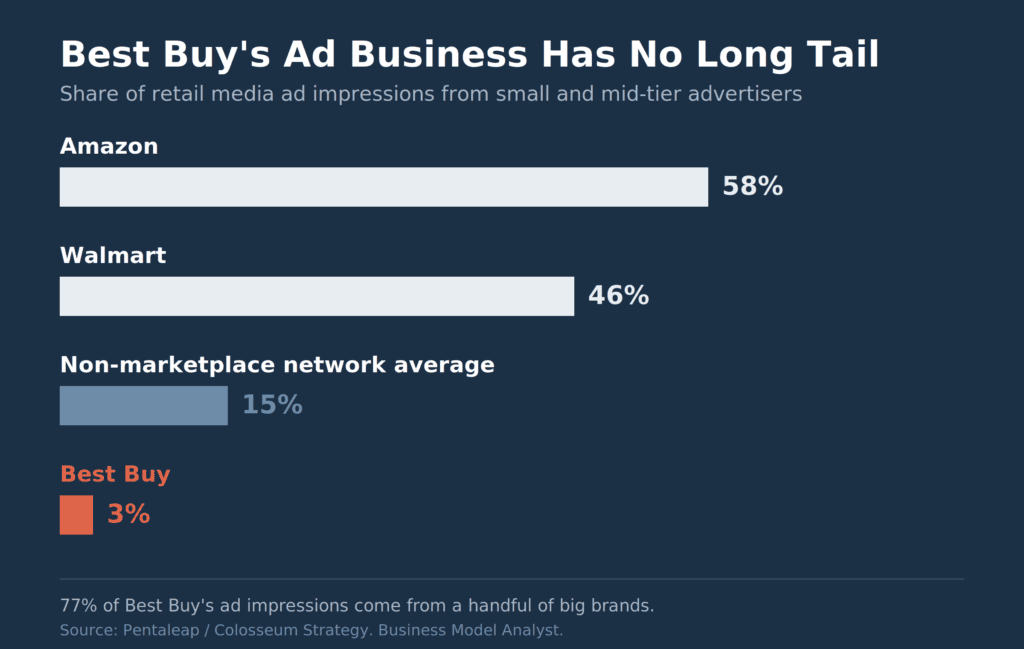
Here is the flaw the whole strategy is quietly built to fix, and the reason to be skeptical of the ceiling.
Best Buy Ads has almost no long tail. Research from Pentaleap and Colosseum Strategy found that 77% of Best Buy’s ad impressions come from a handful of major brands, with just 3% from small and mid-tier advertisers. Compare that to Amazon at 58% and Walmart at 46%. Even the average non-marketplace retail media network pulls 15% from the long tail. Best Buy sits far below its own category.
That concentration is dangerous. If two or three big electronics brands trim their ad budgets in a soft year, a large slice of the ad business goes with them. The fix is a marketplace. Amazon and Walmart have deep advertiser tails because thousands of third-party sellers advertise to defend their listings. Best Buy is relaunching a US marketplace with Mirakl for exactly this reason, to manufacture the long tail of sellers who then become the long tail of advertisers. Its Canadian marketplace, where roughly one in four shipped items comes from a third-party seller, is the proof of concept.
The harder problem is scale. Retail media pays out in proportion to traffic, and Best Buy’s traffic is a fraction of Amazon’s or Walmart’s. Smaller stores add reach, but a 12,000 square foot store in a small market does not generate the ocean of shopper data that makes Amazon Ads an $88 billion machine. The pivot is the correct strategy. It is also structurally capped. Best Buy can build a good retail media business. It probably cannot build a category-defining one, and its stock will eventually be priced on which of those two it turns out to be.
Quick Questions
Is Best Buy really shrinking its stores? No. It is adding smaller-format stores alongside its full-size ones to enter markets that could not support a 40,000 square foot showroom. The traditional fleet stays.
How big is Best Buy Ads? The retail media network runs about 750 advertisers and collects more than $900 million a year, with a claimed 93% revenue identification rate linking ads to purchases.
Why does a marketplace matter for an ad business? Third-party sellers advertise to promote their listings, which gives marketplace-based networks like Amazon and Walmart a deep base of small advertisers. Best Buy’s ad network is heavily concentrated in a few big brands, and a marketplace is how it plans to widen that base.
Can this fix Best Buy’s growth problem? It can lift margins, since ads and marketplace fees are far more profitable than selling hardware. Whether it lifts the whole company depends on traffic scale, where Best Buy is a distant third to Amazon and Walmart.
The Business Model Analyst Take
The “smaller stores to grow sales” headline is the least interesting true thing about this story. The interesting thing is that Best Buy has stopped believing it can win as a box retailer and started rebuilding itself as a media and marketplace company that happens to operate stores. The board confirmed it by handing the company to the man who built the ad network, not the man who runs the floor.
This is the same move Walmart ran with Walmart Connect, and the logic is identical: a low-margin retailer sits on shopper attention it used to give away for free, and it decides to charge for it. The difference is scale and structure. Walmart’s ad business is diversified and enormous. Best Buy’s is smaller and dangerously concentrated in a few brands, which is why the marketplace relaunch and the cheap-to-build small stores are not side projects. They are the supply lines for the only part of the business with real margin leverage.
Watch two numbers, not the store count. Watch whether Best Buy Ads collections keep climbing, and watch whether the long-tail share moves off 3% as the marketplace fills in. If both happen, Bonfig is quietly turning a dying-category retailer into a profitable media company. If they stall, the small stores are just a cheaper way to keep selling televisions at three cents on the dollar.