The electronics retailer beat its own three-month-old forecast by more than three points, raised full-year guidance, and quietly told investors the second half returns to 1% to 3%. Its Canadian segment, running the same strategy without the U.S. computing cycle, comped negative.
Best Buy reported second-quarter comparable sales growth of 4.1% on August 27, 2026, against the roughly 1% it guided in May. Domestic comps rose 4.5%. Adjusted diluted EPS reached $1.47 versus $1.28. Management raised full-year revenue guidance to $42.3 billion to $42.8 billion and adjusted EPS to $6.70 to $6.90.
Underneath the beat sit two numbers that complicate the turnaround story. Domestic gross margin improved 60 basis points, and $34 million of IEEPA tariff refunds accounts for about 37 of them. And Best Buy’s International segment, which sells the same categories through the same operating model in Canada, posted a 1.8% comparable sales decline in the same quarter.
Corie Barry hands the CEO seat to Jason Bonfig on November 1. This was her last full quarter reporting results, and it was a good one. Whether it was a good quarter for the business model is a different question.
What Happened
Enterprise revenue for the 13 weeks ended August 1, 2026 came in at $9.779 billion, up 3.6% from $9.438 billion. Comparable sales grew 4.1% against 1.6% a year earlier. Operating income reached $421 million, or 4.3% of revenue, against $251 million and 2.7%. Net earnings hit $315 million.
Diluted EPS rose 70% to $1.48. That headline needs a footnote. Best Buy booked $114 million of restructuring charges in the year-ago quarter, worth $0.39 per share after tax, from a labor and store optimization program. This quarter it recorded a $6 million reduction to previously planned charges. On an adjusted basis, EPS grew 14.8%, from $1.28 to $1.47. Fifty-five of the seventy points of reported profit growth come from the absence of last year’s charge.
The Domestic segment delivered $9.07 billion of revenue, up 4.3%, on 4.5% comparable growth. Online revenue reached $3.00 billion, 33.1% of domestic revenue against 32.8%. International revenue fell 4.2% to $709 million.
Management raised guidance across the board:
| Metric | March 2026 guidance | August 2026 guidance |
|---|---|---|
| Revenue | $41.2B to $42.1B | $42.3B to $42.8B |
| Comparable sales | (1.0)% to 1.0% | 1.9% to 3.0% |
| Adjusted operating income rate | 4.3% to 4.4% | 4.4% to 4.5% |
| Adjusted diluted EPS | $6.30 to $6.60 | $6.70 to $6.90 |
| Capital expenditures | ~$750M | ~$750M (unchanged) |
Q3 guidance: comparable sales of 1.0% to 3.0%, adjusted operating income rate of 4.1% to 4.2%.
The board declared a quarterly dividend of $0.96 per share, payable October 8. Best Buy returned $239 million in the quarter, $203 million of it in dividends and $36 million in buybacks. Year to date, buybacks total $36 million against a $300 million annual plan.
The Backstory
Best Buy has spent three years hunting for a demand story that does not depend on a hardware refresh. The company launched a U.S. digital Marketplace in FY26 and scaled Best Buy Ads, roughly doubling its ad partner count. Both show up in the FY27 gross margin commentary alongside services. Both also show up in SG&A, where Marketplace and Ads investment is one of three named drivers of higher spend.
Barry announced her departure earlier this year. Bonfig, previously Chief Customer, Product and Fulfillment Officer, takes over November 1. In May he laid out four priorities, the first of which was advancing Best Buy as a retail, media and advertising, and technology company. That sequencing matters. The incoming CEO put media and advertising ahead of the store network in his own list.
CFO Matt Bilunas, who guided the quarter to about 1% comp growth in May, has since left the company. His May commentary is the cleanest available statement of what Best Buy expected: comps had started strong in May at high single digits, and the full-quarter outlook was about 1% because June began lapping the prior year’s gaming launch.
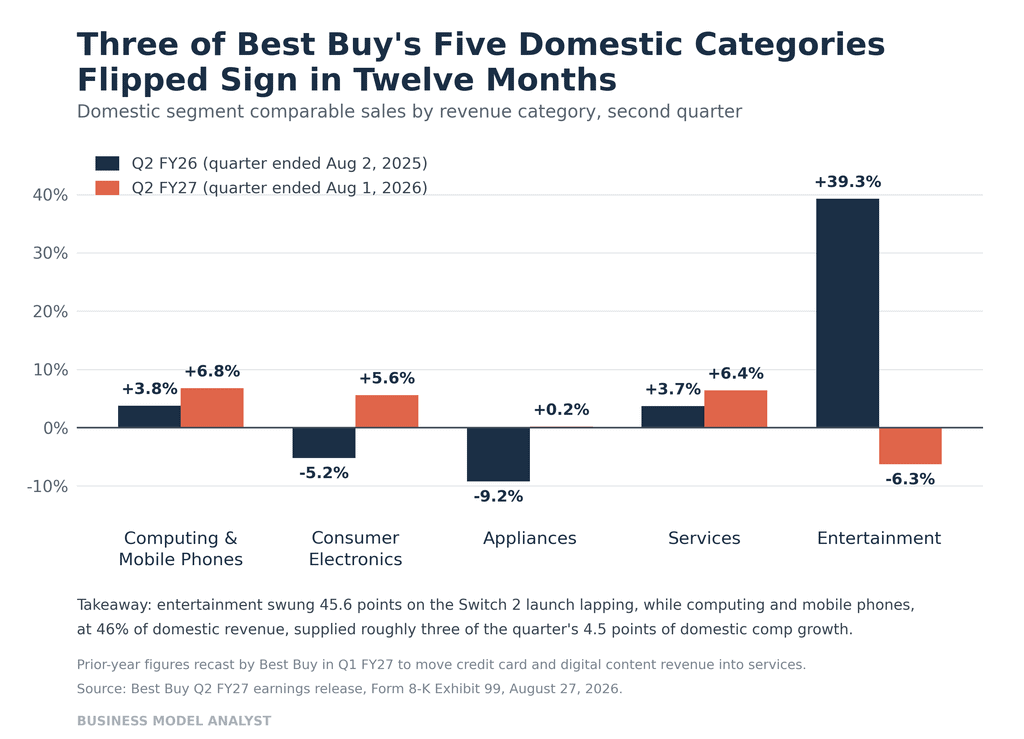
That gaming launch was the Nintendo Switch 2. Best Buy’s domestic Entertainment category comped up 39.3% in Q2 FY26 on the back of it. This quarter the same category comped down 6.3%.
The Plan
Bonfig credited the quarter to deliberate actions and a healthy demand environment for the category. Both halves of that sentence are doing real work, and the second half is carrying more weight than the first.
Best Buy’s own category table shows where the growth came from. Computing and Mobile Phones, at 46% of domestic revenue mix, comped up 6.8%. Applying the disclosed mix weights, that single bucket supplied roughly three of the quarter’s 4.5 points of domestic comp growth, or about two thirds of the total. Consumer Electronics, at 27% of mix, added another 1.5 points on 5.6% growth after declining 5.2% a year earlier.
Company commentary names computing, home theater, and a group of emerging categories including AI glasses and trading cards as the weighted drivers. Trading cards. In a consumer electronics retailer’s earnings release, on the list of categories that moved the comp.
The strategic build sits elsewhere. Marketplace and Best Buy Ads carry structurally different economics from selling a laptop: third-party commission and ad inventory on traffic the stores and site already generate, with no inventory risk and no product margin to defend. Best Buy does not break either out. What it discloses is the aggregate effect, and this quarter the aggregate effect is smaller than the tariff refund.
The Business Model Angle
Three pieces of arithmetic, none of which appeared in the coverage.
One: most of the margin improvement is a refund.
Domestic gross profit rate reached 24.0% against 23.4%, an improvement of 60 basis points. Best Buy attributes it to Marketplace and Ads growth plus approximately $34 million of IEEPA tariff refunds, partially offset by lower product margin rates.
Run the refund against domestic revenue of $9,070 million and it works out to 37.5 basis points. That leaves about 22 basis points for everything else, net of the product margin drag.
| Domestic gross margin, Q2 FY27 | Basis points |
|---|---|
| Total year-over-year improvement | +60 |
| IEEPA tariff refunds ($34M on $9.07B) | +37.5 |
| Marketplace, Ads, less product margin decline | +22.5 |
The refund accounts for 62% of the gross margin expansion. It does not repeat.
Two: the operating leverage went the wrong way.
Domestic adjusted SG&A came in at 19.6% of revenue against 19.3%, meaning Best Buy deleveraged 30 basis points on a 4.5% comp. Retail fixed-cost structures are supposed to work in the other direction. The named drivers are incentive compensation, Marketplace and Ads investment, and advertising.
Domestic adjusted operating income improved 50 basis points, from 4.0% to 4.5%. Strip out the 37.5 basis points of refund and the underlying improvement is roughly 12 basis points, delivered on the strongest comp quarter in years. The new high-margin businesses currently cost more in operating expense than they contribute in gross profit.
Three: the guidance says the quarter does not repeat.
Combine the two halves. Domestic H1 comp was 3.2% on $17,319 million of revenue; International was 1.3% on $1,396 million. Weighted, enterprise H1 comp lands at about 3.06%.
At the midpoint of the raised revenue guidance, $42.55 billion, the second half carries roughly $23.8 billion, or 56% of the year. Solve for the implied second-half comp across the guidance range:
| FY27 comp guidance | Implied H2 comp |
|---|---|
| 1.9% (low) | ~1.0% |
| 2.45% (midpoint) | ~2.0% |
| 3.0% (high) | ~3.0% |
Best Buy’s implied second-half comp range is about 1% to 3%, which is precisely the range it guided for Q3. Q4, the quarter that carries the year, gets the same treatment. A company that had found a durable demand step-change would not model the back half at half the run rate it delivered in the front half.
The control group. Best Buy runs the same brand, the same categories, the same Marketplace-and-Ads playbook and the same specialty-labor model in Canada. International comps fell 1.8% after rising 7.6% a year earlier. International Computing and Mobile Phones grew 2.1% against the U.S. segment’s 6.8%. International adjusted operating income fell to $13 million from $18 million, and the segment margin slipped to 1.8% from 2.4%.
Two segments, one operating model, opposite results. The variable that differs is the size of the U.S. computing replacement wave, not the quality of the execution.
The Risk
Four counterweights, stated as a well-informed skeptic would.
The demand may be real and durable. Consumer Electronics swung from a 5.2% decline to 5.6% growth, and Appliances went from down 9.2% to roughly flat. Neither category has a Microsoft end-of-support date behind it. If households are replacing televisions and dishwashers again, the cycle framing understates what happened.
Guidance conservatism is a management style, not a forecast. Bilunas guided Q2 to about 1% while telling investors May was tracking high single digits. Best Buy has beaten EPS estimates in fifteen of the last sixteen quarters. A company that sandbags by habit will produce an implied H2 comp that looks pessimistic whether or not it is.
Marketplace and Ads may be earlier than the P&L suggests. Both businesses currently show up as SG&A before they show up as margin. Amazon’s advertising line took years to become visible. Judging a two-year-old retail media build on one quarter’s basis-point contribution is a category error, and Bonfig has made it his first stated priority.
The refund is small in absolute terms. Thirty-four million dollars against $9.07 billion of domestic revenue is a rounding error at the revenue line. Its weight in this analysis comes from how thin the underlying margin improvement is, which is itself the point, but a skeptic would note that one line item is carrying a lot of interpretive load.
Two things to watch that would settle it. First, whether inventory growth normalizes: merchandise inventories closed at $6,296 million against $5,816 million, up 8.3% while quarterly revenue grew 3.6%, ahead of a holiday quarter management guides to a slower comp. Some of that is forward buying against memory chip cost inflation and tariffs. Some of it is a bet on demand the guidance does not model. Second, whether Bonfig gives Marketplace and Ads their own disclosure line. Retailers break out the businesses they want investors to value.
Quick Questions
Did Best Buy beat expectations? Yes. Revenue of $9.78 billion beat the $9.59 billion LSEG consensus, and adjusted EPS of $1.47 beat $1.38.
Why did the stock fall in premarket trading? BBY traded at $86.08 premarket, down 1.49%, on a beat-and-raise. One reading: the sell side had already moved above the guide, and the implied second-half deceleration was visible in the release.
What is IEEPA and why did Best Buy get a refund? The Supreme Court struck down tariffs imposed under the International Emergency Economic Powers Act in February 2026. Importers of record have been collecting refunds on duties paid under that authority since. Best Buy booked roughly $34 million of them in gross profit this quarter.
Is Best Buy investing in its stores? Not heavily. Capital expenditure guidance stayed at approximately $750 million while the revenue guide rose $900 million. First-half capex of $344 million ran below depreciation and amortization of $389 million. Against implied full-year adjusted operating income of roughly $1.89 billion, Best Buy is spending about 40 cents of capex per dollar of operating profit. Walmart, on its own FY27 guidance, is spending closer to 90 cents.
Who runs the company now? Barry through October 31. Bonfig from November 1.
The Business Model Analyst Take
Every retailer sells someone else’s product. Not every retailer has its quarterly results scheduled by someone else’s product calendar.
Best Buy’s category table is the clearest picture of the problem any consumer electronics retailer has published this year. Entertainment swung 45.6 points in twelve months because Nintendo shipped a console in June 2025 and did not ship one in June 2026. Consumer Electronics swung 10.8 points. Appliances swung 9.4. Three of five categories flipped sign. The company did not become better or worse at retail in the interval.
The strategic response is correct and the arithmetic is not yet there. Marketplace and Best Buy Ads are attempts to own revenue that does not depend on Microsoft’s support calendar or Nintendo’s release slate. Both currently cost more in SG&A than they deliver in gross margin. That is normal for a build at this stage. It also means the 4.1% comp and the raised guidance describe a cycle, not a conversion.
For founders, the transferable question is simple and uncomfortable. Take your best quarter of the last two years and ask what fraction of it you could have caused. If the answer involves a supplier’s launch date, a regulator’s decision, a platform algorithm change, or a one-time refund, you have a good quarter and an unchanged business. Best Buy earned $34 million from a court ruling and roughly three points of comp from an operating system reaching end of life. It earned about 22 basis points from the thing it actually built.
The number to track is not the comp. It is whether Bonfig, in his first year, breaks out Marketplace and Ads as a reported line. A company only discloses a business separately when it wants that business valued separately. Until then, Best Buy is a specialty retailer whose earnings you forecast by reading vendor roadmaps.