Opening a business bank account is the first unglamorous thing you do after forming an LLC, and it is also one of the few decisions that quietly compounds. The right account keeps your personal and business finances cleanly separated, which is the entire point of forming an LLC in the first place. The wrong one bleeds you a few hundred dollars a year in fees, pays you nothing on idle cash, and makes you drive to a branch to do things a phone should handle.
The good news for 2026: the market has split into two camps. Fintech platforms like Mercury, Bluevine, and Relay charge zero monthly fees, open in minutes, and pay interest on your balance. Traditional banks like Chase still win on cash deposits, branch access, and SBA lending. Most founders should start with a fintech account and add a traditional one only when they have a specific reason to. Below is the verified breakdown, the picks that actually fit different businesses, and the part nobody else explains: how these “free” accounts make money off you.
Definition Box: What is a business bank account? A business bank account is a deposit account held in your company’s legal name (your LLC or corporation) rather than your own. It keeps business income and expenses separate from personal funds, which preserves the liability protection an LLC is supposed to give you. Mixing the two, known as commingling, is the fastest way to let a court “pierce the corporate veil” and put your personal assets on the line. Most accounts in this guide are business checking accounts, often paired with a savings or treasury option for idle cash.
Quick picks
| You are | Start with |
|---|---|
| A tech startup or SaaS founder | Mercury |
| Sitting on operating cash you want to earn yield | Bluevine |
| Running on the Profit First method | Relay |
| A solopreneur or simple online business | Novo |
| Venture-backed with a spending team | Brex |
| Handling regular cash deposits | Chase Business Complete |
The 2026 comparison
All figures verified against provider disclosures as of late June 2026. APYs are variable and change with rates, so treat them as a snapshot, not a promise.
| Account | Monthly fee | Yield on cash | FDIC coverage | Cash deposits | Best for |
|---|---|---|---|---|---|
| Mercury | $0 | Up to ~3.61% via Treasury (needs ~$250K, investment product) | Up to $5M (sweep) | No | Startups and digital-first businesses |
| Bluevine | $0 Standard ($30 / $95 upper tiers, waivable) | 1.3% Standard up to $250K; up to 3.0% on Premier | Up to $3M (sweep) | Limited, with fees | Earning yield on operating cash |
| Relay | $0 Starter (Pro tier paid) | Lower-tier interest via savings | Pass-through via Thread Bank | Yes, at partner retailers | Profit First and multi-account budgeting |
| Novo | $0 | ~1.10% on select tiers | Standard, via partner bank | Limited, at retail partners | Solopreneurs and online sellers |
| Brex | $0 business account | Up to ~3.74% on invested cash | Up to $6M (sweep) | No | VC-backed teams managing spend |
| Chase Business Complete | $15 (waivable) | Effectively 0% | $250K standard | Yes, full branch network | Cash-heavy and traditional needs |
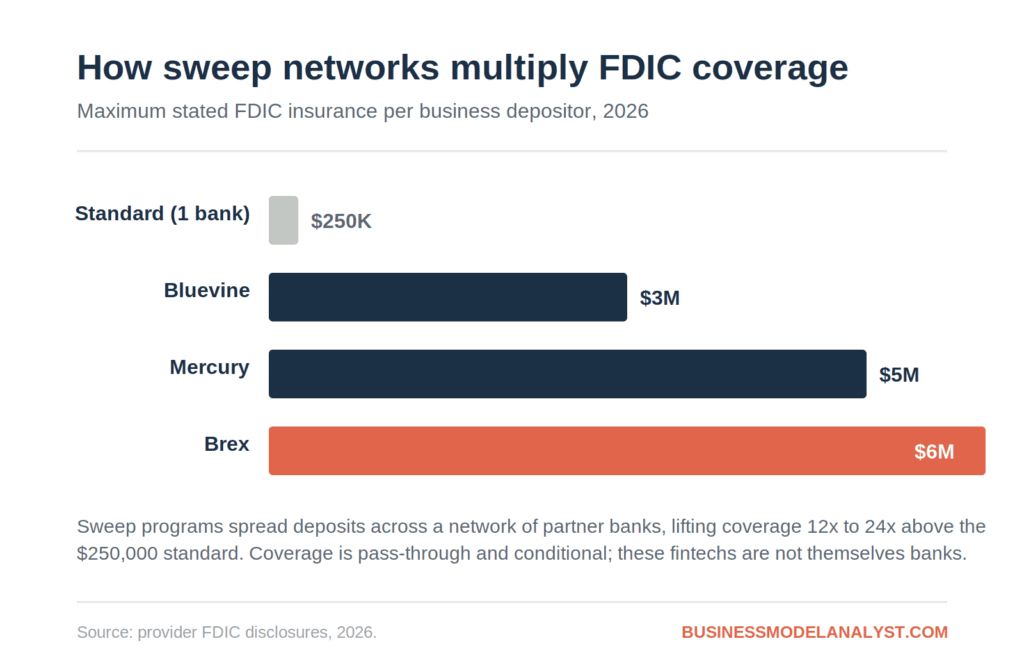
One structural point worth seeing before the individual reviews. The fintech accounts do not just match the standard $250,000 of FDIC protection, they multiply it by spreading your deposits across a network of partner banks.
1. Mercury, best overall for startups
Mercury has become the default operating account for tech startups, and the reasons are boring in the best way. There is no monthly fee, no minimum balance, and no overdraft fee. Domestic and US-dollar international wires are free, which is genuinely rare when most banks charge $20 to $35 per wire. You can open it online in about ten minutes with your EIN and formation documents.
For idle cash, Mercury Treasury yields up to roughly 3.61% as of late June 2026, but read the fine print: it requires about $250,000 across your Mercury accounts, and it is an investment advisory product, not an FDIC-insured deposit. Treasury balances are covered up to $500,000 by SIPC instead, and the value can move. On the deposit side, Mercury offers up to $5 million in FDIC coverage through partner banks Choice Financial Group and Column N.A. and their sweep networks.
The catch is the fintech model itself. Mercury does not take cash deposits at all, so a retail or cash-heavy business cannot use it as a primary account. It also relies on partner banks, and there is a documented pattern of account closures with limited explanation that shows up across review sites. Mercury applied for its own national bank charter in December 2025, which could eventually reduce that dependency, but as of now it is a fintech, not a bank.
Best for: SaaS companies, agencies, e-commerce sellers, and any founder who wants modern tooling and free wires without cash needs.
2. Bluevine, best for yield on operating cash
Bluevine is the pick when you want your operating balance working instead of sitting at 0.01%. The Standard plan is free and pays 1.3% APY on balances up to $250,000, provided you meet one of two monthly conditions: spend at least $500 on the Bluevine debit or credit card, or take in at least $2,500 in customer payments. Miss both in a given month and you simply earn nothing that month, with no other penalty.
If you carry more cash, the upper tiers get aggressive. Bluevine Plus is $30 per month (waivable) and pays 1.75%. Bluevine Premier is $95 per month and pays 3.0% APY on every dollar up to $3 million, with the fee waived if you keep a $100,000 average daily balance and spend $5,000 a month on the card. Across all tiers you get unlimited transactions, up to $3 million in FDIC coverage through Coastal Community Bank’s sweep network, and access to a line of credit up to $250,000 through a lending partner.
The weak spots are international and cash. Bluevine is US-only, charges for wires on the Standard plan, and offers no fee-free cash deposits.
Best for: Domestic service firms, agencies, and e-commerce operators with steady revenue who want yield without shuffling money into a separate savings product.
3. Relay, best for the Profit First method
Relay is built around a simple idea: most small businesses do not need one account, they need their money sorted into buckets. The free Starter plan lets you open up to 20 individual checking accounts and issue up to 50 virtual debit cards, which maps perfectly onto the Profit First system of separating operating funds, taxes, payroll, and profit. There is no monthly fee and no minimum balance on the base plan, with banking services provided by Thread Bank.
You also get granular permissions, so a bookkeeper or business partner can have exactly the access they should and nothing more. It integrates with QuickBooks and Xero for clean reconciliation. A paid Relay Pro tier adds faster same-day ACH and auto-transfer rules for businesses that want more automation.
The tradeoff is that Relay is an organizational tool first and a yield tool second. Interest on idle cash is modest compared with Bluevine or a Mercury Treasury setup, and it is built primarily for US operations, so international payments are not its strength.
Best for: Founders who run on Profit First or simply want disciplined, purpose-separated cash management baked into the banking layer.
4. Novo, best for solopreneurs and simple online businesses
Novo is the no-friction option for freelancers, consultants, and small online sellers. It has no monthly fee and no minimum balance, reimburses third-party ATM fees, and integrates cleanly with Stripe, Shopify, and QuickBooks, which makes it a natural fit if you sell through those rails. Select tiers now pay around 1.10% APY, and Novo added a built-in BOI Reporting Assistant to help with beneficial ownership filing requirements.
It is deliberately simple, which is the point and also the limitation. Novo lacks the advanced global features of a platform like Mercury or Airwallex, accepts wires only in US dollars, and routes international payments through a third-party integration rather than handling them natively. Cash deposit options are limited and run through retail partners with fees.
Best for: Solopreneurs, freelancers, and early online businesses that want a clean free account and tight e-commerce integrations.
5. Brex, best for venture-backed teams
Brex is less a bank account and more a finance platform, combining business banking, corporate cards, expense management, and bill pay in one system. For a startup with a team making purchases, that consolidation is the entire pitch: card limits per employee, automated expense policies, real-time spend visibility, and receipt matching that saves your future controller real hours. It carries up to $6 million in FDIC coverage, the highest stated ceiling on this list, and pays up to roughly 3.74% on invested cash through its treasury product, with 0% on uninvested balances.
The reason it is not the default for every LLC is eligibility. Brex is built for incorporated, funded companies, and generally expects venture backing, meaningful cash reserves, or established business revenue. Its compliance requirements tightened further in 2026, particularly for founders without a US Social Security number. A brand-new bootstrapped LLC will often be a poor fit.
Best for: Venture-backed startups and growing companies that need spend management and credit alongside banking, not just a place to park deposits.
6. Chase Business Complete Banking, best for cash and tradition
When you genuinely need a traditional bank, Chase is the benchmark. It has one of the largest branch and ATM networks in the country, takes cash deposits, and gives you a real relationship to lean on for business credit cards, lines of credit, and SBA loans down the road. Chase has also integrated FedNow and RTP, so the money moves at modern speed even if the branch experience does not feel modern.
The account carries a $15 monthly fee, which is waivable in 2026 by maintaining a $2,000 minimum daily balance, taking in $2,000 a month through Chase Payment Solutions, or spending $2,000 a month on a linked Chase business card. New accounts have recently carried a welcome bonus of up to $500 tied to qualifying activity, though these offers are time-sensitive and expire, so confirm the current terms before you count on one.
The honest downside for globally minded founders: Chase’s foreign exchange rates run roughly 2% to 3% higher than fintech platforms, which adds up fast if you pay overseas vendors.
Best for: Businesses that deposit cash regularly, want in-person support, or plan to tap SBA and traditional lending.
Why are these accounts free? The business model behind fintech banking
Here is the part the affiliate listicles skip. “Free” banking is not charity, and understanding how these platforms actually make money tells you more about which one to trust than any feature table. There are five engines, and most of these companies run several at once.
The first and biggest is interchange. Every time you swipe a business debit or credit card, the merchant pays an interchange fee, and a slice flows back to the card issuer. Because most fintechs partner with small banks that sit under the regulatory threshold for capped interchange, they earn a richer cut than a megabank would. This is precisely why Bluevine, Mercury, and others nudge you to put spend on their card, and why card-spend requirements show up in their interest and fee-waiver terms. Your swipes are the product.
The second is the deposit spread, also called net interest margin. The platform or its partner bank holds your balance and earns yield on it, often in Treasury bills or at the Fed, while paying you little or nothing on a basic account. The gap is revenue. An account paying you 0% on cash is not free, it is the most profitable kind.
The third is treasury and advisory fees. When Mercury or Brex moves your idle cash into money market funds, there is usually a management fee attached (Mercury’s runs around 0.5% on its Treasury product). The fourth is lending: lines of credit, venture debt, card interest, and in Bluevine’s origins, invoice factoring. These carry real margin. The fifth is software and subscriptions: Mercury’s paid plan from $35 a month, Relay Pro, Bluevine’s Plus and Premier tiers, plus perks marketplaces and partner referral deals that pay the platform.
The practical takeaway: a platform that earns from interchange and lending can afford to keep your checking genuinely free, while one leaning hardest on the deposit spread has a quiet incentive to keep your yield low. Match the model to your behavior. If you spend heavily on cards, the interchange-funded accounts will treat you well. If you sit on cash, prioritize the ones that actually share the yield.
How to choose
Run your decision through four filters, in order.
| Filter | What to ask |
|---|---|
| Cash | Do you deposit physical cash? If yes, you need Chase or another traditional bank, full stop. |
| Fees | Are there monthly or minimum-balance fees you cannot easily waive? In 2026 you should not pay for basic checking. |
| Yield | How much idle cash do you carry, and is the account actually paying you on it? |
| Workflow | Does it integrate with your stack (Stripe, Shopify, QuickBooks, Gusto) and your method (Profit First, spend management)? |
For most LLCs the answer is a free fintech account as the daily driver, plus a traditional account opened later only if cash deposits or SBA lending enter the picture.
How to open a business bank account for your LLC
Fintech accounts approve in minutes; traditional banks can take days and sometimes a branch visit. Either way, have these ready:
| Document | Why |
|---|---|
| EIN | Your IRS-issued business tax ID |
| Articles of Organization | Proof your LLC is legally registered |
| Operating Agreement | Shows who has authority over the account |
| Government-issued ID | Required for any owner with 25% or more |
Once these are verified, most fintech accounts are usable the same day.
Frequently asked questions
Do I legally need a separate bank account for my LLC? Functionally, yes. While a few states do not strictly mandate it, mixing personal and business funds can pierce the corporate veil and erase the liability protection that makes an LLC worth forming. Treat a dedicated account as non-negotiable.
Are fintech business accounts actually safe? Your deposits are FDIC-insured through the platform’s partner banks, often well above the $250,000 standard via sweep networks. The nuance is that the fintech itself is not a bank, the coverage is pass-through and conditional, and treasury or investment products are insured differently (by SIPC) or not at all. Read which product you are actually holding.
Can I open a business account with just an EIN? You generally need the EIN plus your formation documents and a personal ID. Fintech platforms allow fully online applications; some traditional banks may require a branch visit for more complex LLC structures.
What is the best business bank account for a startup with no revenue yet? Mercury is the common default because it approves new LLCs quickly, charges nothing, and offers founder-focused tools. Brex, by contrast, generally wants venture backing or revenue, so it is often a poor fit for a brand-new bootstrapped company.
Which account pays the highest interest? It depends on your balance and tier. Bluevine Premier pays 3.0% on every dollar up to $3 million if you clear its requirements, while Mercury and Brex offer higher treasury yields but as investment products with larger minimums. For a typical small balance, a Bluevine or Novo account is the simpler way to earn something.
The Business Model Analyst Take
The 2026 reality is that for roughly nine out of ten LLCs, the old default of paying a megabank $15 a month for worse software no longer makes sense. Start with a free fintech account that matches how you operate: Mercury if you are a digital-first startup, Bluevine if you are sitting on cash, Relay if you budget in buckets, Novo if you are a solopreneur. Add a Chase account only when a concrete need appears, namely cash deposits or SBA lending.
But choose with your eyes open. These platforms are not banks, they are software companies sitting on top of banks, and they make money from your swipes, your idle balance, and your subscriptions. That is not a reason to avoid them, it is a reason to match the business model to your own behavior. If you spend on cards, ride the interchange-funded accounts and enjoy the genuinely free checking. If you hold cash, demand real yield and do not let a 0% account masquerade as a free one. The best account is not the one with the longest feature list, it is the one whose economics happen to align with yours.
Sources and verification: figures confirmed against provider disclosures and official product pages (Mercury, Bluevine, Relay, Novo, Brex, Chase) as of late June 2026. APYs and promotional bonuses are variable and time-sensitive; verify current terms with the provider before opening an account. This article is for informational purposes only and is not financial, legal, or tax advice.