
One fragrance, Japanese Cherry Blossom, has pulled in more than $1.5 billion for Bath & Body Works over 20 years. The company’s problem is that it has not found the next one, and sales are sliding. Its answer is not just a new scent. It is a factory cluster in the middle of Ohio that most shoppers have never heard of.
The $1.5 billion candle in the room
Japanese Cherry Blossom debuted in 2006 and never left the best-seller list. The scent, a perfumer’s blend of Asian pear, white jasmine and basmati rice, now moves through candles, lotions, body mists and air fresheners, and Bath & Body Works marked its 20th anniversary this spring with fresh packaging and an ad push.
That single fragrance is both the company’s crown jewel and its warning sign. When one product carries this much of a brand for two decades, the pressure to replicate it never stops. Bath & Body Works has a chief “nose,” Mary Testa-Gough, whose job is literally to find the next one, working with master perfumers at fragrance houses like DSM-Firmenich who compete to land their scents on the company’s shelves.
The number that forced a rethink
Sales fell to $7.3 billion last year from a pandemic-era peak of $7.8 billion. The pressure came from two directions at once: nimble competitors marketing scents on TikTok, and a wave of consumers growing suspicious of synthetic chemicals in fragrance.
A roughly $500 million slide is not a collapse, but for a mall-anchored specialty retailer it is enough to trigger a full strategic reset. That reset arrived with a new chief executive.
What Daniel Heaf’s turnaround actually does
Daniel Heaf, who took over as CEO in May 2025, unveiled a plan he calls the Consumer First Formula alongside a weak third-quarter report in November. Investors did not love the diagnosis at first: the stock fell about 25% to $15.82 on the day. Heaf’s blunt read was that the company had chased adjacent categories and neglected its core.
The plan reorganizes the business around a few clear moves:
| Lever | What it means | Status |
|---|---|---|
| Sell on Amazon | Meet shoppers “in their path” instead of relying on stores and its own weak site | Live since February 2026 |
| Enter Ulta Beauty | Home fragrance, hand soap, three-wick candles and mists in 600-plus Ulta stores | Rolling out from July 12, 2026 |
| Elevate “iconic” scents | Market hero fragrances as stand-alone brands | In progress |
| Exit weak categories | Wind down hair and men’s grooming to refocus on core | In progress |
| New launches | Watermelon Whirl and Tangerine Twirl in a line promoted by Hilary Duff | This month |
The Amazon move is sharper than it looks. Heaf noted the brand was already seeing $60 million to $80 million in gray-market sales on the platform before it ever launched there, revenue it was neither controlling nor capturing. Q1 2026 results (net sales of $1.38 billion, down 3% year over year) came in ahead of guidance, an early sign the plan is at least not making things worse.
For context on why a marketplace like Amazon is so hard for a stores-first brand to ignore, the platform’s flywheel rewards being where consumers already search.
Beauty Park: the moat nobody markets
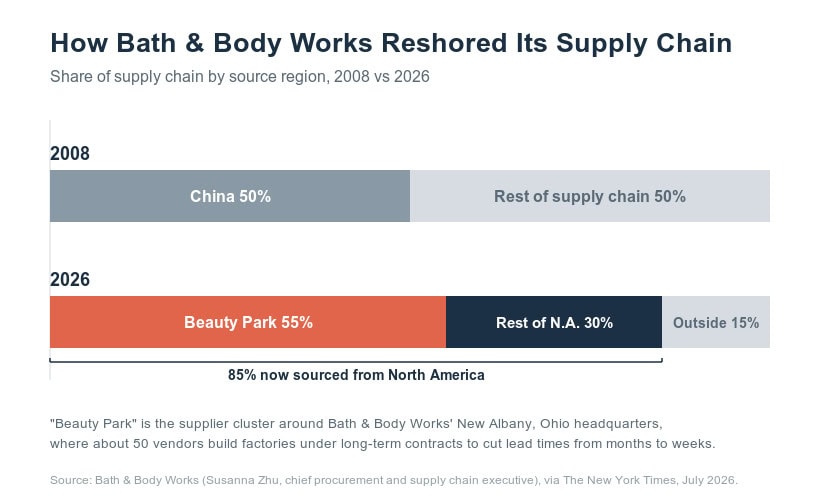
Here is the part of the story that matters most to operators, and that Bath & Body Works barely advertises. Since 2008, the company has cut its roster of strategic suppliers to about 50 from hundreds, and it has clustered many of them physically around its New Albany, Ohio headquarters. The industry now calls that cluster Beauty Park.
The logic is speed. Axium Packaging builds the plastic bottles. Kdc/one, a contract manufacturer, mixes fragrances into the foaming soaps, lotions and gels and fills those bottles at a plant about half a mile away. Alene Candles, which pioneered the three-wick candle with Bath & Body Works, runs a burn lab nearby where technicians measure soot and flame height on every batch. When a scent goes viral, the company can restock in weeks instead of months.
The scale of the shift is striking. In 2008, about half the supply chain ran through China. Today, 85% of it comes from North America, and 55% of the total sits inside Beauty Park.
Why clustering beats chasing the cheapest factory
The obvious question: why not just source wherever it is cheapest? Because proximity buys more than speed. It buys co-invention.
Alan Malter, an associate professor at the University of Illinois Chicago who studies industry clusters, frames the difference plainly. A cheap, distant contract manufacturer takes instructions and makes what it is told. A close, long-term partner helps invent the next product with you. Bath & Body Works executives describe their core suppliers as an extension of the company itself, and that near-familial relationship is exactly what lets them turn a focus-group hunch into a shelf-ready product before a TikTok trend cools off.
The idea traces back to retail mogul Les Wexner, the founder of L Brands (the former parent of Bath & Body Works, Victoria’s Secret and Abercrombie & Fitch). Wexner had watched Victoria’s Secret suppliers in an Indian apparel hub turn around orders fast because they were all clustered together. He pushed to recreate that density in Ohio, on a former pig farm 17 miles from the nearest railway. His own team thought he was crazy. During the pandemic, that same cluster let the company pivot to hand sanitizer overnight and post its best year on record.
How a billion-dollar scent is actually born
The front end of the process is as high-tech as the back end is industrial. To build the Milk Bar Birthday Cake collection, chemists captured molecules from the steam of a freshly baked cake and recreated the aroma in a lab. Japanese Cherry Blossom itself was pure invention, since real cherry blossoms barely smell. Perfumer Harry Fremont, the man behind Calvin Klein’s CK One, layered in sandalwood, musk and rice molecules, then added top notes of apple and pear after focus groups found an earlier version too sophisticated. The brief from Bath & Body Works at the time was audacious: make our version of Shalimar, the legendary 1925 Guerlain perfume.
The competitive squeeze
None of this guarantees a hit. Nobody, inside the company or out, can reliably predict why one scent becomes a 20-year classic while another lands in the clearance bin. Meanwhile the threats are concrete: viral fragrance brands built natively for TikTok, and a “clean beauty” movement pushing shoppers to scrutinize ingredient lists. A fast supply chain lets you scale a winner quickly. It does not tell you which product will win.
What a skeptic would push back on
The reshoring story is genuinely impressive, but it is worth stress-testing. Three cautions:
First, speed to restock solves a supply problem, not a demand problem. If the company cannot generate the next iconic scent, the fastest supply chain in retail just refills products nobody is asking for.
Second, Beauty Park is a fixed-cost bet. A dense domestic cluster is a formidable asset when volumes are high and rising, and a liability when they are falling, which is the exact direction sales moved last year. Concentration cuts both ways.
Third, the turnaround leans heavily on distribution (Amazon, Ulta) to buy time. Those channels expand reach, but they also hand shelf space and consumer relationships to partners, and they can dilute the store experience that made the brand distinctive. More places to buy is not the same as more reasons to buy.
What operators can take from this
The transferable lesson is not “build a factory town.” Most businesses cannot. It is that Bath & Body Works treated its supply chain as a source of competitive advantage rather than a cost center to be squeezed. By trading the lowest possible unit cost for speed and co-invention, it built something rivals cannot copy with a purchase order.
You see the same trade in other places: a private-label operation like Trader Joe’s wins on a tight, deeply integrated supplier network rather than the widest, cheapest one. The strategic question for any product company is which of your “costs” are actually latent moats, and whether you are optimizing them for the wrong variable.
The Business Model Analyst Take
Bath & Body Works has quietly built one of the most defensible operational moats in specialty retail, and it is spending 2026 finding out whether that moat can offset a demand problem it has not yet solved. The Beauty Park cluster is the answer to a question most retailers never think to ask: what if proximity, not price, is the real supply-chain advantage? It shrinks lead times, deepens supplier co-invention and de-risks the company from overseas shocks, and it is the reason the pandemic became the company’s best year rather than its worst.
But a moat protects a castle; it does not fill it. The Heaf turnaround (Amazon, Ulta, iconic fragrances as stand-alone brands, a ruthless cut of weak categories) is a bet that better distribution and sharper focus can reignite demand while the supply engine stands ready to scale whatever hits. The elegant part is the sequencing: fix where and how people can buy first, because the factory cluster already guarantees you can deliver the moment they do. The risk is that fragrance is a hit business, and no supply chain, however fast, can manufacture the next Japanese Cherry Blossom on command. Watch the new launches, not the logistics. The logistics are already world-class. The question is whether the nose can find another billion-dollar bottle.