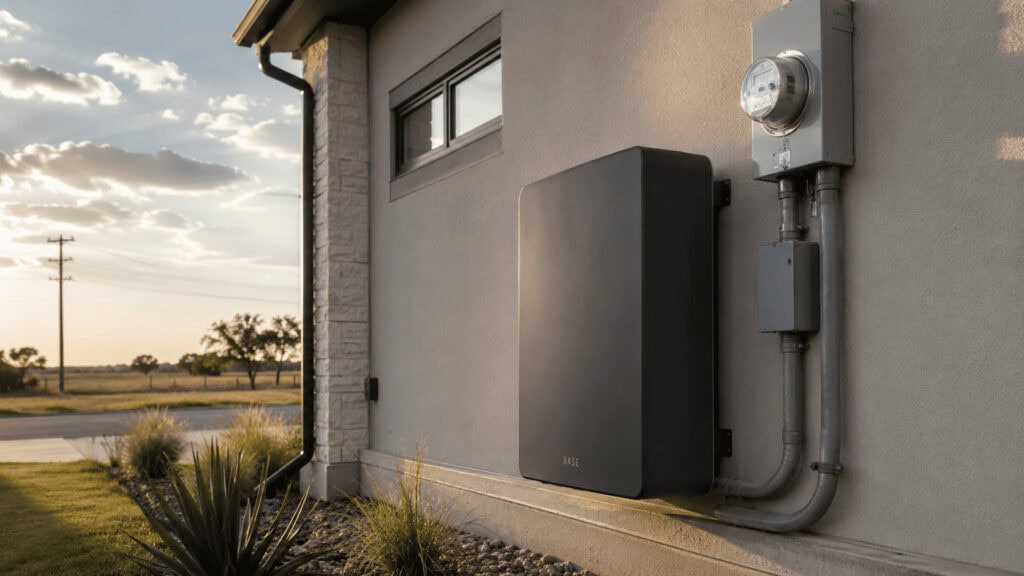

The Michael Dell heir’s home-battery startup raised another $1 billion. The trick is that it owns every unit it installs, turning 23,000 backyards into a power plant it controls.
Base Power is now worth $13 billion, and it got there by giving homeowners a battery it refuses to sell them. The Austin startup run by Zach Dell, son of Michael Dell, closed a fresh $1 billion round that more than tripled its valuation from $4 billion last October. It owns the hardware, keeps it on its own balance sheet, and books revenue three separate ways from a single box sitting in your yard. That structure, not the Dell name, is the story.
Base Power raised $1 billion at a $13 billion valuation, bringing its total funding past $2.5 billion. The company has installed more than 23,000 batteries across Texas and the Chicago area and runs roughly 100 installations a day, a pace it plans to double by year-end. Its edge is a business model closer to a cell-tower operator than a consumer-electronics brand: Base never sells the battery, so every unit it deploys becomes a revenue-producing asset it keeps.
Steps away from an old printing press in the former Austin American-Statesman building, robots and workers assemble batteries bound for residential backyards. Three years ago the company installed its first unit at a friend’s home in Dallas and had to scour Craigslist for an electrician, who took $500 in cash. The newest battery goes in under an hour on a pre-wired modular design. The ambition scaled with the process: Dell wants to build America’s next major power company, one AC-compressor-sized box at a time.
What Happened
Base Power confirmed a $1 billion funding round on August 3, 2026, lifting its valuation to $13 billion. Ribbit Capital, Addition, Valor Equity Partners, and JPMorganChase’s Strategic Investment Group led the round. Michael Dell is not a backer. His son Zach co-founded and runs the company.
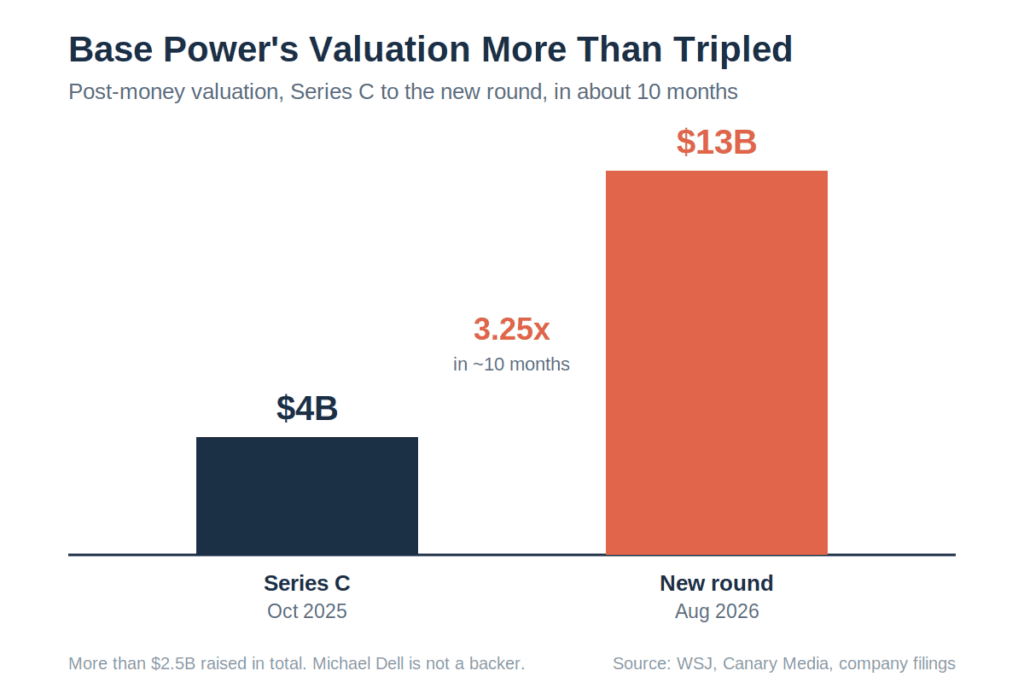
The raise stacks on a fast climb. Base closed a $1 billion Series C at a $4 billion valuation in October 2025, six months after a $200 million Series B. Founded in 2023, it became a unicorn in two years. Total capital raised now sits above $2.5 billion.
The money funds one thing: more batteries in more yards. Base has roughly 550 megawatt-hours installed, equal to a large utility-scale storage project, except spread across tens of thousands of homes instead of one fenced-off site. It employs about 500 people and is building a factory in Austin to make its own hardware.
The Backstory
Zach Dell co-founded Base with Justin Lopas, the former head of manufacturing at Anduril Industries. That pairing matters. Anduril built a reputation for vertically integrated, fast-iterating hardware production, and Lopas brought that discipline to a product that has to be cheap, reliable, and installable at scale. Antonio Gracias of Valor Equity Partners, an early backer of Tesla and SpaceX, joined the cap table and praised the team and the manufacturing approach.
The hardware evolved across three generations. Early units offered about 25 kilowatt-hours of storage. The modules rolling out now deliver 39.2 kilowatt-hours, enough for roughly 36 hours of backup for most homes. Base designs and builds the latest generation in-house at its Austin factory, partly to control cost and partly to comply with federal rules that limit tax credits for batteries carrying too much Chinese content.
The Plan
Dell wants Base in more states and eventually overseas. It entered the Chicago area earlier this year and treats Texas as the beachhead, not the ceiling. The factory is meant to push production high enough to keep the 100-installs-a-day pace climbing.
The expansion rides a real wave. In the first quarter, the US installed 3.3 gigawatts of battery storage, or 8.4 gigawatt-hours of energy capacity, according to the American Clean Power Association and Wood Mackenzie. The home-battery slice hit 1.3 gigawatt-hours, an industry record. Rivals are crowding in: NRG Energy partnered with Sunrun on bundled solar-and-storage subscriptions, and Tesla keeps expanding its residential footprint with the Powerwall.
The Business Model Angle
Here is where Base separates from the pack. It runs two models, and both hinge on ownership.
In deregulated markets like Texas, Base acts as your retail electricity provider. It installs the battery at no hardware cost to you, sells you power at below-average rates, and keeps the box. When the grid runs normally, Base aggregates thousands of these batteries and discharges them into the system during peak-demand windows when wholesale prices spike, then recharges when power is cheap. When an outage hits, the same battery gives you backup. One owned asset, three income streams: retail margin on your bill, arbitrage and grid-services revenue from the aggregated fleet, and the customer-retention value of being the company that keeps your lights on.
The second model targets regulated and municipal utilities and electric co-ops. In West Texas, El Paso Electric asked homeowners on its most crowded feeders to host Base batteries. The utility owns the battery, installs it on the grid side of the meter, and pays the homeowner a $250 incentive plus backup power. A separate meter tracks charging and discharging, so the customer’s bill stays untouched. El Paso Electric CEO Kelly Tomblin framed the economics with a hotel analogy: a utility builds for the handful of scorching days when demand leaps from 1,000 megawatts to more than 2,500, then charges everyone year-round to pay for capacity used a few days annually. Batteries let her avoid building for that peak.
Both models point to the same insight. Base is not a gadget company. It is a distributed power-plant operator that happens to use your backyard as the site. That is the cell-tower playbook applied to electrons: own the physical asset, spread it across thousands of locations, and monetize the aggregate. Tesla sells you a Powerwall and books a one-time hardware margin. Sunrun leases you solar-plus-storage as a decades-long subscription built around generation. Base is storage-first, keeps the asset, and doubles as your power retailer.
The Risk
The model that makes Base interesting also makes it fragile. Owning every battery means Base fronts the cost of every battery. Growth does not free up cash, it consumes more of it, which is why the company keeps raising billion-dollar rounds. Sunrun ran the same asset-owned playbook in solar and leaned hard on non-recourse project finance to fund it. Base will likely need the same debt machinery, and that only works if the batteries produce the cash flows the model assumes.
Then there is price. Reported projections put Base’s 2026 revenue near $70 million. A $13 billion valuation on that figure is north of 180 times revenue. That is a bet on installed capacity compounding into a dispatchable fleet worth utility-scale money, not on this year’s income statement. BMA has flagged the same pattern at Tesla, where the valuation decoupled from current operations and gets priced on a future that has to show up. If installs stall, if grid-services revenue underdelivers, or if the in-house manufacturing ramp slips, the multiple re-rates fast.
Competition and regulation add pressure. Tesla and the NRG-Sunrun pairing want the same homeowners. Utilities can build their own storage. And Base’s richest model, the retail-provider version, depends on deregulated markets like ERCOT. Expansion into regulated territory pushes it toward the thinner utility-partnership model, where the utility owns the battery and Base collects a smaller slice.
Quick Questions
Does Base Power sell you the battery? No. Base owns the hardware and keeps it on its balance sheet. You get lower electricity rates and backup power, not a box you own.
So how does Base make money? Three ways from each owned battery: margin as your retail power provider, revenue from aggregating and dispatching the fleet during peak demand, and fees from utilities that use the batteries to relieve grid congestion.
What is Base worth now? $13 billion, up from $4 billion in October 2025. It has raised more than $2.5 billion in total.
Is Michael Dell involved? No. Michael Dell is not a backer. His son, Zach Dell, is co-founder and CEO.
The Business Model Analyst Take
Base Power sells convenience and buys an asset. The homeowner gets a cheaper bill, a backup battery, and no upfront hardware cost. Base gets a box it owns, controls, and dispatches, one node in a fleet it is assembling into a virtual power plant. The $13 billion valuation is not paying for the batteries. It is paying for the option that 23,000 units becomes 2.3 million, and that a company owning millions of distributed storage assets ends up looking like a utility with none of the legacy infrastructure.
That option is real, and the demand tailwind behind it is real. Antonio Gracias put the macro case bluntly: US GDP growth will run into the ceiling of available energy. Distributed storage is one way to raise that ceiling without building a peaker plant that sits idle 350 days a year.
The catch is that fleet-operator businesses are capital furnaces early and cash machines only later, if the unit economics hold. Base is still deep in the furnace phase, financing its buildout with equity at a multiple that assumes near-flawless execution. The batteries are cheap to install. The model is expensive to grow. Whether Base becomes America’s next big power company or a very well-funded cautionary tale comes down to one number nobody can see yet: what a mature, fully deployed Base battery earns over its life, minus what it cost to put in the ground. Everything in that $13 billion is a wager on that spread.
Source: The Wall Street Journal, “Zach Dell Is Raising Money to Put a Battery in Your Backyard” (Aug. 3, 2026), with additional data from Canary Media, Sacra, and company disclosures.