
The art market didn’t recover by accident. It got choreographed, deal by deal, before a single gavel dropped.
Auction houses pulled off a $2.5 billion spring season, nearly double last year’s $1.3 billion, by de-risking the whole game before sales even started. More than half of evening-sale lots carried third-party guarantees, meaning roughly $1.4 billion in art was effectively presold to backers who agreed to bid in advance.
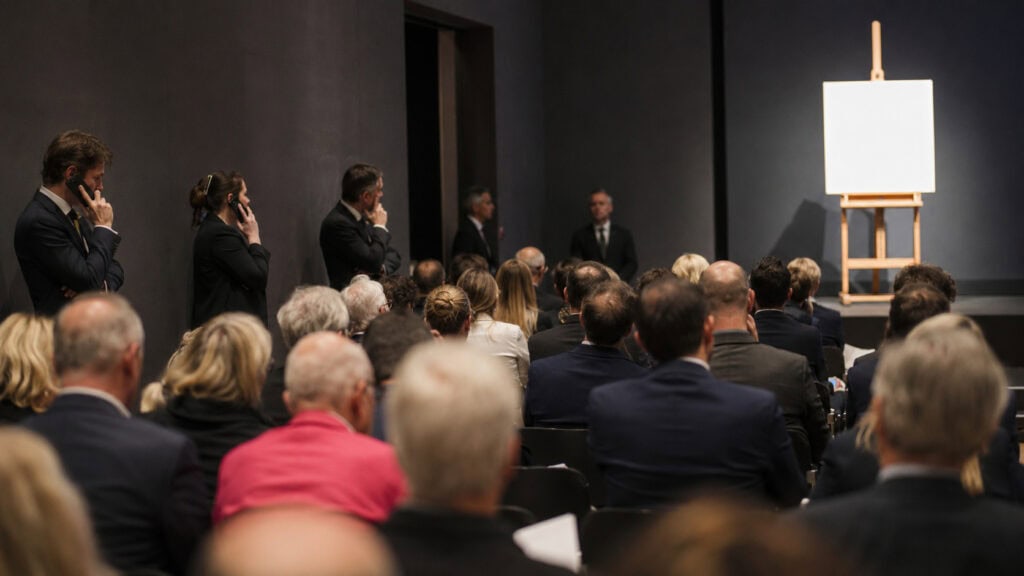
Picture this: a Christie’s executive lifts a phone, covers their mouth, and whispers into the receiver. Seven minutes later, a Jackson Pollock splash-and-drip painting has climbed to a record $181.2 million. It looks like spontaneous market euphoria. It mostly wasn’t.
What Happened
Christie’s, Sotheby’s, and Phillips sold a combined $2.5 billion in art this spring, including buyers’ fees, up from $1.3 billion in the equivalent sales last May. Several works blew past their high estimates, and a handful set new auction records.
The headline numbers were real. But the mechanics behind them were deliberate. Christie’s CEO Bonnie Brennan described the market as “healthy but disciplined,” noting renewed confidence at the top end. The season was less a rebound and more a carefully managed reset of what buyers and sellers were told to expect.
The Backstory
For four straight years, auction sales had been uneven, and executives blamed global conflict, economic instability, and a thin supply of top-tier work. Last May, Sotheby’s got publicly burned when a $70 million Giacometti bust failed to sell.
Then things shifted. A Klimt portrait fetched $236.4 million in November, and confidence started returning. This season’s job was to protect that momentum by avoiding anything that might flop, from untested young artists to big names carrying overly ambitious price tags. More than $1 billion of the haul came from the estates of major collectors, including former Condé Nast leader S.I. Newhouse Jr. and philanthropist Agnes Gund.
The Play
Here’s the engine. To win consignments, auction houses promised sellers a guaranteed minimum price. Then they offloaded that risk to third parties: backers who either win the work at an effective discount, or collect a financing fee if they’re outbid. Either way, the house locks in a result.
Five years ago, collectors found these guarantees off-putting because they didn’t want to bid against insiders. Now it’s the norm. “When you don’t see that, it makes people wonder, why would they bid?” said Caroline Sayan, CEO of advisory firm Cadell North America.
The spectacle helped too. Sotheby’s ran a promo video of Nicole Kidman dancing around a bronze Brancusi head. That same Brancusi sculpture, “Danaïde,” sold for a record $107.6 million, though a former Sotheby’s executive noted the guaranteed buyer “could have paid a number very far below $107 million” once the financing fee is counted.
The Business Model Angle
This is a textbook case of de-risking a marketplace by pre-committing demand, and there’s a real lesson for founders here.
Auction houses are two-sided platforms. Their hardest problem isn’t pricing, it’s convincing sellers to consign scarce inventory without knowing if buyers will show up. Third-party guarantees solve that by manufacturing a price floor before the “live” event ever happens. The auction becomes theater layered on top of a deal that’s already mostly done.
Smart operators do versions of this constantly: pre-sales before a product launch, signed letters of intent before a fundraise, anchor tenants before a mall opens. You reduce uncertainty by selling the risky part to someone willing to own it. The auction houses just monetized that mechanic with unusual elegance. If you run a marketplace, the takeaway is blunt: liquidity you can engineer beats liquidity you have to hope for. Founders thinking through two-sided dynamics can find more on platform strategy in the Business Model Analyst blog.
The Risk
Now the honest counterpoint. Engineered confidence is still engineered, and the underlying market looks shakier than the $2.5 billion suggests.
Art remains a brutal investment. A Warhol Elvis silk-screen that sold for $37 million in 2018 went for just $27.1 million last week, down nearly 49 percent after inflation. A Pollock that fetched $15.3 million in 2024 dropped 46 percent to $9.2 million. The winners are loud, but the losers are real.
There’s also a demand-base problem. Russian and Chinese buyers have thinned out over the past decade, the Middle Eastern collector boom fizzled as Gulf clients turned cautious, and core auction buyers remain, per former Sotheby’s executive Mari-Claudia Jiménez, mostly white men over 60. When one-third of works priced between $10 million and $40 million underperformed their estimates, the message is clear: this comeback depended on rare estate material and clever financial scaffolding. Strip either away, and next season is a much harder sell.
Quick Questions
What is a third-party guarantee in art auctions?
It’s a deal where an outside backer agrees to bid a minimum amount on a work before the auction. If nobody bids higher, they own it. If someone outbids them, they collect a financing fee. Either way, the auction house locks in a sale.
How much art actually sold this spring?
Christie’s, Sotheby’s, and Phillips sold a combined $2.5 billion including buyers’ fees, up from $1.3 billion in the same sales last May.
Is buying art a good investment?
The data says it’s a gamble. Some works soared (a Rothko jumped 607 percent since 2003), but others crashed hard, like a Warhol that lost nearly half its value since 2018. Outcomes vary wildly even in a strong season.
Why are auction houses selling fewer young artists?
The pandemic-era speculators chasing emerging “ultracontemporary” names are mostly gone. This season offered 112 works by artists born after 1975, down nearly 50 percent from the 2023 peak, as houses retreated to safer, deceased blue-chip painters.
The Bottom Line
The $2.5 billion comeback is a masterclass in managing a fragile market: lock in your risky inventory, presell your demand, wrap it in spectacle, and let the records make headlines. But founders should read it for the warning too. Engineered momentum buys you a great quarter, not a healthy business. When the rare inventory runs out and the financial scaffolding comes down, you still need real buyers who actually want what you’re selling.
Read the original reporting at The New York Times.