
Aritzia’s target market is women roughly 18 to 40 who want elevated, quality-driven basics without paying designer prices. But the demographic label is the least interesting part of the story. The commercially decisive fact about Aritzia’s audience in 2026 is geographic: the company now earns about C$34 per Canadian resident and only about C$7 per American resident, which means the U.S. customer base it has spent a decade chasing is still barely scratched. That gap, not the age bracket, is what explains a 35% revenue year.
Aritzia closed fiscal 2026 (the year ended March 1, 2026) with net revenue of C$3.70 billion, up 35.2%, and it hit its own fiscal 2027 revenue target a full year early. Comparable sales grew 26.5%, which means most of that growth came from existing stores and the website selling more, not from opening doors. Then the first quarter of fiscal 2027 came in at C$951 million, up 43%, with U.S. revenue up 54%.
Those are not the numbers of a mature specialty retailer. They are the numbers of a brand that has found a customer segment nobody else was serving properly and is now filling it in as fast as it can build stores. This analysis breaks down exactly who that customer is, how Aritzia segments her, and where the audience is heading next.
What is a target market?
Target market: the specific group of consumers a company designs its products, pricing, stores, and messaging around. It is narrower than the total addressable market. A target market is defined across five lenses: demographic (age, gender, income), psychographic (values, identity, aspiration), geographic (where they live and shop), behavioral (how they buy, how often, through which channel), and technographic (which platforms and devices mediate discovery and purchase).
For fashion retailers, the target market is not a marketing artifact. It is a capital allocation decision. Every store lease is a bet that a specific kind of person lives within driving distance.
The Aritzia customer: what the company actually discloses
Start with an honest caveat, because most articles on this topic will not give you one. Aritzia does not publish customer demographics. It does not disclose average customer age, household income, or gender breakdown in its filings or investor materials. Any article that hands you a confident “the Aritzia customer is 28 years old and earns $95,000” is reverse-engineering from vibes.
What the company does disclose, and what third-party data supports, gives us a more useful picture:
| Attribute | What the evidence supports |
|---|---|
| Gender | Overwhelmingly female. Aritzia’s exclusive brands are women’s labels. Menswear exists only through Reigning Champ, acquired via CYC Design in 2021, and men’s Super Puff styles. |
| Age | Broadly 18 to 40, with the commercial center of gravity in the mid-20s to mid-30s rather than the teen years. |
| Income | Comfortable but not wealthy. The pricing sits above mall fast fashion and well below designer. |
| Location | Urban and affluent-suburban North America, increasingly outside the coasts. |
| Channel | Omnichannel. Boutiques generated 65% of fiscal 2026 revenue, digital 35%, and both grew at nearly the same rate. |
The teen brand myth
Here is a data point that complicates the popular narrative. Piper Sandler’s Taking Stock With Teens survey, the most-watched read on U.S. teen brand preference, has consistently shown Aritzia hovering in the low single digits of mindshare among upper-income female teens, well behind Brandy Melville, American Eagle, Lululemon, and Hollister.
If Aritzia were primarily a teen brand, that would be a red flag. It is not. It is confirmation of the actual positioning. Aritzia sells a C$150 trouser and a C$250 puffer. That is not teen allowance money. The brand borrows teen cultural heat through TikTok and campus visibility, then monetizes the 25-to-40-year-old woman who has a salary, a commute, a wedding season, and a wardrobe she treats as infrastructure.
That distinction matters strategically. Brands that get trapped in the teen tier live and die on trend cycles. Brands that convert teen awareness into adult purchasing power, which is what Abercrombie also rebuilt itself around, get to compound.
Psychographic segmentation: the “Everyday Luxury” contract
Aritzia’s positioning statement is Everyday Luxury, and it is worth taking seriously as a segmentation tool rather than dismissing it as a tagline.
The target customer is someone who has rejected two adjacent options:
- She has aged out of fast fashion. She has bought the C$30 blazer that pilled after four wears and has decided the false economy is not worth it. Compare this to the Zara target market, which is built around trend velocity and price accessibility, and where the implicit promise is newness rather than durability.
- She has not entered luxury. She is not buying Celine or The Row. Either she cannot, or she has decided that a C$3,000 coat is an irrational allocation for a life that involves subways and coffee.
Everyday Luxury is the deliberate occupation of that gap. The psychographic profile is:
- Identity through restraint. Neutral palettes, minimal logos, clean silhouettes. The clothes signal taste rather than spend, which is precisely the currency of the post-2022 “quiet luxury” shift.
- Cost-per-wear reasoning. The customer is not price-insensitive. She is price-rationalizing. She will pay C$148 for a trouser she believes she will wear 200 times.
- Wardrobe as system, not as outfit. Aritzia’s brand house is designed for repeat purchase across categories, not for a single seasonal statement piece.
- Low tolerance for discounting. Aritzia runs roughly two major sale events a year. Scarcity of markdowns protects perceived value, and the customer has been trained to buy at full price.
That last point is the underrated one. A brand whose customer waits for the sale has a broken target market. Aritzia’s fiscal 2026 gross margin of 44.9%, up 180 basis points, tells you her willingness to pay is intact even after tariffs and the removal of the de minimis exemption hit the cost line.
Geographic segmentation: the actual story
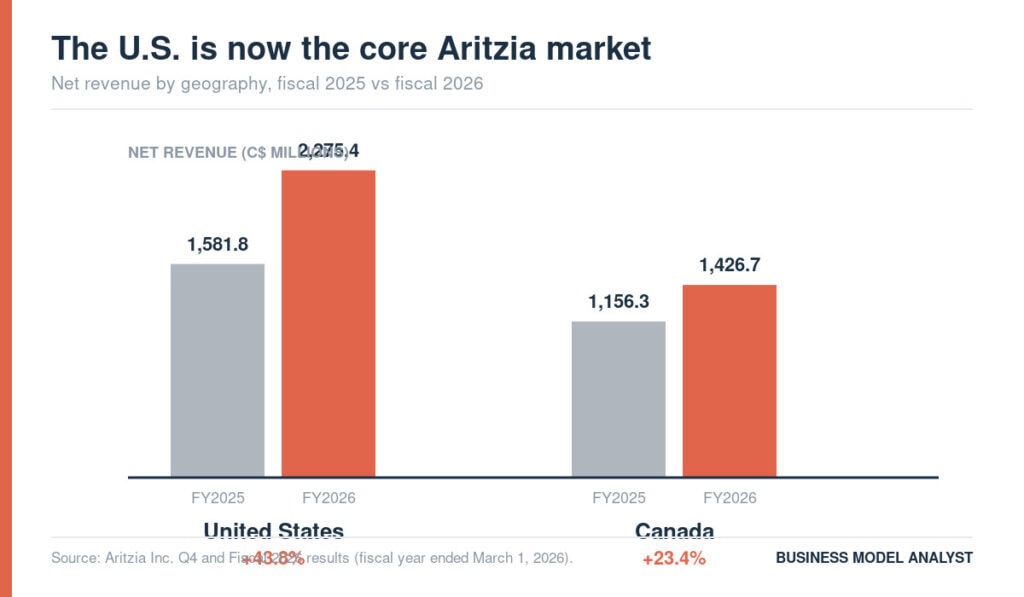
In fiscal 2026, U.S. net revenue rose 43.8% to C$2.28 billion while Canada rose 23.4% to C$1.43 billion. The United States is now about 62% of the business, and in the fourth quarter it was 63.7%.
That framing is standard. Here is the framing almost nobody runs.
The penetration gap
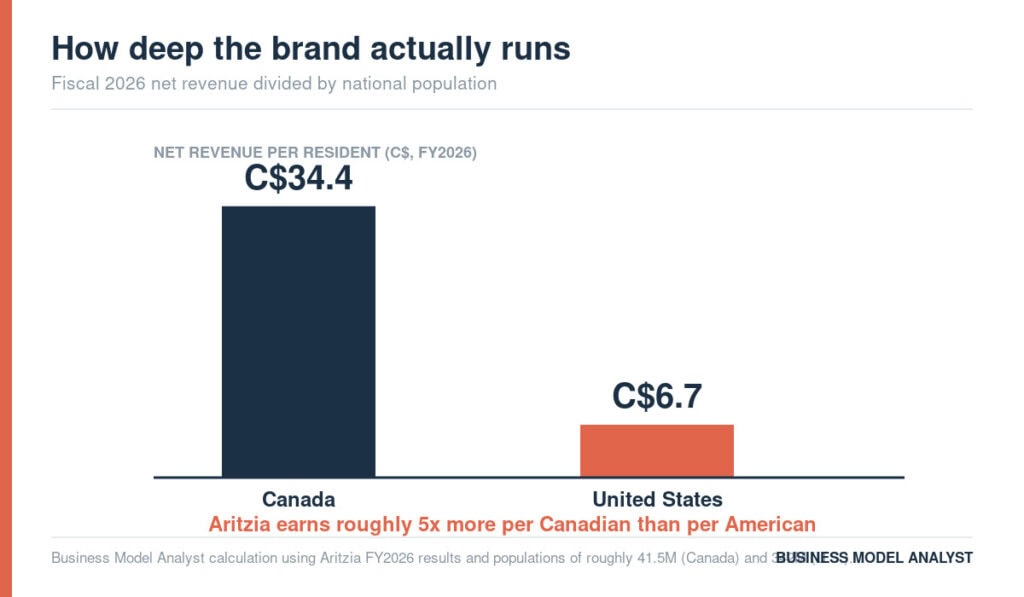
Divide fiscal 2026 net revenue by national population, using roughly 41.5 million Canadians and roughly 342 million Americans:
| Market | FY2026 net revenue | Population (approx.) | Revenue per resident |
|---|---|---|---|
| Canada | C$1.43 billion | 41.5 million | C$34.4 |
| United States | C$2.28 billion | 342 million | C$6.7 |
Aritzia extracts roughly five times more revenue per Canadian than per American. This is a Business Model Analyst calculation, not a company disclosure, and it is a blunt instrument. Canada is the home market with forty years of brand equity, and no brand ever replicates home-market intensity abroad.
But even a partial convergence is enormous. If Aritzia eventually reached half of its Canadian per-capita intensity in the U.S., that implies a U.S. business of roughly C$5.9 billion, about 2.6 times the current U.S. revenue. The target market is not a segment Aritzia is defending. It is a segment it has barely met.
The store map confirms it
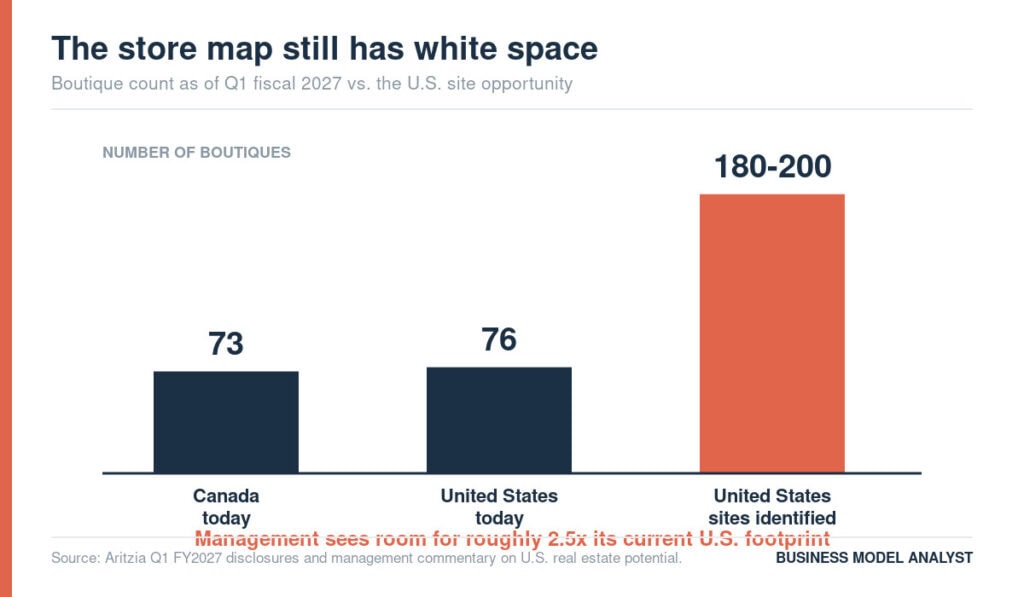
As of the first quarter of fiscal 2027, Aritzia operates about 143 boutiques, roughly 76 in the U.S. and roughly 73 in Canada. Management has said it sees room for approximately 180 to 200 U.S. locations that meet its site criteria.
Do the density math. Canada: one boutique per roughly 570,000 people. United States today: one per roughly 4.5 million. Even at a fully built-out 200 stores, the U.S. would sit at one per 1.7 million, still three times thinner than Canada.
And the geography of the next wave tells you where the target market is expanding. The three new U.S. boutiques slated for the second quarter of fiscal 2027 are in Birmingham, New Orleans, and St. Louis. Not SoHo. Not Rodeo Drive. These are markets where Aritzia has never operated, and management has said new stores are now paying back their capital investment in under a year against a stated target of 12 to 18 months.
Translation: the “urban coastal creative professional” caricature of the Aritzia customer is already out of date. She exists in Alabama, Louisiana, and Missouri, and she has been buying online for years while waiting for a store.
Behavioral segmentation: how she actually buys
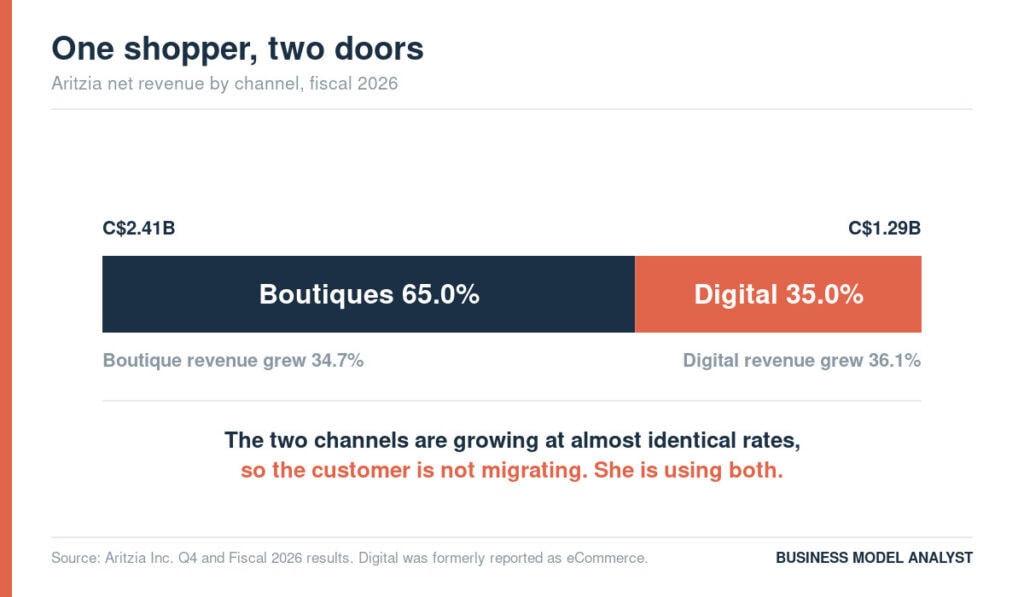
Boutiques generated C$2.41 billion in fiscal 2026, up 34.7%. Digital generated C$1.29 billion, up 36.1%. The two channels are growing within 1.5 percentage points of each other.
This is the tell that Aritzia’s customer is not migrating from stores to screens. She is using both, for different jobs. Discovery and reassurance happen in the boutique, where staffed personal shopping, cafés, and communal mirror areas turn a transaction into an afternoon. Replenishment and restock happen on the app, which Aritzia launched during fiscal 2026 and explicitly credits for its digital acceleration.
Other behavioral markers worth naming:
- Hero-product anchoring. The Super Puff, the Effortless Pant, and the Contour bodysuits function as entry points. A customer’s first purchase is usually a named product, not a category.
- Low promotional dependence. Two major sale windows per year. This shapes a customer who buys when she wants the item, not when the discount arrives.
- High repeat cadence in basics. The brand-house structure (below) is engineered so that a customer buying a TNA sweatsuit at 22 can be buying a Babaton blazer at 30 without ever leaving the building.
Brand-house segmentation: one customer, many stages of life
Aritzia’s most underappreciated segmentation tool is that it is not one brand. It is a portfolio of exclusive in-house labels sold under a single roof, which lets it segment the same woman across occasions and life stages instead of splitting her across competitors.
| Label | Segment it serves | Life-stage role |
|---|---|---|
| TNA | Casual, athleisure, campus-coded fleece and sweats | Entry point. Age 18 to 24, the acquisition engine. |
| Sunday Best | Feminine, trend-forward, occasion pieces | Social and going-out wardrobe. |
| Babaton / The Group by Babaton | Minimalist tailoring, blazers, trousers, knits | The professional core. Highest price, highest margin. |
| Wilfred / Wilfred Free | Elevated, romantic, design-led | The aspirational tier for the established customer. |
| Denim Forum | Premium in-house denim | Captures spend that would otherwise leak to AGOLDE or Citizens. |
| Golden | Performance and activewear | Direct answer to Lululemon and Alo. |
| The Super Puff | Technical outerwear franchise | The viral acquisition weapon and winter traffic driver. |
| Reigning Champ | Premium menswear | The only meaningful non-female segment. |
Vertical integration is the engine underneath. Because Aritzia designs and owns nearly all of these labels, it captures full margin on segment expansion. A multi-brand retailer that wanted to serve the same range of occasions would be paying wholesale margin to eight different vendors. This is the same structural logic that makes the Lululemon business model so profitable, applied to a much broader wardrobe.
The competitive set: who else is chasing this woman
| Competitor | Where it overlaps | Where Aritzia wins or loses |
|---|---|---|
| Lululemon | Athleisure, premium basics, similar income tier, Vancouver origin | Aritzia loses on technical performance, wins on wardrobe breadth. See the Lululemon target market for the contrast. |
| Abercrombie & Fitch | The same “teen heat converted to adult wallet” playbook, similar U.S. footprint | Abercrombie is cheaper and broader. Aritzia is more premium and more curated. |
| Zara | Trend-driven wardrobe staples at accessible prices | Zara wins on price and speed. Aritzia wins on quality perception and store experience. See the Zara business model. |
| Reformation / Madewell / Sézane | The elevated-basics niche, quiet-luxury adjacency | Similar aesthetic, far less scale and store footprint. |
| Alo Yoga / Vuori | Athleisure as everyday wear | Direct pressure on the Golden label. |
The strategic insight is that none of them own the whole wardrobe. Lululemon cannot sell you a wedding-guest dress. Zara cannot sell you a blazer you trust. Aritzia’s target market is defined less by who she is than by the fact that she wants one place that covers the gym, the office, and the party at a coherent quality level, and almost nobody offers that.
Where the target market goes next
Three signals from the last six months point at deliberate expansion of the audience definition.
1. Fred Segal. In February 2026, Aritzia acquired the Fred Segal brand and its intellectual property from Fred Segal Family LLC, along with a lease on the original 8100 Melrose Avenue flagship in Los Angeles. Financial terms were not disclosed. CEO Jennifer Wong framed it as stewarding a cultural touchstone for a new generation. Read it structurally: Fred Segal was a multi-brand, co-ed, experiential lifestyle destination. It is a vehicle for Aritzia to test an audience it cannot reach under its own banner, in the single most culturally productive retail market in the United States.
2. Menswear, quietly. Reigning Champ remains a small, separately counted operation, but the men’s Super Puff exists, and the Fred Segal platform is co-ed by nature. Aritzia has never made a loud menswear push. It does not have to. The realistic near-term male segment is the boyfriend, husband, or brother already standing in the boutique.
3. Non-coastal America. Birmingham, New Orleans, and St. Louis are the actual news. The bet is that Everyday Luxury is not a coastal taste but an income-and-aspiration profile that exists in every metropolitan area of 500,000 people or more.
What could break the thesis
Honest analysis requires naming the counterarguments a well-informed skeptic would raise.
- The comps are unrepeatable. Comparable sales grew 26.5% in fiscal 2026 and 35% in the first quarter of fiscal 2027. Nobody laps that forever. When comps normalize, the growth story becomes a store-count story, and store-count stories are valued very differently.
- Tariffs and the de minimis change are a real tax on the model. Aritzia absorbed roughly 260 basis points of margin pressure from tariffs and the elimination of the de minimis exemption in fiscal 2026 and still expanded margin. That is impressive. It is also a structurally worse cost base for a company that sells into the U.S. from a Canadian and Asian supply chain.
- The target market is one economic shock away from trading down. A woman who rationalizes C$148 trousers on cost-per-wear can also un-rationalize them. Aritzia’s customer is discretionary by definition, and the brand’s refusal to discount is a strength in an expansion and a liability in a contraction.
- Brand heat is not a moat. Aritzia’s U.S. growth is substantially an awareness story. Awareness can be bought by competitors. The durable moat, if there is one, is vertical integration and store productivity, not TikTok.
FAQ
Who is Aritzia’s target market? Women roughly 18 to 40, concentrated in the mid-20s to mid-30s, in urban and affluent-suburban North America, with enough disposable income to buy quality basics at premium prices. Aritzia does not publish demographic data, so precise age and income figures circulating online are estimates.
What age group shops at Aritzia? The brand spans roughly 18 to 40 through its label portfolio: TNA skews youngest, Babaton and Wilfred skew toward established professionals. Notably, Aritzia is not a dominant teen brand. It ranks low in teen mindshare surveys, which is consistent with its price architecture.
Is Aritzia a luxury brand? No. Aritzia positions itself as “Everyday Luxury,” which sits deliberately between fast fashion and designer luxury. A trouser runs about C$148 and a Super Puff about C$250, well below designer price points.
Is Aritzia bigger in the U.S. or Canada? The United States. U.S. net revenue was C$2.28 billion in fiscal 2026, about 62% of the company total, and it grew 43.8% versus 23.4% in Canada. In the first quarter of fiscal 2027, U.S. revenue grew 54%.
Does Aritzia sell menswear? Only indirectly, through Reigning Champ (acquired via CYC Design Corporation) and men’s Super Puff styles. The core Aritzia banner is women’s. The Fred Segal acquisition may change this.
Who are Aritzia’s main competitors? Lululemon, Abercrombie & Fitch, Zara, Reformation, Madewell, Alo Yoga, and Free People, depending on the category. No single competitor covers the full wardrobe range Aritzia does.
The Business Model Analyst Take
Most target market analyses of Aritzia stop at “Gen Z and millennial women who like minimalist clothes.” That description is true and almost useless, because it describes fifty brands.
The sharper reading is that Aritzia’s target market is not primarily a demographic. It is a behavior: the woman who has decided to stop buying disposable clothing but has not decided to start buying luxury, and who wants one retailer to handle her entire wardrobe at a consistent quality bar. That behavior is not new. What is new is that, until recently, nobody was serving it at scale in the United States.
The five-to-one revenue-per-capita gap between Canada and the U.S. is the single most important number in this analysis. It says the U.S. business is not a mature segment being defended; it is an under-penetrated segment being discovered, one 10,000-square-foot boutique at a time, and the fact that new stores are now paying back capital in under a year means the discovery is not speculative.
The risk is that Aritzia is confusing a cyclical awareness wave with a structural position. Brand heat mean-reverts. Comps of 35% do not persist. When the growth rate normalizes, the market will re-rate the stock on store economics rather than momentum, and the question will become whether Everyday Luxury is a category Aritzia owns or merely a gap it found first.
Our view: the vertical integration and the brand-house architecture make this defensible in a way that pure trend brands are not. Aritzia is not selling a look. It is selling a wardrobe operating system to a woman who has decided she is done shopping around. That customer does not churn easily. But she does trade down in a recession, and Aritzia has never faced one at this scale.
Watch the comps. When they land in the single digits, we will find out whether the target market was loyal or just enthusiastic.