
Apple did something on June 25, 2026 that it almost never does: it raised prices mid-cycle across nearly its entire hardware lineup, with no new specs to justify the bump. The trigger is a memory and storage shortage so severe that CEO Tim Cook called it a “hundred-year flood.” The iPhone was spared, for now. The stock was not, falling 6.12% to $275.15, its worst single day since April 2025.
What Apple changed
The new prices went live globally on Apple’s online store on Thursday morning, after the store briefly went dark and came back with the increases already in place. The hikes hit the Mac, iPad, Apple TV, HomePod, HomePod mini, and Vision Pro lines. Apple did not add storage or memory to any of these models, so buyers are paying more for the exact same hardware.
The entry-level MacBook Neo, introduced earlier this year as Apple’s budget play, jumped from $599 to $699. The cheapest iPad went from $349 to $449. At the extreme end, the M3 Ultra Mac Studio climbed $1,300, from $3,999 to $5,299.
Apple was blunt about the cause. In its statement, the company said the rapid expansion of AI data centers has created an “extraordinary surge” in demand for memory and storage, adding that it had never seen component prices rise this much, this quickly.
The full price breakdown
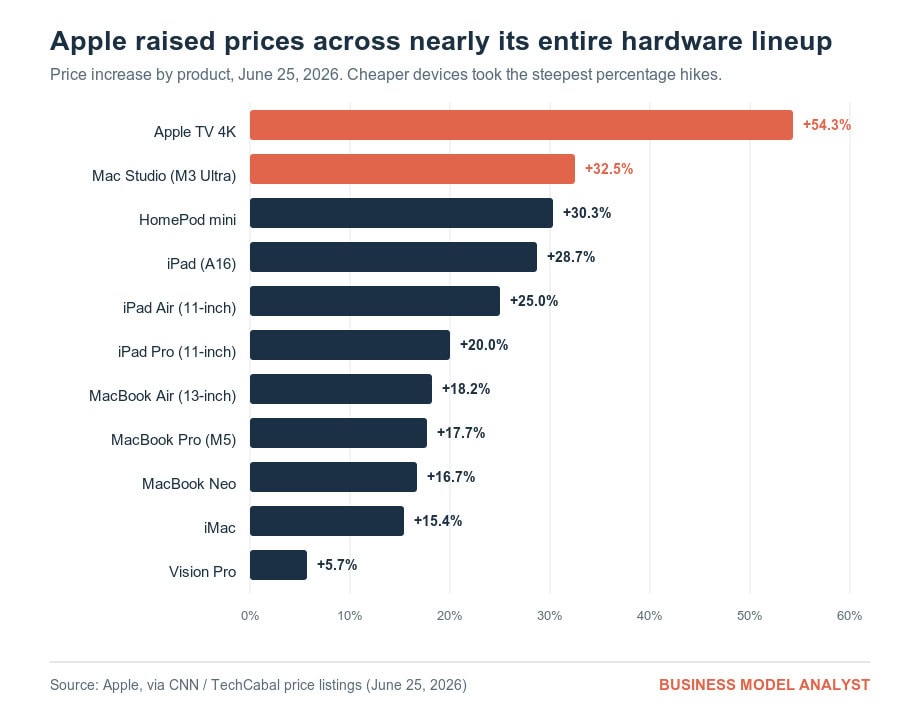
The increases ranged from $30 on the HomePod mini to $1,300 on the top Mac Studio. In percentage terms, the cheapest devices took the hardest hits.
Mac
| Product | Old price | New price | Change |
|---|---|---|---|
| MacBook Neo | $599 | $699 | +$100 (16.7%) |
| 13-inch MacBook Air | $1,099 | $1,299 | +$200 (18.2%) |
| 15-inch MacBook Air | $1,299 | $1,499 | +$200 (15.4%) |
| M5 MacBook Pro | $1,699 | $1,999 | +$300 (17.7%) |
| M5 Pro MacBook Pro | $2,199 | $2,499 | +$300 (13.6%) |
| M5 Max MacBook Pro | $3,599 | $4,099 | +$500 (13.9%) |
| iMac | $1,299 | $1,499 | +$200 (15.4%) |
| Mac Studio (M4 Max) | $1,999 | $2,499 | +$500 (25.0%) |
| Mac Studio (M3 Ultra) | $3,999 | $5,299 | +$1,300 (32.5%) |
| Mac mini (M4 Pro) | $1,399 | $1,599 | +$200 (14.3%) |
iPad
| Product | Old price | New price | Change |
|---|---|---|---|
| iPad (A16) | $349 | $449 | +$100 (28.7%) |
| iPad Air 11-inch | $599 | $749 | +$150 (25.0%) |
| iPad Air 13-inch | $749 | $949 | +$200 (26.7%) |
| iPad Pro 11-inch | $999 | $1,199 | +$200 (20.0%) |
| iPad Pro 13-inch | $1,299 | $1,499 | +$200 (15.4%) |
| iPad mini | $499 | $599 | +$100 (20.0%) |
Apple TV, HomePod, and Vision Pro
| Product | Old price | New price | Change |
|---|---|---|---|
| Apple TV 4K | $129 | $199 | +$70 (54.3%) |
| HomePod | $299 | $349 | +$50 (16.7%) |
| HomePod mini | $99 | $129 | +$30 (30.3%) |
| Vision Pro | $3,499 | $3,699 | +$200 (5.7%) |
What stayed flat
Apple left several products untouched. The iPhone, every current model, kept its old price. So did the Apple Watch, AirPods, the Studio Display, and the Apple Pencil. The company hinted that more adjustments could follow, which most analysts read as a near-certainty rather than a possibility.
Why the shortage is happening
The root cause is a reallocation of global memory production toward AI. Samsung, SK Hynix, and Micron control more than 95% of DRAM output, and all three have been shifting capacity toward high-bandwidth memory (HBM), the specialized chips that sit inside Nvidia’s AI server clusters. HBM carries roughly 60% margins versus around 40% for commodity DRAM, so every wafer redirected to AI is a wafer pulled away from the LPDDR memory inside phones, laptops, and tablets.
The price math is brutal. Contract DRAM prices jumped about 90% in the first quarter of 2026 and another 60% in the second, per TrendForce. By Apple’s own framing, memory and storage now cost roughly four times what they did three quarters ago.
The clearest proof of where the money is going sits in Micron’s latest quarter: revenue more than quadrupled, up 346% year over year to $41.46 billion, with gross margin hitting roughly 85%, a level that briefly put a memory maker ahead of Nvidia on that metric.
Why this matters for Apple’s business model
Here is the part that should interest anyone studying how Apple actually makes money. Apple builds memory and storage into every single product it sells, which means a cost spike of this size cannot be absorbed quietly. The Apple business model has always paired premium hardware pricing with a high-margin services engine, and both halves of that machine are now under stress at once.
In its March quarter (fiscal Q2 2026), Apple posted a 49.3% gross margin, up from 47.1% a year earlier, helped by a record services quarter near $31 billion. Those numbers landed before the worst of the memory squeeze hit. For the June quarter, Apple has already guided gross margin down to a 47.5% to 48.5% range. Every 100 basis points of margin pressure removes roughly $3.8 billion from annual operating income, which is why even a one-point move matters.
That gives Apple a binary choice on each product: absorb the cost and watch its prized margins compress, or pass it on and risk softening demand for devices that just got more expensive. On Thursday, Apple chose to pass it on. The market read that as an admission that the cost problem is real and arriving fast, which is the simplest explanation for a 6% drop in a stock that had logged only one other move larger than 5% all year.
The iPhone is the number that actually moved the stock
Mac and iPad together account for only about 14% of Apple’s revenue. The iPhone is roughly half. So the Thursday hikes, in isolation, are not large enough to justify a 6% selloff. What the market was really pricing is the iPhone hike that has not happened yet.
JPMorgan has flagged that DRAM and NAND could climb from 10% to 15% of an iPhone’s component cost today to more than 45% by 2027. TechInsights estimates Apple would need to lift iPhone 18 Pro pricing by around $270, from $999 to roughly $1,269, just to hold current margins. Analyst estimates for the coming iPhone increase range widely, from about $50 (JPMorgan) to as much as $270 (TechInsights), with Counterpoint landing at $150 to $200. Most expect the move to arrive with the iPhone 18 launch in September, though Apple could adjust existing-product pricing sooner during its Back to School window.
Apple is better positioned than almost anyone to survive this
The memory shock is industry-wide. Microsoft has raised Xbox prices, Samsung lifted the Galaxy S26 lineup, Sony and Nintendo have bumped console prices, and Dell, HP, Lenovo, Acer, and ASUS have all raised laptop prices. IDC has called the impact “highly asymmetric,” and that asymmetry favors Apple for three structural reasons.
First, demand inelasticity. A 2026 survey found 96.4% of iPhone users plan to buy another iPhone, up from 91.9% in 2021. That base does not walk away over a $200 increase. Second, the services buffer. Apple’s high-margin services segment keeps growing regardless of the hardware cycle, and a thinner margin on hardware is far more manageable when the same customer keeps paying monthly across subscriptions, as we detail in our breakdown of the App Store’s $1.4 trillion economy. Third, scale. Budget Android makers, where memory can be 15% to 20% of build cost on thin margins, have far less room to maneuver than a company with Apple’s pricing power and ecosystem lock-in, the same dynamics covered in our Apple SWOT analysis.
How long the squeeze lasts
This is not a one-quarter event. Micron expects tight supply beyond 2027, Intel’s CEO has said relief is unlikely before 2028, and some analysts see pricing pressure lasting toward 2030. Micron has also locked in around $100 billion of minimum revenue through take-or-pay contracts running to 2030, which means hyperscalers have effectively reserved memory supply at elevated prices for years. The practical takeaway for consumers is blunt: companies rarely roll back prices once they go up, so these new numbers are likely here to stay even after the shortage eases.
The Business Model Analyst Take
The instinct is to read this as Apple defending its margins, and that is partly true. But the more interesting signal is what a mid-cycle, no-new-specs price hike says about Apple’s pricing power. For years, Apple’s premium pricing strategy rested on the idea that customers pay more because they get more. Thursday broke that link. Buyers are now paying 15% to 54% more for identical hardware, and Apple is betting the ecosystem is sticky enough that they will.
That bet is probably correct on the Mac and iPad, which serve a captive, upgrade-driven base. The real test is the iPhone. If Apple can push a $200-plus increase through its highest-volume product without denting unit demand, it will have proven that its ecosystem moat is strong enough to convert a supply shock directly into revenue. If demand softens, the company will have to choose between volume and margin in its most important product line for the first time in years. The July 30 earnings call, and the gross-margin number on it, is where we find out which Apple this is. Watch that figure against the 47.5% to 48.5% guide: at or above, the price hikes are working; below, the flood is reaching earnings faster than Apple can route around it.