
John Ternus took over on September 1 with 108 years of executive tenure already walking out the door, and the pay plan designed to prevent exactly that is the reason it happened.
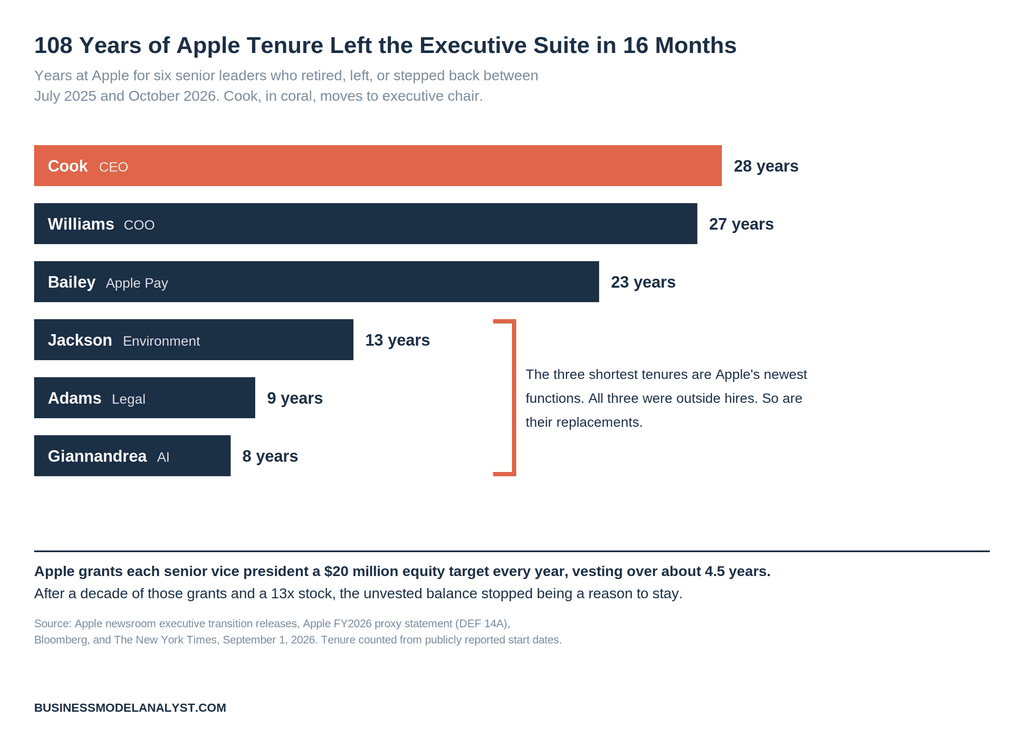
Apple grants each senior vice president a $20 million equity target every year, vesting over roughly four and a half years, a schedule the company’s own proxy statement describes as longer than its peer group’s. That design binds an executive right up until the amount already banked makes the amount still vesting irrelevant. Under Tim Cook, Apple’s market value rose about 13 times over. Between July 2025 and October 2026, six senior leaders holding 108 combined years of Apple tenure retired, left, or stepped back. Ternus is rebuilding the layer below him with hires from Meta, Microsoft, American Airlines, and one person who had already retired.
Every story about Apple’s handover is being written as a product story. Can the new guy do a foldable, can he fix Siri, can he be interesting.
Fine questions. But the more expensive problem sitting on John Ternus’s desk has nothing to do with hardware. It is that the people who used to answer those questions have mostly stopped showing up, and the compensation machine Apple built to keep them is the thing that let them go.
Retention through equity has a shelf life. It runs out precisely when the stock does its job.
What Happened
Ternus, 51, became Apple’s eighth chief executive on Tuesday, September 1, succeeding Cook after fifteen years. Cook stays on as executive chair, with Apple saying he will help on certain matters including engagement with policymakers around the world. The New York Times reported that nearly half of Ternus’s executive team is nearing traditional retirement age.
Count what has already gone. Jeff Williams handed the COO job to Sabih Khan in July 2025 and retired after 27 years. John Giannandrea, hired in 2018 to run machine learning and AI strategy, stepped aside that December and retired in the spring. Lisa Jackson, at Apple since 2013, retired in late January 2026. General counsel Kate Adams, in the seat since 2017, retires this year. Jennifer Bailey, who has run Apple Pay since its 2014 launch and joined the company in 2003, retires at the end of October. Add Cook’s move upstairs and you get six leaders and 108 years of institutional memory, all repositioned inside sixteen months.
That is only the named tier. Alan Dye, who led human interface design since 2015, left for Meta at the end of 2025 and took senior design director Billy Sorrentino with him. Ruoming Pang, who ran Apple’s foundation models team, went to Meta in July 2025. Brian Lynch took smart home hardware to Oura in March. Paul Meade took mixed reality hardware to OpenAI in July. Apple’s own trade secret complaint against OpenAI put the count of former Apple employees now working there at more than 400. Luca Maestri and Phil Schiller are still on the badge list in smaller roles.
The Backstory
Here is the part nobody is connecting.
Apple’s FY2026 proxy shows that Adams, Khan and Deirdre O’Brien each carried an identical $20 million target for their long term equity award in 2023, 2024 and 2025. Reported grant date value came in around $22 million apiece, with total compensation of roughly $27.03 million each. Cook’s target was $50 million, inside a $74.3 million package. The restricted stock vests over about four and a half years, and Apple explicitly flags that schedule as longer than what its peer group uses, which ties executive wealth to multi year stability.
That is a well designed handcuff. Now run the arithmetic on what it is actually worth to the person wearing it.
Once the grant stack is running, a senior vice president is carrying roughly two years of unvested awards at any moment, call it $40 to $45 million measured at the price it was struck. Real money. Now count the other side of the ledger. Ten years of $20 million grants is $200 million at grant value, and those grants vested into a stock that multiplied roughly thirteen times over Cook’s tenure while the company returned more than $1 trillion to shareholders. The realized number is a large multiple of the face number.
So the handcuff is worth maybe a fifth of the pile, and walking away costs about $20 million a year of forward income against a nine figure balance sheet. Bloomberg reported the same thing in plain language: this cohort grew wealthy over decades and no longer needs to work.
Apple engineered the longest vesting ladder among its peers and it still lost the group. Duration was never the binding constraint. Ratio was.
The Plan
Look at how Ternus is refilling the room, because the sourcing tells you where the bench actually was.
Internally, Apple promoted Khan to COO after 30 years, elevated Johny Srouji to chief hardware officer in April, put Kevan Parekh in the CFO chair, and moved Steve Lemay into design. Those are the mature functions, the ones with twenty years of succession runway underneath them.
Externally is where it gets interesting. Legal went to Jennifer Newstead, poached from Meta’s chief legal officer job, in a near perfect swap for the design chief Meta poached from Apple weeks earlier. AI went to Amar Subramanya, out of Microsoft by way of sixteen years at Google. Government affairs went to Nate Gatten, hired out of American Airlines, which is to say Apple went shopping for regulatory muscle in one of the most politically managed industries in America.
And then there is Laura Legros, a hardware engineering vice president and Ternus’s former deputy, who retired in 2022 and has now rejoined. She reports directly to Ternus and, per the Times, could work as his adviser and emissary across the company. That is a coordination role by another name, and it is what you create when you cannot lean on the peer layer yet.
The pattern is clean. Where Apple had depth, it promoted. Where the function was young, it bought. And where it needed a trusted operator immediately, it called someone who had already left.
The Business Model Angle
Equity retention has an expiry date, and success brings it forward. Any plan whose holding power comes from appreciation stops working at the moment it delivers. The crossover is calculable: the year when banked value makes the unvested balance immaterial. For a high performing company that arrives around year eight to twelve, not year twenty, and the better the stock does the sooner it lands. If your retention model is a vesting schedule, you are running a clock, not a lock.
Zero turnover at the top guarantees zero bench beneath it. Fifteen years of stability in the executive suite means fifteen years without a vacancy for the layer below to compete for. Nobody gets tested, so nobody gets identified, so when the cliff arrives there is no internal answer. Stability is booked as a benefit every quarter and paid for all at once. Forced rotation is expensive and unpopular. It is cheaper than buying a leadership team at market prices.
The boomerang hire is a bench depth indicator, and it is free to watch. When an organization reaches back into its retiree list for a senior role, that is the fastest, cheapest public signal that the internal candidate list was thin. It costs nothing to track in any company you own or compete with, and it usually precedes the outside hires by a quarter or two.
The Risk
The strongest case against all of this is that Apple planned it.
The sequence was public and orderly: COO succession announced in July 2025, AI leadership reset that December with a named replacement, a general counsel hired months before the incumbent left, and the CEO announced in April for a September start. That is not an exodus, that is a schedule. Apple also runs a functional organizational structure in which knowledge sits in disciplines rather than in individual general managers, which is precisely the design that makes a company survivable when a name leaves. Jennifer Chatman of Berkeley Haas asked the sharper version of the question in the Times, wondering whether Apple is “getting enough new ideas in.” Fifteen years of the same brain trust has a cost too.
There is also a real argument that the exodus re arms the mechanism. Newstead, Subramanya and Gatten each start with nothing banked and a full four and a half year ladder in front of them. On paper, Ternus now runs the most locked in senior team Apple has had in a decade, and the supplier commitment book he inherited is a more urgent problem than his org chart. The business model itself has not changed at all.
What would falsify the reading: Cue, O’Brien and Joswiak, each roughly four decades in, staying put through 2027. A new retention grant structure showing up in the next proxy. A September 9 hardware event strong enough to reset the internal mood. Watch those three.
Quick Questions
Is Tim Cook still at Apple? Yes. He is executive chair, with a mandate Apple has scoped around engagement with policymakers rather than product or operations.
How much does Apple pay a senior vice president? Roughly $27 million in fiscal 2025 for Adams, Khan and O’Brien, built on an identical $20 million annual equity target plus $1 million salary and a $4 million cash incentive.
Why are so many Apple executives leaving at the same time? Two forces stacked. A cohort hired in the 1980s and 1990s is hitting retirement age together, and the equity that was supposed to hold them has already paid out at thirteen times the value it was granted against.
Did Apple promote from within? For the operating roles, yes. Khan, Srouji, Parekh and Lemay are all internal. Legal, AI and government affairs all came from outside.
What is the number to watch? How many of Ternus’s next five senior appointments come from inside Apple. That ratio is the honest read on whether the bench is rebuilding or still being rented.
The Business Model Analyst Take
Cook’s fifteen years produced the most stable executive team in large cap technology, and stability of that length is not a governance trophy. It is a deferred liability that accrues quietly and settles in one window.
The tell is that Apple did succession brilliantly for exactly one job. The CEO handoff was telegraphed for years, staged over months, and executed without a wobble. The forty jobs underneath it were never planned for, because nobody ever left, so nobody ever had to be developed.
Ternus inherits a company where the retention plan worked so well it finished. Every executive it was meant to hold is now rich enough to ignore it, and the replacements arrive with fresh ladders and no history. That is the trade he did not choose: fifteen years of institutional memory swapped for fifteen years of unvested stock.
Golden handcuffs are only handcuffs while the key is still out of reach.