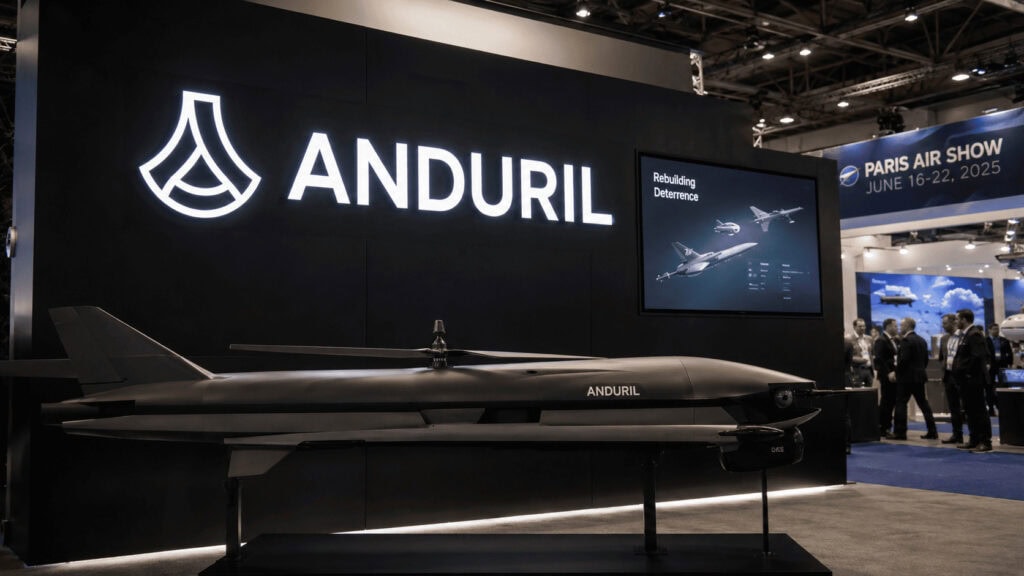

Anduril does not sell defense work. It sells finished weapons, the way Apple sells phones, and that one switch is why it is worth more than most companies on the Fortune 500.
Anduril Industries is an American defense technology company founded in 2017 by Palmer Luckey, Trae Stephens, Brian Schimpf, Matt Grimm, and Joe Chen, headquartered in Costa Mesa, California. Its business model inverts the defense industry’s standard playbook: instead of waiting for a government contract and billing for time and materials (the “cost-plus” model), Anduril self-funds research and development, builds autonomous systems and AI software upfront, and sells them as finished products at firm-fixed prices. The economic engine underneath the hardware is Lattice, an AI software platform that ties every product into one command-and-control layer and creates recurring, high-margin, sticky revenue. Key takeaway: Anduril turned defense hardware into a software business. Drones, towers, and submarines are the delivery vehicles. The software platform is the moat, the margin, and the reason customers cannot easily leave.
The model in one sentence
Most defense primes get paid to try. Anduril only gets paid when it delivers. Founder Palmer Luckey is blunt about the distinction: Anduril is a “defense products company,” not a defense contractor. The company eats the R&D risk, ships a working system, and then says “try it.” If the product fails, Anduril absorbs the cost. If it works, the firm-fixed-price contract means every efficiency gain flows straight to margin.
That is the whole thesis. Everything else is execution.
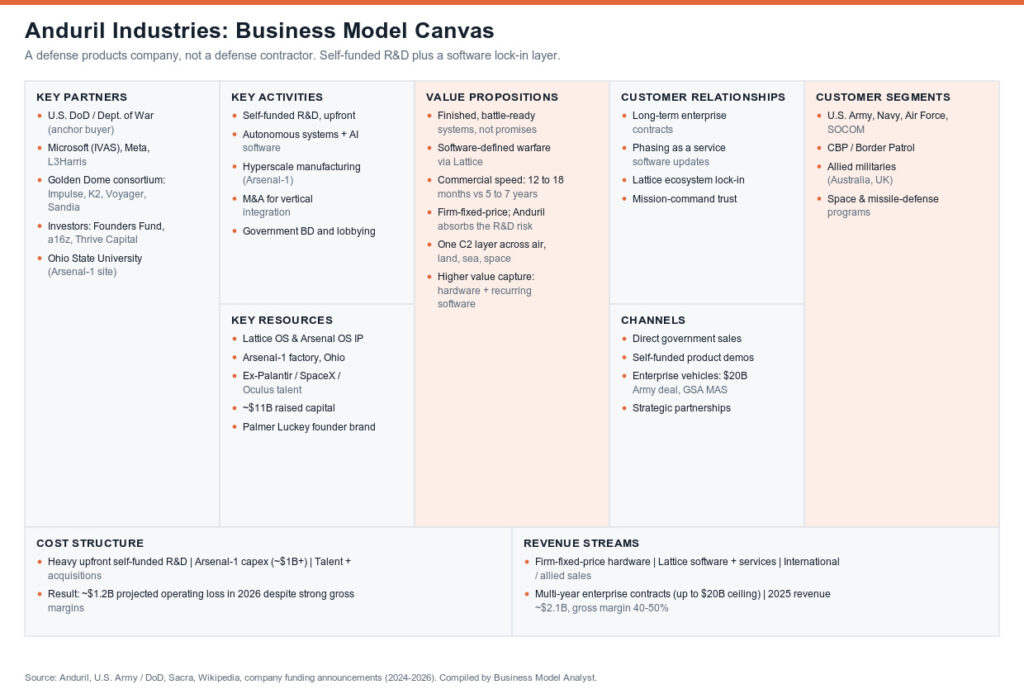
Cost-plus vs commercial: the switch that built a $61B company
To see why Anduril matters, you have to understand the model it is attacking. For decades, the “Big Five” primes operated on cost-plus contracts: the government writes a detailed spec, picks a contractor, and pays for labor, materials, and a fixed percentage of profit on top. The structural problem is the incentive. When your margin is a percentage of cost, expensive and slow is good for business.
Anduril flipped every variable.
| Dimension | Traditional primes (cost-plus) | Anduril (commercial / fixed-price) |
|---|---|---|
| Who funds R&D | The government (taxpayer) | Anduril, upfront, with private capital |
| How they get paid | For time and materials, plus a fixed margin | A fixed price for a finished product |
| Incentive created | Spend more, take longer | Build faster, cut cost, keep the savings |
| Development timeline | 5 to 7 years | 12 to 18 months |
| Estimated gross margin | 8 to 12% | 40 to 50% |
| Procurement trigger | Government issues a spec (build to spec) | Anduril anticipates the need (build to mission) |
| IP ownership | Often shared or government-owned | Anduril keeps it |
The “build to mission, not build to spec” line is the part founders should steal. Anduril builds things the Pentagon has not asked for yet, often things it has “written off as not feasible,” in Luckey’s words, then shows up with a working unit. That collapses the sales cycle and lets Anduril own the IP and the roadmap. It is closer to how a consumer hardware startup operates than how Lockheed operates. The closest analogue is not a defense company at all. It is Palantir’s business model: software-defined, sticky, and government-anchored.
Lattice: the flywheel that makes the margins real
Hardware sales are mostly one-off. A drone is a drone. So where does the recurring, software-like margin come from? Lattice.
Lattice is the AI operating system that ingests data from every sensor, drone, tower, and submarine and fuses it into a single real-time picture, then coordinates autonomous responses across air, land, sea, and space. Every new piece of hardware Anduril builds makes the Lattice network smarter and more valuable. That is the flywheel:
- More hardware in the field means more data feeding Lattice.
- A smarter Lattice makes every existing system more capable.
- A more capable network raises the switching cost of ever leaving it.
On top of that, Anduril runs what it calls “phasing as a service.” Its software-defined systems get continuous capability updates under ongoing, fixed-price service contracts, so a customer’s hardware does not go obsolete. That is a subscription dynamic dressed in defense clothing, and it is exactly why the company can earn software margins on metal.
Revenue: doubling, then doubling again
The growth is not subtle. Anduril roughly doubled revenue to about $1 billion in 2024, then did it again in 2025.
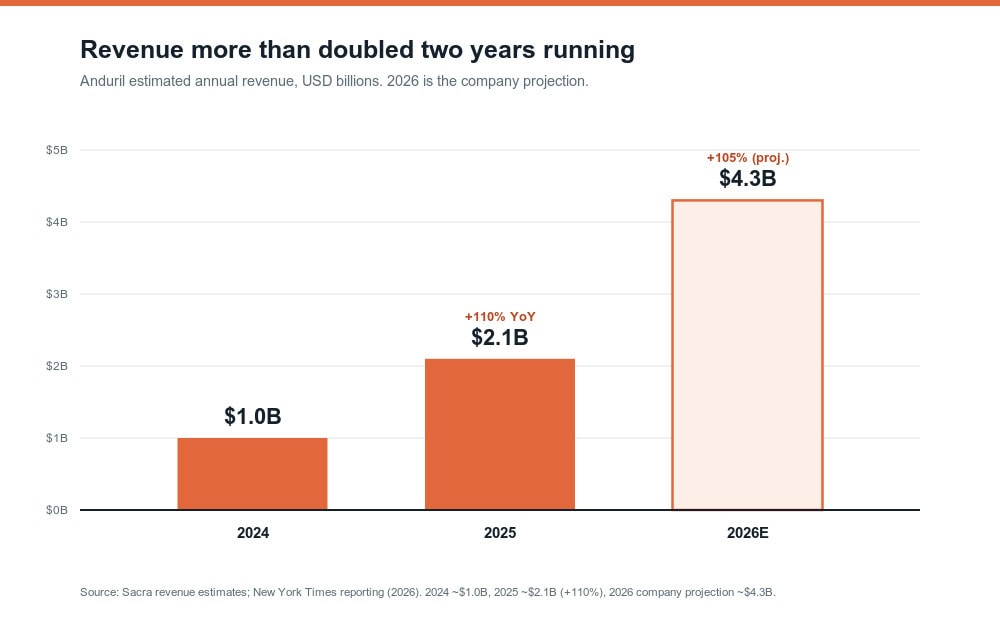
Independent estimates from Sacra put 2025 revenue near $2.1 billion, up about 110% year over year, with the company projecting roughly $4.3 billion for 2026 as the Arsenal-1 factory scales. The New York Times reported a similar figure of around $2 billion for the prior year. For a company that sells physical defense hardware, that is a software-grade growth curve.
How Anduril actually makes money
The revenue mix is where the model gets interesting. It is not just selling boxes.
| Revenue stream | What it is | Why it matters |
|---|---|---|
| Firm-fixed-price hardware | Drones, towers, interceptors, submarines sold as finished units | High margin because Anduril controls cost and IP |
| Lattice software and services | The C2 platform, integration, and “phasing as a service” updates | Recurring, sticky, software-like economics |
| Enterprise contracts | Multi-year vehicles like the $20B Army deal | Scale and predictability, consolidates many small buys |
| International / allied sales | Australia, UK, and other allied militaries | Diversifies beyond a single buyer, within US export rules |
The margin story is the headline. At an estimated 40 to 50% gross margin, Anduril is operating at roughly four to five times the gross margin of a traditional prime.
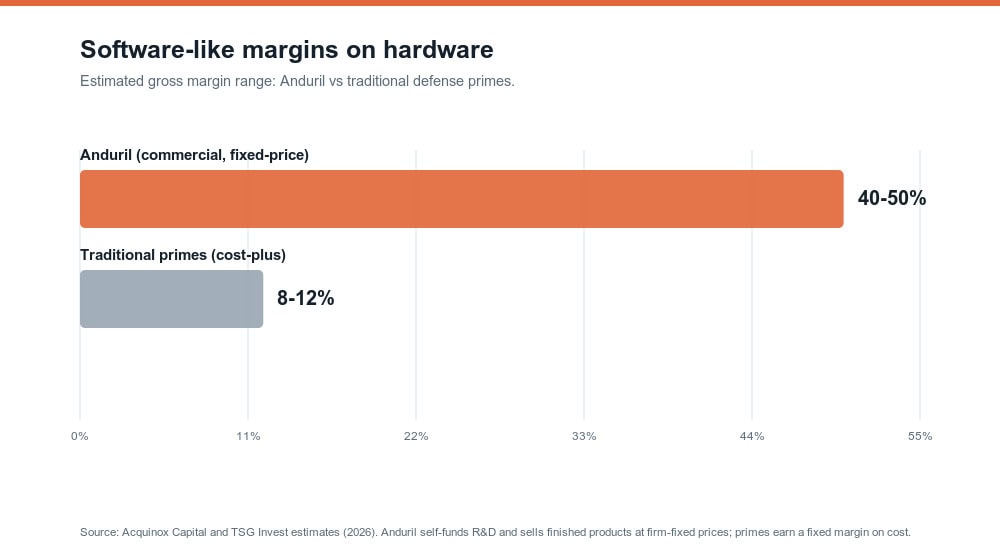
That gap is the entire reason private investors have piled in. It says Anduril is not really competing on platforms. It is competing on the economics of how those platforms get built and sold.
Vertical integration: owning the whole stack
Anduril’s margins are not magic. They come from owning the supply chain rather than assembling other people’s parts. The company has bought its way into propulsion, sensors, ruggedized computing, and space surveillance, folding each acquisition into the Lattice ecosystem.
| Acquisition | Year | What it added |
|---|---|---|
| Area-I | 2021 | Small drone technology |
| Dive Technologies | 2022 | Autonomous undersea vehicles |
| Adranos | 2023 | Solid rocket motors for missiles |
| Blue Force Technologies | 2023 | The foundation for the Fury autonomous fighter jet |
| Numerica (radar / C2) | 2025 | Radar systems and command-and-control software |
| Klas | 2025 | Ruggedized edge-computing hardware |
| American Infrared Solutions | 2025 | In-house infrared cameras and components |
| ExoAnalytic Solutions | 2026 | A 400-telescope space-surveillance network |
Anduril says nearly 90% of its products can be built at scale using commercially available components. That is the unlock behind Arsenal-1, its hyperscale factory near Columbus, Ohio. Anduril is putting roughly $1 billion of its own money into a 5-million-square-foot, 500-acre site designed to produce tens of thousands of autonomous systems a year, run on “Arsenal OS,” a manufacturing software layer modeled on Lattice. The bet is simple and aggressive: competitors build prototypes, Anduril builds a gigafactory. If it works, the production gap becomes a moat no rival startup can cross.
The valuation climb
Investors have rewarded the model with one of the steepest private valuation curves of the decade.
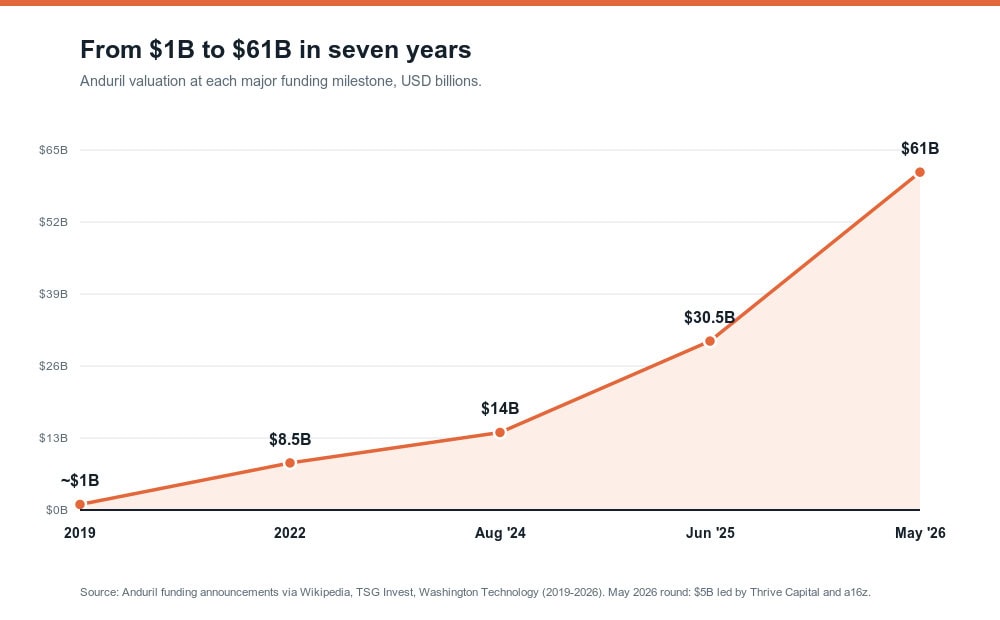
Anduril went from roughly $1 billion in 2019 to $8.5 billion in 2022, $14 billion in August 2024, $30.5 billion in mid-2025, and $61 billion in May 2026 after a $5 billion round led by Thrive Capital and Andreessen Horowitz. Total funding now sits north of $11 billion. That climb tracks a broader shift in venture capital: the highest private valuations are no longer reserved for pure software. They are flowing to capital-intensive, regulation-adjacent businesses, the same pattern visible in SpaceX’s business model and across the fastest-growing startups of 2026, where Anduril sits at number one. As one analyst put it, the moat is the friction. Anduril absorbs regulatory, physical, and geopolitical complexity that pure-software firms cannot replicate quickly.
The customer: one enormous, complicated buyer
Here is the uncomfortable truth underneath the growth. Anduril essentially has one customer: the US government, plus allies that the US government allows it to sell to. That concentration cuts both ways, and the contract wins show why the upside is real.
| Contract / program | Scale | What it covers |
|---|---|---|
| US Army enterprise contract (March 2026) | Up to $20B over 10 years | Consolidates 120+ procurements around the Lattice platform |
| IVAS (taken over from Microsoft, Feb 2025) | $22B program ceiling | Army mixed-reality combat goggle |
| SOCOM contract | Up to $1B | Special Operations capabilities |
| SBMC / mixed reality awards | $159M + $354M | Soldier-borne mission command goggles |
The $20 billion Army deal is the model in microcosm. It is firm-fixed-price, runs through March 2036, and folds more than 120 separate buys into one vehicle built around Lattice as the command-and-control backbone. For comparison, Palantir landed a similar $10 billion enterprise deal consolidating 75 contracts. The Pentagon is clearly betting on the software-first procurement model, and Anduril and Palantir are the two names cashing the checks.
Why the model works: the moats
Strip away the hype and four durable advantages remain:
- Software lock-in. Once Lattice is the C2 layer, ripping it out means rebuilding the entire kill chain. That is switching cost in its purest form.
- Speed as a weapon. Fielding capability in months instead of years is an arbitrage on the Pentagon’s own slowness.
- Manufacturing scale. Arsenal-1 turns production capacity into a structural cost advantage rivals cannot match on prototypes.
- Vertical integration. Owning sensors, propulsion, compute, and software means Anduril controls quality, cost, and roadmap end to end.
The Risk
Now the part the investor decks skip past. This model is not bulletproof.
The customer concentration is extreme. Anduril’s fortunes rise and fall with US defense priorities and budget cycles. The company has been embraced by the current administration, which is great until administrations change. A single complex buyer means traditional market dynamics do not apply, and political wind shifts hit harder than competitive ones.
The contract numbers are ceilings, not cash. That $20 billion Army figure is a maximum potential value over ten years, not obligated revenue. The real money depends on individual task orders that may or may not materialize. Treating the ceiling as guaranteed revenue is exactly the kind of lazy math that inflates expectations.
It is losing money, by design, at scale. Anduril is reportedly projecting an operating loss of around $1.2 billion in 2026, driven by heavy upfront R&D and the cost of building Arsenal-1. The self-funded model that produces 40 to 50% gross margins also requires enormous capital outlays before the revenue shows up. The whole thesis depends on hyperscale manufacturing working at a scale no defense startup has ever achieved. If Arsenal-1 stumbles, the math gets ugly fast.
Founder dependence is real. Palmer Luckey’s brand attracts capital and contracts, but it is also a single point of failure and a magnet for controversy. Investors should ask whether Anduril can outgrow its founder’s mythos.
None of this means the model is broken. It means the valuation is pricing in near-flawless execution of an unproven manufacturing bet, in a market with exactly one customer. That is a lot of conviction to underwrite.
Quick Questions
How does Anduril make money?
By self-funding R&D, building autonomous defense systems and AI software upfront, and selling them to the US military and allies at firm-fixed prices. The recurring margin comes from Lattice, its software platform, sold with ongoing “phasing as a service” updates.
Why is Anduril different from Lockheed or Boeing?
The traditional primes work on cost-plus contracts, billing for time and materials plus a fixed margin, which rewards slow and expensive. Anduril sells finished products and keeps the savings when it moves faster, producing far higher margins.
What is Lattice?
Lattice is Anduril’s AI operating system. It fuses data from every sensor and autonomous system into one real-time command-and-control picture, and it is the source of the company’s recurring, software-like revenue and customer lock-in.
How much is Anduril worth?
About $61 billion as of May 2026, after a $5 billion funding round led by Thrive Capital and Andreessen Horowitz. That makes it America’s most valuable private defense technology company.
The Business Model Analyst Take
Anduril’s genius is not its drones. It is the recognition that “how you get paid” was the root of the defense industry’s dysfunction, and the willingness to rebuild the business model from that insight outward. By self-funding R&D and selling finished products, Anduril aligned its incentives with the customer’s, collapsed timelines from years to months, and earned software margins on hardware. Lattice turned a product company into a platform company, where every new system makes the network more valuable and harder to leave.
The lesson for founders is portable far beyond defense: in slow, regulated, incumbent-heavy industries, the durable edge is rarely a better product. It is a better business model. Anduril found an arbitrage between Silicon Valley’s tempo and the Pentagon’s, and it is monetizing the gap.
The open question is whether the model survives contact with its own ambition. A $61 billion valuation on a company posting a billion-dollar-plus operating loss, betting everything on a gigafactory that has never been built at this scale, serving one customer whose priorities can change overnight, is a high-wire act. The upside is enormous and the moats are real. But the same vertical integration and self-funding that produce the margins also concentrate the risk. Anduril rewrote the rules of defense contracting. Now it has to prove it can manufacture at the scale its valuation already assumes.