Allstate runs three sales forces against the same customer. Score its strengths and weaknesses from the wrong one and you get the wrong answer.
Every other large US personal lines carrier picked a distribution model and lived with it. State Farm built a captive agent force and kept it. GEICO went direct and skipped agents. Progressive runs agency and direct together and refuses to call it a conflict. Allstate runs exclusive agents, independent agents and a direct operation at full scale at the same time, plus a fourth channel embedded inside 30-odd national retailers, and it has spent seven years shifting weight between them.
That makes a company-level SWOT close to useless on its own. Allstate’s record advertising budget is a strength for the direct operation and a threat to the exclusive agent who sells the same policy at the same price. The 58,700 independent agent doors are the broadest shelf space in the industry and the least productive per door. The homeowners product that anchors the whole bundle is growing fastest in the channel with no agent in it. Almost nothing in this SWOT holds a single sign.
One quadrant does resolve at company level, and it is the reason Allstate can afford the argument at all: the balance sheet.
SWOT analysis sorts a business into four categories. Strengths and weaknesses are internal, meaning management controls them. Opportunities and threats are external, meaning management can only react. The framework assumes the company is one unit. When a business runs several distribution models that compete for the same customer, the four buckets have to be scored per channel first and only then added up. Allstate is the clearest case in US insurance.
Allstate At a Glance
| Measure | Latest figure |
|---|---|
| Total revenues, FY2025 | $67,685 million |
| Net income to common, FY2025 | $10,165 million ($38.06 per diluted share) |
| Property-Liability combined ratio, FY2025 | 85.2 |
| Property-Liability combined ratio, H1 2026 | 84.3 |
| Auto insurance premiums written, Q2 2026 | $9,572 million, up 0.4% |
| Homeowners premiums written, Q2 2026 | $4,752 million, up 8.1% |
| Total policies in force | 215.9 million, up 3.8% |
| Property-Liability policies in force | 38.9 million, up 2.6% |
| Adjusted net income return on equity, trailing 12 months | 44.2% |
| Book value per common share | $123.38, up 49.7% year over year |
| Advertising spend | $638M (2023), $1,863M (2024), $2,100M (2025), $1,068M (H1 2026) |
| US private passenger auto market share, 2025 | 10.15%, fourth largest |
| US homeowners multiple peril market share | 9.42% |
| Distribution | 27,400 exclusive agents and licensed sales professionals, 58,700 independent agent locations, 2,200 direct sales representatives, 500 retail stores |
| CEO | Tom Wilson, chief executive since January 2007 |
The SWOT Matrix
| Strengths | Weaknesses |
|---|---|
| Ten-year homeowners combined ratio of 92.0 against an industry 102.2 | Auto premium written grew 0.2% in the first half of 2026 |
| $8.5 billion of Property-Liability underwriting income in 2025, up 177% | Auto underwriting margin depends on prior year reserve releases |
| Broadest distribution in US personal lines by door count | The independent channel produces one third the auto output per door |
| 44.2% adjusted return on equity and $9.5 billion of deployable holding company capital | Protection Services earnings fell in the first half while its policy count grew |
| Protection Plans embedded in retailers with $1.3 trillion of combined US sales | Cost per new application has roughly doubled since 2023 |
| Opportunities | Threats |
|---|---|
| Custom360 gives independent agents a middle market product, now in 41 states | Progressive and GEICO are both cutting rates into the same shopping cycle |
| Direct homeowners new business grew more than fourfold in three years | Reserve releases run out and the recorded ratio converges on the underlying one |
| ALLIE, the AI ecosystem Wilson says will cut distribution expense | Homeowners carries 29.3 points of catastrophe load and is the growth engine |
| Arity holds over two trillion miles of driving data and sells third party leads | The exclusive channel shrinks faster than the direct channel replaces it |
| Independent agents now place 39.5% of US personal lines premiums | Wilson has run the company for 19 years with no announced successor |
Strengths
Homeowners is the franchise, and it has been for a decade
Read the ten-year record in Allstate’s own second quarter deck. On an earned premium weighted basis from 2016 through 2025, Allstate’s homeowners combined ratio was 92.0 against an industry figure of 102.2. Auto came in at 95.2 against 100.3. A ten-point advantage in a line that most of the industry loses money on is the single hardest thing in this SWOT to argue with.
The 2026 numbers show why it matters now. Homeowners written premium grew 8.1% in the second quarter while auto grew 0.4%. Homeowners earned premium grew 11.4% against auto’s 1.2%. Underwriting income in homeowners swung from a $76 million loss to a $226 million profit. Allstate carries about 9.42% of the US homeowners multiple peril market on $17.766 billion of direct premium written, a position no publicly traded competitor comes close to.
The underlying homeowners combined ratio of 61.0 for the first half is the number to hold onto. Before catastrophes, Allstate keeps 39 cents of every homeowners premium dollar. Catastrophes take most of it back, which is the trade, and Allstate has been managing that trade longer than anyone else in the peer group.
Property-Liability earnings that fund everything else
The 2025 result was the best in Allstate’s history: $10,165 million of net income to common, $8.5 billion of Property-Liability underwriting income, a 85.2 combined ratio after a 9.1 point improvement. The first half of 2026 ran a 84.3 combined ratio and $4,664 million of underwriting income. Trailing twelve month adjusted return on equity reached 44.2%.
Capital follows. Allstate returned $3.5 billion to shareholders over the last year, about 6.7% of its market capitalization. It repurchased $1.0 billion of stock in the second quarter alone, with $2.6 billion left on a $4 billion authorization. Deployable capital at the holding company sits at $9.5 billion, roughly $37 per share. Book value per common share reached $123.38, up 49.7% in a year.
The long arc is starker than the quarter. Of 900 million shares Allstate has issued, 646 million sit in treasury. The company has bought back 39% of its outstanding shares in the last decade and returned cash equal in value to its entire 2015 market capitalization. Whatever the channel argument does to the operating business, the capital account has been resolved in shareholders’ favor for ten years.
Four distribution channels, and a fourth that nobody counts
Allstate’s 2025 Form 10-K lists over 27,400 exclusive agents and licensed sales professionals, approximately 58,700 independent agent locations, approximately 2,200 direct sales representatives in contact centers and online, and roughly 500 retail stores selling Direct Auto. Brands include Allstate, National General, Direct Auto, Answer Financial, Esurance and Encompass.
Then there is the channel that does not appear in the distribution table. Allstate Protection Plans sits inside more than 30 large retailers that generate $1.3 trillion in combined US annual sales. Allstate Dealer Services partners with about 1,100 dealerships reaching over 1.75 million customers a year. Neither runs through an agent, a call center or an Allstate website.
Weaknesses
The independent channel has the most doors and the least output
Allstate’s deck calls its network the broadest distribution in the industry. By door count it is. By production per door it is not, and the gap is not close.

In the second quarter of 2026 Allstate wrote 2,347 thousand new auto applications and 411 thousand new homeowners applications. Applying the channel shares Allstate published alongside those totals, and dividing by the distribution counts in the 10-K, gives 29.1 new auto applications per exclusive agent or licensed sales professional and 12.8 per independent agent location. In homeowners the same arithmetic gives 9.5 against 1.1.
The independent channel has 2.1 times as many doors and produces about one third the auto output and one ninth the homeowners output per door. Some of that is structural: an independent agency also represents competing carriers and places business where the price wins that week. That is the point. Shelf space in an independent agency is an option the agent exercises, not distribution Allstate owns. Progressive discovered the same thing from the other side, which is why its own SWOT analysis turns on how many carriers now return a quote on the same comparative rater.
Auto premium has stopped growing
Auto written premium grew 0.4% in the second quarter and 0.2% for the first half. Policies in force grew 2.8%. Average premium per auto policy fell to $1,486 from $1,492. Allstate implemented rate changes in 36 states during the quarter with a net neutral overall impact, a mix of increases and decreases.
Allstate presents this as affordability, and it is a deliberate choice rather than a failure to raise price. The cost of the choice shows up per policy. Against that $1,486 of annualized premium, the adjusted underlying loss and expense per policy runs $1,337. The margin is $149 a policy, and the loss and expense line has been rising while the premium line falls.
The reported auto margin and the current auto margin point in opposite directions
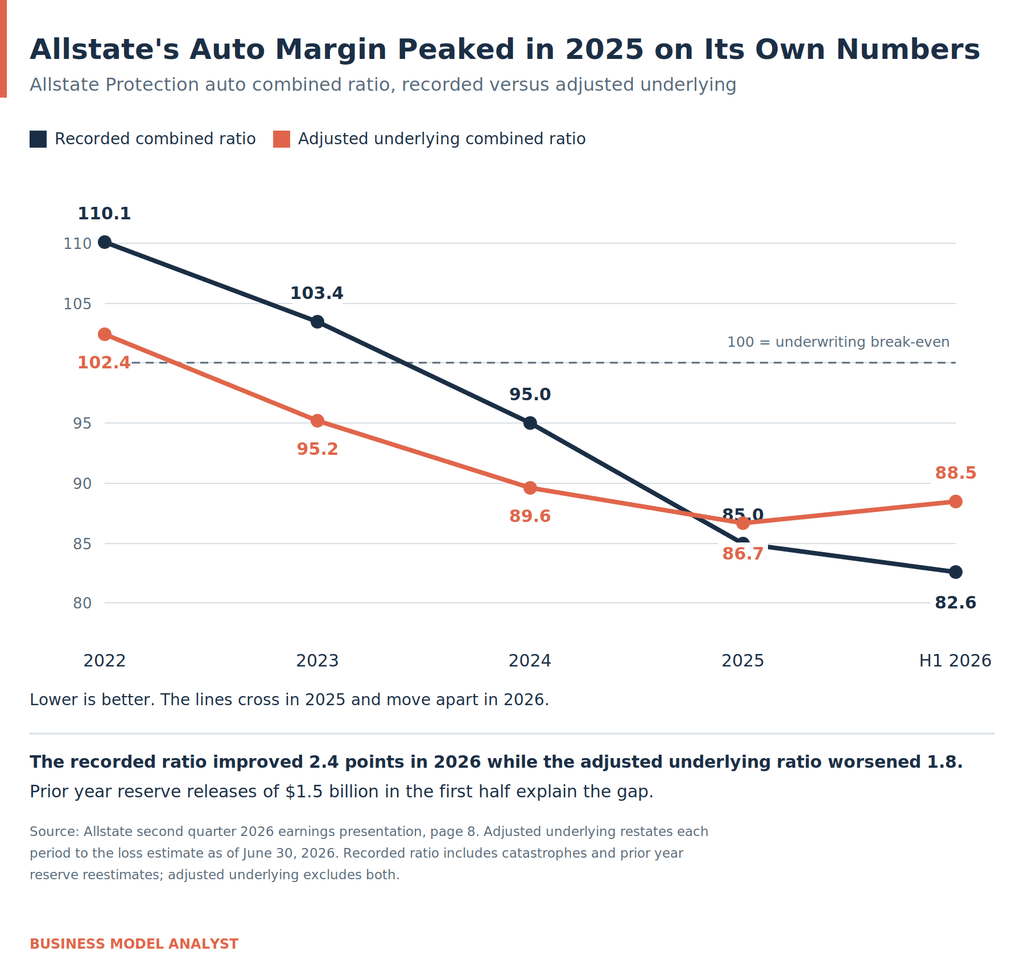
Allstate publishes an adjusted underlying combined ratio that restates every period to the loss estimate as of the latest balance sheet date. It is the cleanest run rate the company produces. Put it next to the recorded ratio and the two series separate in 2026.

Recorded auto combined ratio: 85.0 in 2025, 82.6 in the first half of 2026, an improvement of 2.4 points. Adjusted underlying: 86.7 in 2025, 88.5 in the first half of 2026, a deterioration of 1.8 points. The second quarter alone ran an adjusted underlying 90.0.
The difference is reserves. Allstate released $1.5 billion of prior year auto reserves in the first half of 2026, $1.3 billion of it on injury coverages, with about 51% relating to accident years 2023 and 2024 and 30% to 2025. Prior year reestimates excluding catastrophes added 7.7 points to the first half auto combined ratio. On $19,191 million of auto earned premium, those 7.7 points are worth roughly $1,478 million, which is about 44% of the $3,335 million of auto underwriting income Allstate booked in the half.
None of that is improper. Reserves get released when claims settle better than assumed, and Allstate’s disclosure here is more generous than most of the industry. The Progressive numbers run the same direction for the same reason, which we covered separately. The Allstate specific problem is that the released years are running out, and the run rate underneath them is moving the wrong way.
The headline policy count measures something other than insurance
Allstate leads with 216 million policies in force. Protection Services holds 177 million of them.
Protection Services generated $3.4 billion of revenue and $203 million of adjusted net income over the trailing twelve months. Against total trailing adjusted net income of $11,891 million, that is 1.7% of the earnings on 81.8% of the policies. The segment also went backwards in the first half: adjusted net income of $100 million against $115 million a year earlier, with Protection Plans down $13 million on weaker margins in major appliances, and Arity running a $19 million loss.
A phone screen protection plan is a real product with a real customer. It is not equivalent to a homeowners policy, and quoting the two in the same total flatters the growth rate.
Opportunities
The bundle is being rebuilt in the direct channel
The sharpest three-year comparison in Allstate’s own materials is one it does not state as a percentage.

Between the second quarter of 2023 and the second quarter of 2026, direct homeowners applications rose from roughly 19,600 to roughly 86,300 a quarter, a gain of about 340%. Direct auto applications nearly doubled. The exclusive channel grew in both lines but slower, and independent agents added 11.9% in homeowners against 54.0% in auto.
Homeowners is the product that historically justified the exclusive agent office. It is complicated, it needs advice, and it is what keeps a household from shopping its auto policy every six months, which is the same logic behind Progressive’s own segment ladder. Allstate has now proved it can sell that product without an agent, and the direct channel’s share of homeowners new business went from 7% to 21% in three years. Every incremental point of that is a strength for the company and a subtraction from the agent’s case for existing.
Custom360 and the independent agent shelf
Independent agents placed 39.5% of all US personal lines premiums in 2025, their fourth consecutive annual gain. Allstate’s answer is Custom360, a middle market standard and preferred auto and homeowners product built for that channel, live in 41 states as of the second quarter, up from 36 at the end of 2025.
The homeowners per-door number above is the size of the prize. If Allstate can move independent agent homeowners production from 1.1 applications per location per quarter to anything close to what those agents already do in auto, the shelf becomes worth what the door count implies.
ALLIE, and what Wilson says it is for
Allstate is building ALLIE, its Large Language Intelligent Ecosystem, on a base of more than 250 significant models, 40 petabytes of data and 1.5 billion CPU hours. The company prices over 100 million pieces of business, buys 50 million sales leads and manages over 400 million service interactions a year.
Wilson was direct about the first target on the second quarter call. Jesse Merten, he said, already has work underway to take work out of agent offices, which will reduce distribution expense. Read that from the shareholder’s chair and it is margin. Read it from the agent’s chair and it is the plan.
Threats
The cycle turns while the growth engine is already flat
Auto rates across the market are coming down. Progressive told investors in August that it had cut new business rates in 30 states covering 63% of its premium through the first half of 2026, while raising advertising 16%. GEICO’s own average written premium per auto policy is falling. Allstate went net neutral on rate across 36 states in the second quarter. All four of the largest carriers are competing for the same shopping households at the same time, and Allstate enters that fight with auto premium growing 0.2%.
Its response has been to buy volume. Advertising went from $638 million in 2023 to $1,863 million in 2024 to $2,100 million in 2025, with $1,068 million spent in the first half of 2026. Auto and homeowners new applications rose from about 1,758 thousand in the second quarter of 2023 to about 2,758 thousand in the second quarter of 2026, a gain of 56.9%.
Set annualized spend against annualized applications and the cost of a new issued application moved from roughly $91 in 2023 to roughly $194 in 2026. That comparison is rough, since 2023 was a year Allstate deliberately suppressed advertising while non-renewing policies, and applications are seasonal. The direction is not in doubt, and Allstate’s own slide describes advertising as increasing because advances across the consumer acquisition engine improve economics. The unit cost of an application is not the metric that supports that claim.
Note also what Allstate excludes when it reports expense discipline. Its adjusted underwriting expense ratio is defined to strip out advertising expense, on the stated grounds that advertising varies from period to period based on business decisions. The line that tripled sits outside the ratio the company uses to show the line is under control.
Catastrophe exposure sits in the line that is growing
Homeowners took $1,408 million of catastrophe losses in the second quarter, 33.5 points of combined ratio, and $2,454 million in the first half. Full year 2025 catastrophes came to about $5 billion across the book. The homeowners underlying combined ratio also moved the wrong way in the quarter, up 2.9 points to 61.5 on higher loss costs.
Allstate is deliberately growing the line with the fattest tail. That is a defensible trade at a 61 underlying ratio. It is still the trade.
The exclusive channel is shrinking, and Allstate stopped showing the number
Compare the distribution disclosure across three filings. The 2019 Form 10-K reported 10,800 exclusive agencies in 10,700 locations supported by 27,100 licensed sales professionals. The 2021 filing reported 9,300 exclusive agents in 9,400 locations supported by 21,700 licensed sales professionals. The 2025 filing reports a single merged figure: over 27,400 Allstate exclusive agents and licensed sales professionals.
Agents and professionals combined ran about 37,900 in 2019 and 31,000 in 2021. The 2025 combined figure is 27,400, down roughly 28% from 2019 on a basis that has itself changed. The count of exclusive agencies, the number that would show how much of the network is left, is no longer disclosed at all.
Meanwhile the channels Allstate is adding to keep growing. National General reached over 43,000 independent agent locations in 2021 and the 2025 total is 58,700. The direct operation has 2,200 representatives and takes a third of new auto business.
Nineteen years of one CEO and one plan
Wilson has been chief executive since January 2007 and chairman since May 2008. Transformative Growth is his strategy, announced in December 2019 and now in its seventh year, with the technology rollout phase still ahead of it. Allstate has published no successor. The plan and the person who owns it are the same asset, and the company has not shown what happens if one of them leaves before the other finishes.
What the SWOT Adds Up To
Take the four largest items in this analysis and score each one twice.
| Fact | From the company’s chair | From the exclusive agent’s chair |
|---|---|---|
| Advertising at $2.1 billion a year | Buys new business across all channels | Sends the customer to a call center at the same price |
| Direct homeowners up more than fourfold | Proves the bundle sells without an agent | Removes the reason to keep an office |
| ALLIE cutting distribution expense | Margin | Wilson said it out loud on the call |
| 58,700 independent agent doors | Broadest distribution in the industry | 58,700 competitors who also sell Allstate |
None of those four resolves at the company level. Each is a strength somewhere and a weakness somewhere else, and which one it is depends entirely on where the reader is standing.
What does resolve is the balance sheet. A 44.2% return on equity, $9.5 billion of deployable holding company capital, a book value per share up 49.7%, and 39% of the shares retired in a decade. That capital position is what lets Allstate run an internal argument between three sales forces for seven years without being forced to settle it.
The settlement is coming anyway, and the auto book sets the clock. Once the 2023 and 2024 reserve releases are spent, the recorded combined ratio converges on the adjusted underlying one, which is currently going the wrong way. At that point Allstate has to grow auto premium rather than manage it flat, and it will have to choose which sales force does the growing. State Farm is answering that question by rewriting the contract under 19,000 agents. Allstate is answering it by building the direct channel until the answer becomes obvious.
Frequently Asked Questions
What are Allstate’s biggest strengths? Homeowners underwriting and capital generation. Over the decade to 2025, Allstate’s homeowners combined ratio averaged 92.0 against an industry 102.2, and its auto book averaged 95.2 against 100.3. In 2025 the company earned $10.2 billion of net income and $8.5 billion of Property-Liability underwriting income, and it has repurchased 39% of its outstanding shares over the last ten years.
What is Allstate’s biggest weakness? Auto premium growth. Written premium in auto grew 0.4% in the second quarter of 2026 and 0.2% for the half, with average premium per policy falling to $1,486. The recorded auto combined ratio looks strong at 82.6 for the half, but 7.7 points of that came from releasing prior year reserves. On Allstate’s own adjusted underlying basis the auto book ran 88.5 in the half and 90.0 in the second quarter, worse than the 86.7 it ran in 2025.
Is Transformative Growth working? By its stated objective, yes. Property-Liability policies in force grew 2.6% year over year, auto new business rose 8.8% in the second quarter and homeowners new business 16.4%, and Allstate says it is gaining share in most states. The cost is visible too: advertising tripled between 2023 and 2025, and the exclusive agent headcount has fallen roughly 28% since 2019.
How does Allstate compare with Progressive, State Farm and GEICO? Allstate is fourth in US private passenger auto with 10.15% share on 2025 NAIC data, behind State Farm at 18.64%, Progressive at 18.60% and GEICO at 11.56%. Note that the top of that table is contested: Progressive management describes itself as the largest US personal auto writer, and S&P Global Market Intelligence shows it ahead on a trailing twelve month basis through March 31, 2026, while conceding that its figure includes estimates for two New Jersey subsidiaries that file no public quarterly statements and that published data still shows State Farm slightly ahead. Allstate’s distinguishing feature is not size. It is that it runs State Farm’s distribution model, Progressive’s and GEICO’s at the same time.
What are the biggest threats to Allstate? Rate competition arriving while auto premium is flat, catastrophe exposure concentrated in the line Allstate is growing fastest, the end of the reserve release runway, and a distribution transition that is removing exclusive agents faster than the direct channel is currently replacing their homeowners production.
Why does Allstate say it has 216 million policies? Because Protection Services holds 177 million of them, mostly device and appliance protection plans sold through retailers. That segment produced $203 million of adjusted net income over the trailing twelve months, about 1.7% of Allstate’s total. The Property-Liability book, which is the insurance company, holds 38.9 million policies.
Is Allstate still a captive agent company? Only in part. Exclusive agents wrote 34% of new auto applications in the second quarter of 2026, down from 39% three years earlier, and 63% of new homeowners applications, down from 72%. The direct channel took 34% of new auto and 21% of new homeowners business. Allstate also distributes through approximately 58,700 independent agent locations, more than double its exclusive headcount, though those locations produce far less Allstate business per door.
The Business Model Analyst Take
Allstate is the only carrier in US personal lines that has to answer the distribution question twice a quarter, and the honest reading of its SWOT is that management has already picked a side and has not said so.
The evidence is in the homeowners numbers. Direct homeowners new business grew more than fourfold in three years while the exclusive channel’s share of that line fell nine points and independent agents added under 12%. Homeowners is the product that made an agent office worth visiting. Allstate now sells it four times better without one, and the CEO described the AI program as a way to take work out of agent offices and reduce distribution expense. Nobody builds a machine to remove work from a channel they intend to expand.
That is defensible. It may be correct. The risk is timing, and the timing is set by the auto book rather than by the agents. Allstate is running a 44.2% return on equity on a recorded auto combined ratio that leans on $1.5 billion of prior year reserve releases, while the adjusted underlying ratio it publishes itself has turned back up. When those releases stop, the reported result drops toward the run rate and the flat premium line becomes the whole story. Allstate will need to grow auto quickly at exactly the moment the market is discounting, with an exclusive force 28% smaller than in 2019, a marketing budget that costs about twice as much per new application as it did in 2023, and 58,700 independent doors that produce one auto application a week each.
The balance sheet buys time for that, and Allstate has more of it than the peer group assumes: $9.5 billion of deployable capital, a book value up 49.7%, and a ten-year homeowners record no competitor can match. Time is not the same as an answer. Progressive settled its channel question by refusing to treat it as one. State Farm is settling its by rewriting 19,000 contracts. Allstate is settling its by quietly starving one channel while the other two grow, which works until the quarter someone needs the starved channel to sell something.