
Airwallex has raised $320 million in Series H funding at an $11 billion valuation, a 38% jump in just six months, and used the announcement to reframe itself from a cross-border payments company into the financial operating system for an economy run by AI agents. The round was led by returning investor Addition, with Lee Fixel’s firm doubling down on a thesis the company is now putting at the center of its pitch: in agentic commerce, the winners own the licenses and rails, not the interface on top of them.
The Deal at a Glance
| Detail | Figure |
|---|---|
| Round | Series H |
| Amount raised | $320 million |
| Post-money valuation | $11 billion |
| Previous valuation | $8 billion (December 2025) |
| Valuation increase | +38% in six months |
| Lead investor | Addition (Lee Fixel) |
| Annualized revenue (March 2026) | $1.3 billion, up 74% YoY |
| Annualized transaction volume | $287 billion, up 120%+ YoY |
| Businesses served | 676,000+ |
| Licenses held | 85+ across 4 regions |
What Airwallex Just Raised and From Whom
The $320 million Series H was led by Addition, the New York firm that also led the company’s $330 million Series G in December 2025. Participating investors include Baillie Gifford, Hummingbird, QED Investors, T. Rowe Price, Hedosophia, Haun Ventures, Washington University in St. Louis, and Amex Ventures.
The investor mix is the tell. Baillie Gifford and T. Rowe Price are crossover funds that typically anchor pre-IPO and public-market positions, not early venture. Their presence alongside fintech specialists like QED and crypto-native Haun Ventures signals a round built to fund a late-stage growth phase while keeping the public-market door open for later. Amex Ventures adds a strategic incumbent to the cap table at the exact moment Airwallex is pushing deeper into corporate spend and finance automation.
The Numbers Behind the $11 Billion Price Tag
The valuation rests on a genuinely steep growth curve. As of March 2026, Airwallex reported $1.3 billion in annualized revenue, up 74% year over year, and $287 billion in annualized transaction volume, up more than 120%. More than 90% of revenue now comes from customers using more than one product, which is the metric investors care about most: it shows the company is selling a platform, not a single payments feature.
That cross-sell density is what justifies an $11 billion mark on roughly $1.3 billion of revenue, a multiple of about 8.5x annualized revenue. For a profitable, fast-growing infrastructure business with multi-product lock-in, that is aggressive but defensible. For a single-product payments processor, it would not be.
Why the Valuation Jumped 38% in Six Months
Airwallex has now repriced three times in roughly a year:
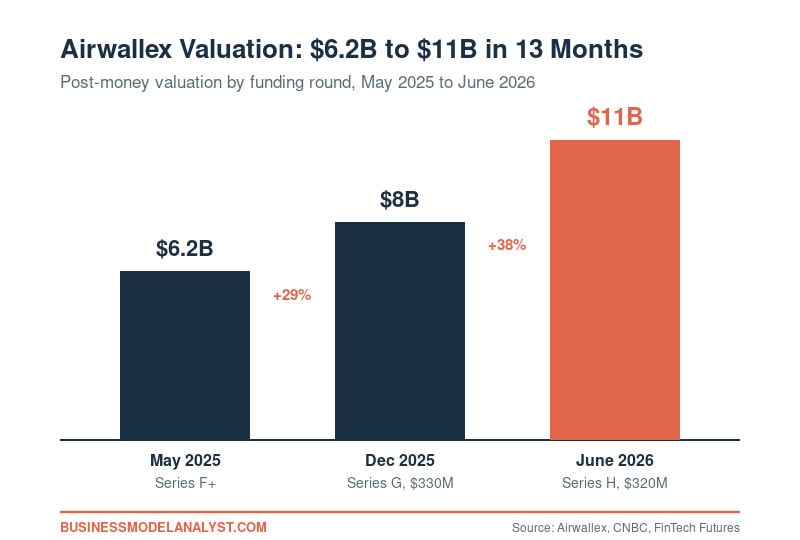
The jump is not just growth. It is narrative. Six months ago Airwallex was a borderless-payments story. Today it is an agentic-finance story, and the AI framing is doing real work on the multiple. Addition’s Lee Fixel made the case explicitly: the durable advantage in an AI-driven landscape goes to companies building on top of real financial infrastructure rather than around it. That is a direct shot at AI-native fintech startups trying to wrap agent workflows around someone else’s rails.
The Bet: Autonomous Finance and Agentic Commerce
Alongside the raise, Airwallex announced two products that define its next chapter:
T:0 (“Time Zero”) is an AI-native platform meant to run a company’s entire finance function end to end, automating bookkeeping, forecasting, taxes, compliance, and reporting from day one with no migration required. It is in private beta. The pitch is CFO-grade books for founders who have no finance team. To support it, Airwallex also acquired Leapfin, a revenue-recognition and reconciliation platform that turns raw transaction data into GAAP-ready financials.
Airi is an agentic consumer wallet built to let AI agents make payments inside defined permission and spending controls, with multi-currency balances and delegated-agent payments. It folds in Airwallex’s existing one-click checkout, which the company says lifted successful checkout conversion by up to 14% for digital merchants in early testing.
The strategic logic is clean: if AI agents are going to research, negotiate, and pay autonomously, someone has to hold the licenses, KYC the agents, and settle the money. Airwallex is arguing that its decade of regulatory grunt work, 85+ licenses, 160 local payment network integrations, and payout reach to 200+ countries, is precisely the boring infrastructure the agentic economy will run on.
How Airwallex Stacks Up Against Stripe and the Field
Airwallex sits in a crowded field, but it is carving out a specific lane: the cross-border, multi-currency, all-in-one financial OS for global businesses.
| Company | Approx. valuation | Core focus |
|---|---|---|
| Stripe | ~$70 billion | Developer-first payments infrastructure |
| Airwallex | $11 billion | Cross-border payments + financial OS |
| Ramp / Brex | Private | Corporate spend and finance automation |
| Wise | Public (LSE) | Cross-border transfers |
The competitive irony is hard to miss. Co-founder and CEO Jack Zhang reportedly turned down a $1.2 billion acquisition offer from Stripe years ago. Now he is positioning Airwallex against Stripe on the one axis where Stripe is weakest: native multi-currency, multi-jurisdiction infrastructure built from the ground up rather than bolted on. For more on where Airwallex fits among payment players, see our breakdown of the top PayPal competitors and the highest-valued unicorns of 2026.
The China Question and Regulatory Overhang
The bull case has a real shadow. Airwallex was founded in Melbourne, is now co-headquartered in San Francisco and Singapore, and still operates offices in Shanghai, Beijing, and Shenzhen. Its backers include Tencent, which has held a stake of roughly 12.5%, and HongShan Capital, the firm formerly known as Sequoia China.
That footprint has drawn fire. In December 2025, prominent investor Keith Rabois, a board member at rival Ramp, called Airwallex a “Chinese backdoor into sensitive American data.” Zhang dismissed the claim as a conspiracy theory and said US customer data is stored in the US and inaccessible to staff in China or Hong Kong, and the company has reportedly relocated some Hong Kong and Shanghai staff to comply with US data-transfer rules. Separately, Australian regulator AUSTRAC ordered an external auditor in early 2026 to assess the company’s anti-money-laundering compliance. None of this is fatal, but it is exactly the kind of risk that follows a company into a public-market roadshow.
The IPO That Keeps Drifting
For years, Airwallex has been described as IPO-bound. Zhang has consistently pushed back, and this round gives him cover to keep doing so. He told the Australian Financial Review that heavy AI investment has made the company’s margins “too volatile to go public,” and has separately suggested a listing is unlikely before 2028.
This is the strategically interesting part. Staying private lets Airwallex spend aggressively on AI without quarterly-margin scrutiny, exactly when its competitors are doing the same. The fresh $320 million plus crossover investors who can hold through a long private runway is the financial structure of a company that wants the option to IPO without the pressure to. “IPO-ready” and “IPO-bound” remain two very different things.
What This Means for Founders and Operators
Three transferable lessons sit inside this round:
- Owning the rails beats renting them. Airwallex’s multiple is being driven by the fact that it controls licenses and settlement infrastructure others must build on top of. When a new category emerges (here, agentic commerce), the regulated layer underneath captures durable value.
- Multi-product attach is the real moat. The 90%+ multi-product revenue figure is what turns a payments company into a platform and unlocks an infrastructure multiple. Cross-sell density, not raw growth, is what investors are paying for.
- Narrative repricing is real but fragile. A large slice of the 38% bump is the shift from a payments story to an AI story. That works while the growth backs it up. The moment growth slows, an AI narrative inflates the downside as fast as it inflated the upside.
The Business Model Analyst Take
Airwallex is making the single most defensible bet available to a fintech in 2026: that the agentic economy will need regulated, multi-currency money movement, and that the company holding the licenses wins. The infrastructure thesis is sound, the growth is real, and the multi-product revenue is the kind of metric that justifies the price.
The risk is that Airwallex is now telling two stories at once. The first is a boring, profitable, compounding payments-infrastructure business. The second is an AI-native autonomous-finance moonshot with T:0 and Airi still in beta. Investors are paying for the second while relying on the first to hold up the valuation. That works beautifully until growth decelerates or the China and AML overhang forces a discount, at which point the AI premium becomes the AI penalty. Layer on a CEO who keeps the IPO permanently two years away, and you have a company with extraordinary fundamentals and an unusually large gap between what it is today and what it is being valued as. The fundamentals earn the benefit of the doubt. The narrative is the part to watch.
FAQ
How much did Airwallex raise and at what valuation?
Airwallex raised $320 million in a Series H round at an $11 billion valuation, up from $8 billion in December 2025.
Who led the Airwallex Series H round?
The round was led by returning investor Addition, with participation from Baillie Gifford, T. Rowe Price, QED Investors, Hummingbird, Hedosophia, Haun Ventures, Washington University in St. Louis, and Amex Ventures.
How much revenue does Airwallex make?
As of March 2026, Airwallex reported $1.3 billion in annualized revenue, up 74% year over year, on $287 billion in annualized transaction volume.
Is Airwallex going public?
Not soon. CEO Jack Zhang has said an IPO is unlikely before 2028 and that AI-driven investment has made the company’s margins too volatile to list.
What are T:0 and Airi?
T:0 is an AI-native platform that automates a company’s full finance function, and Airi is an agentic consumer wallet that lets AI agents make payments within set controls. Both are early-stage.