
Bending Spoons is paying $1.285 billion for a business growing more than 20% a year at roughly 90% gross margins. Venture equity could not hold that asset. A leveraged compounder can.
Silicon Valley is calling it the SaaSpocalypse, and the Airtable sale is being read as the body count. The deal terms say something narrower and more useful: Airtable works. It grew. It generates cash. What broke was the match between the company and the people who owned it.
Sahil Aggarwal, whose startup Rattle raised close to $30 million before he cut it from 70 employees to 15 and relaunched as Von, told the Wall Street Journal that if two engineers can rebuild your product in a few weeks, you deserve to be killed. It is a good line. It does not describe Airtable, which has 500,000 organizations on the platform and 80% of the Fortune 100. Two engineers are not rebuilding that in a few weeks. Airtable still sold at roughly half the going rate for a private software company in 2026.
What Happened
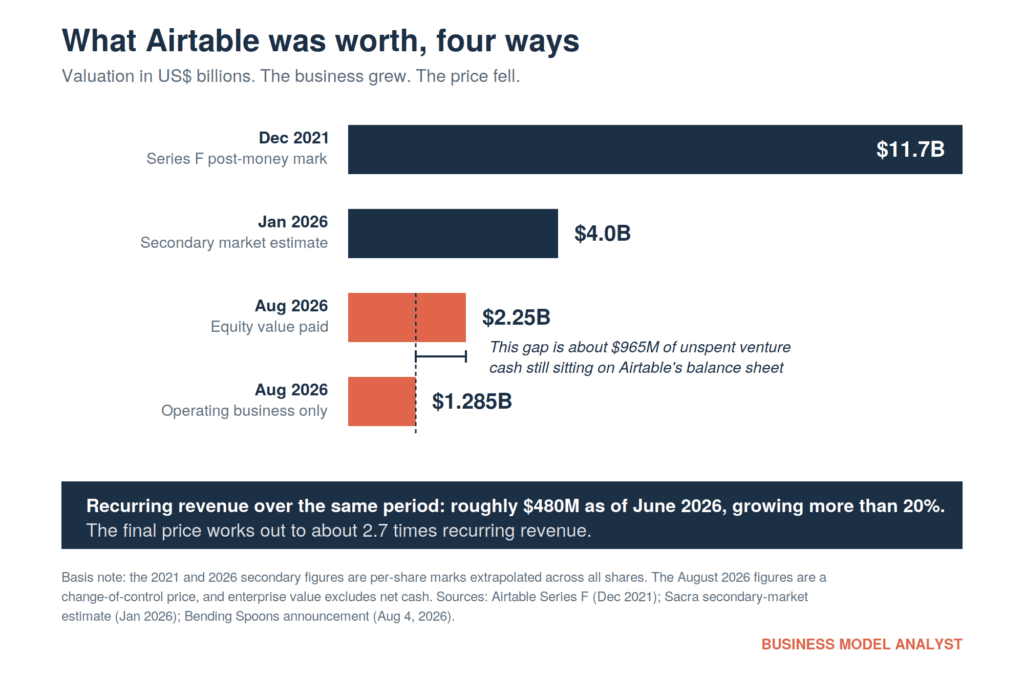
On August 4, 2026, Bending Spoons signed a definitive agreement to buy Airtable at an enterprise value of $1.285 billion. Add Airtable’s cash balance and the implied equity value comes to about $2.25 billion. Both boards approved it. The companies expect to close before year end, pending regulatory review.
Bending Spoons put Airtable’s recurring revenue at roughly $480 million as of June 2026, growing more than 20% year over year. That works out to about 2.7 times recurring revenue for the operating business.
Set that against the comparable set. Aventis Advisors puts the median private software M&A exit near 4.5 times revenue across the last decade, with the top quartile above 8.1 times. SaaS Capital’s data lands around 5.3 times for venture-backed sellers. Public software companies entered 2026 near 6 to 7 times enterprise value to revenue. Airtable cleared at 2.7.
The gap between the equity value and the enterprise value is the part worth staring at. About $965 million separates them, which is net cash sitting on Airtable’s balance sheet. Airtable raised roughly $1.4 billion across seven rounds. Close to 70% of that money never left the building. The buyer writes a check for $2.25 billion and gets $965 million of it back on day one.
That is the actual epitaph for a large slice of the 2021 cohort. These companies did not burn to death. They ran out of things worth spending money on at a return that justified spending it, and the capital sat there.
The Backstory
Airtable raised $735 million in December 2021 at an $11.7 billion post-money valuation, led by XN, with Franklin Templeton, Silver Lake, Salesforce Ventures, MSD Capital and T. Rowe Price joining. The price per share was $187.28. Nine months earlier the company had raised at $5.77 billion. Eighteen months before that, $2.6 billion.
By January 2026, buyers on the secondary market were marking Airtable around $4 billion. The August deal implies roughly $36 a share. Series F investors are recovering about 19 cents on the dollar.
Notice that the secondary market was still wrong by a wide margin. Traders had already cut Airtable by two thirds from its peak and were still pricing it at 78% above what an actual control buyer would pay. Private marks and clearing prices are different objects, and the distance between them only becomes visible when someone signs.
There is a second measurement problem here worth naming. Sacra points out that Airtable never disclosed recurring revenue as a private company, so every ARR figure circulating on aggregator sites has been a third-party estimate. Some of those trackers had Airtable at $478 million back in 2024. Bending Spoons now reports roughly $480 million as of June 2026, growing more than 20%. Both cannot be right. The buyer’s number carries securities liability and the tracker’s number does not, so the buyer’s number wins, which means the estimates the venture asset class quietly marked itself against were running hot for years.
The term SaaSpocalypse has a datable origin, too. SaasRise traces the sell-off to Anthropic’s Claude Cowork launch on January 12, 2026, after which roughly $1 trillion in aggregate software market capitalization came off and public multiples compressed from around 7.0 to 5.5 times revenue. The WSJ reports Workday, Salesforce and Adobe all down more than 30% from their peaks over the past year, and IBM shedding $69 billion of market value in a single July session on a profit warning tied to customers moving budget from software to AI hardware.
The Plan
Bending Spoons does not run a product turnaround. It runs an arithmetic problem, and the F-1 tells you the arithmetic.
The company discloses that when it allocates acquisition financing, it assumes debt equal to the lower of two figures: 85% of the target’s enterprise value, or the maximum debt that the acquired business’s projected free cash flow can fully repay within five years. It also states a return hurdle of 25% or better on capital.
Run those assumptions against Airtable. Eighty-five percent of $1.285 billion is about $1.09 billion. Repaying that inside five years means roughly $218 million a year of free cash flow before you pay any interest, and Bending Spoons borrows at leveraged-loan pricing, with its largest dollar term loan carrying an all-in rate near 9.43%. Call it $260 million to $270 million a year of free cash flow required from a business with $480 million of recurring revenue.
Airtable runs about 90% gross margins, so gross profit on that revenue is around $432 million. To clear $260 million of free cash flow, total operating expense has to come down under roughly $170 million. Airtable employs around 947 people.
The company has not disclosed the financing for this specific deal, and the F-1 language describes an allocation convention used for illustrative return math rather than a per-deal debt commitment. But the model has a documented output. At Evernote, most of the roughly 250 US and Chile-based staff were gone within months of the 2023 close and the personal annual plan went from $69.99 to $129.99, an 86% increase. At WeTransfer, about 75% of staff left within weeks of closing in 2024, and the free tier was capped at 10 transfers a month. At Brightcove, more than 85% of roughly 200 employees went.
Howie Liu says the deal gives Airtable the resources and long-term commitment to build the AI-native platform of the future. The financing structure describes a different project.
The Business Model Angle
Venture equity and permanent capital are two different business models applied to the same underlying asset, and they produce different prices for identical cash flows.
A venture fund gets paid on the option value of a very large outcome. A $1.4 billion cost basis needs an exit measured in tens of billions to move a fund. Airtable at $2.25 billion returns something like 1.6 times gross across a decade, and no amount of 20% growth and 90% gross margin fixes that. Once an asset stops being able to produce a fund-returning outcome, that capital class cannot hold it, however healthy the business is. The board becomes a forced seller of a good company.
Permanent capital gets paid on margin. Bending Spoons borrows at 9.43%, cuts operating expense, raises prices, and never sells. Its filing names Henry Singleton of Teledyne and Mark Leonard of Constellation Software as the models. Fifty-plus acquisitions over 13 years and no material divestiture. Under those rules, 2.7 times revenue on a 90% gross margin business is not a discount. It is the number that clears the hurdle.
So the SaaS business model is not dying. Ownership of it is moving from capital that pays for growth to capital that pays for cash flow, and the second kind pays less. Bending Spoons says it has mapped more than 1,000 targets representing roughly $400 billion of aggregate annual revenue. That is the size of the transfer being queued up.
One number from the same WSJ story sharpens what the market is actually pricing. Salesforce agreed in June to buy Intercom’s Fin agent for $3.6 billion against roughly $400 million of recurring revenue, about nine times. Airtable, with more revenue, cleared at 2.7. Fin is a product carve-out rather than a whole company, which flatters the multiple, but the direction is unmistakable: buyers are paying a premium for revenue billed per outcome and a discount for revenue billed per seat. When an agent does the work, the seat count is the wrong meter.
The Risk
The compounder side of this trade has its own unresolved question, and the market has started asking it.
At March 31, 2026, Bending Spoons carried about $4.36 billion of debt against roughly $1.06 billion of shareholders’ equity. First-quarter interest expense of $93.2 million consumed 77.5% of $120.2 million in operating income, leaving $27.5 million of net income on $601 million of revenue. Most of the debt stack matures around March 2031, which concentrates refinancing risk into a single window. The credit agreements cap leverage at 4.0 times net debt to adjusted EBITDA, and adjusted EBITDA is a number the company constructs.
Look at what gets added back. Reorganization expense ran $13.5 million in 2023, $51.8 million in 2024, $78.6 million in 2025, then $75.8 million in the first quarter of 2026 alone. A cost that recurs every year and attaches to the core strategy is an operating expense, not a one-off. By 2025 the gap between GAAP net income and adjusted net income had reached roughly $376 million.
Growth is also mostly purchased. Bending Spoons grew revenue 95% in 2025, of which organic growth contributed 13 points. In the first quarter of 2026 organic growth came in at 6% and net revenue retention at 94%, meaning the existing portfolio shrinks a little each year and the acquisitions cover it. That model works while credit is available and targets are cheap. It gets tested when either changes.
And the bear case on Airtable deserves a fair hearing rather than a dismissal. The 2.7 multiple may not be a repricing artifact at all. Airtable launched Superagent in January 2026 and rebranded around AI, which is what a company does when it can see per-seat billing eroding underneath it. If agents genuinely compress the number of humans who need a workspace license, then a buyer who responds by cutting engineering and raising prices owns a melting asset financed with fixed obligations. Bending Spoons is underwriting an installed base, not a product roadmap. That works on AOL. Airtable is a harder bet.
Quick Questions
Did AI kill Airtable? No. Airtable grew more than 20% last year, holds roughly 90% gross margins, reached cash-flow positive in late 2024, and serves 80% of the Fortune 100. AI changed who could afford to own it at a price the cap table would accept.
Why does the enterprise value differ so much from the equity value? Airtable holds about $965 million of net cash, most of it unspent venture money. Enterprise value strips cash out to price the operating business on its own.
Is 2.7 times revenue a fair price? It is below the roughly 4.5 times median for private software M&A. Whether that reflects a forced seller, an uncompetitive process, or a real discount on seat-based revenue is the open question. All three arguments have evidence.
Who else does this? Thoma Bravo took Dayforce private for $12.3 billion. Vista and Blackstone bought Smartsheet. Constellation Software has run the model for decades. Private equity is sitting on trillions in dry powder against software trading near multi-year lows.
The Business Model Analyst Take
The price of your company depends on who is permitted to own it, and founders choose that pool the moment they take growth capital rather than at the moment they sell.
Airtable is a good business by every operating measure that matters: high gross margin, growing, cash generative, embedded in most of the Fortune 100. It sold at a discount to its own comparable set because a 2021 cap table with $1.4 billion of cost basis has no acceptable outcome at $2.25 billion, and the only buyers who show up for an asset in that position are the ones who underwrite cash flow instead of growth. The capital structure priced the exit, not the product.
That has a practical edge for anyone running a software company right now. If your growth rate has settled into the teens or twenties and you have institutional investors who need a multiple, you are already in the transfer queue whether you have noticed or not. The useful question is not how to restart growth. It is whether the business can generate the free cash flow that a leveraged buyer will demand, because that buyer is going to run the arithmetic on your payroll either way. You can do that math yourself first, on your own terms, while you still control the outcome.
The WSJ interviewed the sellers. The buyers had a better week.