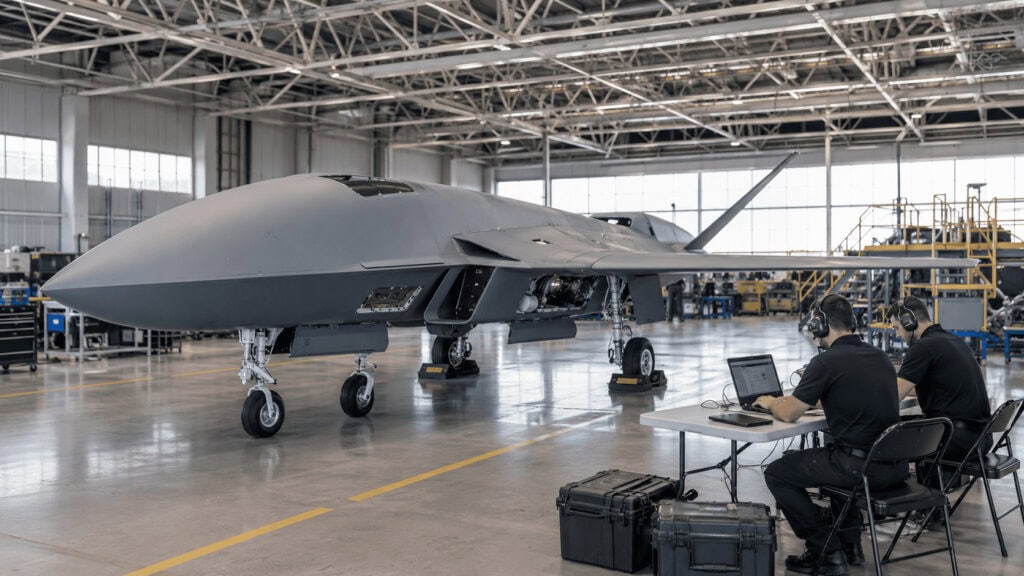

Anduril and General Atomics won production contracts for autonomous combat aircraft. The bigger shift is that the Pentagon bought the airframe and the software separately, and that breaks the oldest lock-in in defense.
On June 17, the U.S. Air Force awarded production contracts for its first fleet of semi-autonomous combat drones to Anduril and General Atomics, four months ahead of schedule. It also did something quieter and more consequential: it bought the aircraft and the autonomy software as two separate products, from two separate competitions.
For sixty years, buying a fighter jet meant buying a relationship. The airframe, the avionics, the mission software, the sustainment contract and the upgrade path all came from one prime contractor, bundled into a single decades-long dependency. Once the Air Force picked Lockheed for the F-35, it picked Lockheed for everything the F-35 would ever do. The Collaborative Combat Aircraft program just tested whether that has to be true.
What Happened
The Air Force announced on June 17 that General Atomics and Anduril both received engineering, manufacturing development and production contracts under Increment 1 of the Collaborative Combat Aircraft program. Both aircraft dropped the “Y” prefix that marks a prototype: the YFQ-42A became the FQ-42A Dark Merlin, and the YFQ-44A became the FQ-44A Fury. The service will field a split fleet of at least 150 aircraft by the end of the decade, with an eventual target near 1,000.
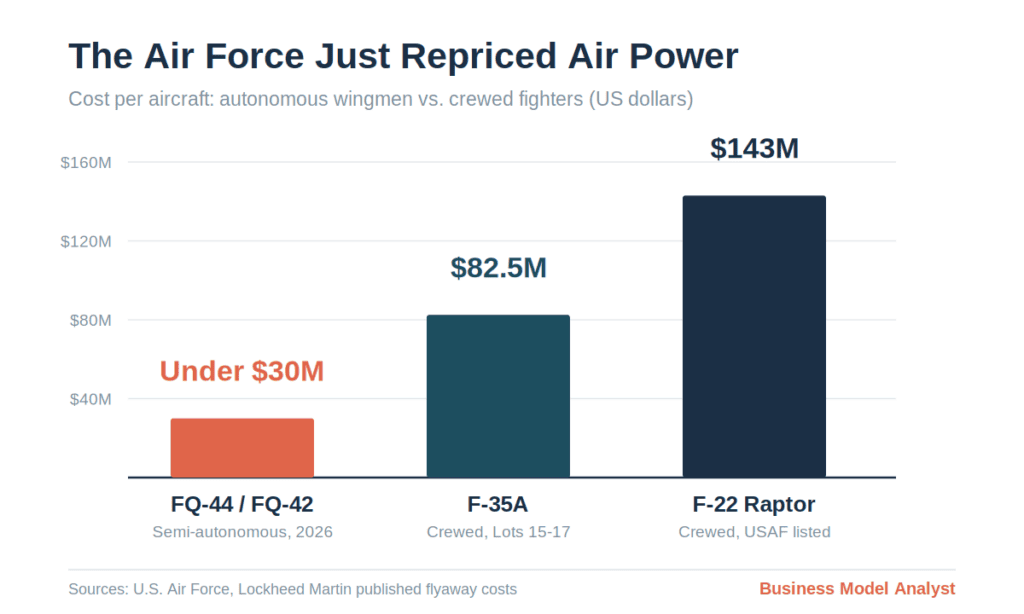
Col. Timothy Helfrich, the program acquisition executive for fighters and advanced aircraft, said the contracts cover the first three lots and that both companies will have equal opportunity to receive orders. The Air Force requested $996.5 million in fiscal 2027 to begin procurement. The target unit cost is under $30 million.
Separately, and this is the part that matters structurally, the Air Force established a six-year contract vehicle for mission autonomy software with a pool of six vendors: Anduril, General Atomics, Lockheed Martin, Northrop Grumman, RTX Collins Aerospace and Shield AI. Three of them, Anduril, Shield AI and Collins Aerospace, advanced immediately into head-to-head competition rounds. A single primary software provider gets named by summer 2027.
Underpinning all of it is a government-owned technical standard called the Autonomy Government Reference Architecture, which decouples the software from the airframe so that any vendor’s autonomy stack can be integrated onto any vendor’s aircraft.
The Backstory
The Air Force is flying roughly 5,000 aircraft, the smallest fleet in its 79-year history, and much of it is not mission-ready. Replacing that inventory one exquisite fighter at a time is arithmetically impossible. An F-35A carries an average flyaway cost of $82.5 million across production lots 15 through 17. The F-22 it flies alongside was listed by the Air Force at $143 million per unit and was cancelled at 187 airframes precisely because the math stopped working.
That is the constraint that produced CCA. If you cannot afford mass in crewed aircraft, you buy mass in uncrewed ones and attach them to the crewed fleet you already have.
Anduril flew the Fury for the first time on October 31, 2025. In March 2026, three months ahead of its own schedule, it opened production at Arsenal-1, a campus in Pickaway County, Ohio, that cost close to $1 billion to stand up. At that point the company had two known airframes and no production contract. Company officials described a line capable of 50 aircraft per shift, up to 150 a year, while acknowledging that capacity is not the same thing as orders.
That gap between capacity and orders was the entire risk. Three months later, it closed.
The Plan
The Air Force is running two competitions on different clocks, and that is deliberate.
Hardware moves on a manufacturing clock. Two suppliers, split lots, performance-based allocation, first orders released as soon as the fiscal 2027 budget clears. Neither company is guaranteed volume. Helfrich tied future orders to how well each delivers “capability at speed and scale,” which is a polite way of saying the two vendors will spend the next several years bidding against each other on throughput.
Software moves on an iteration clock. Six vendors in the pool, three in active competition, six-month evaluation rounds, a primary provider named in 2027 and the door explicitly left open after that. Autonomy gets treated as a component that can be swapped, not a feature that ships welded to the airframe. The Air Force has already demonstrated the principle in the air, flying the Fury under both Shield AI’s Hivemind and Anduril’s own Lattice.
The design intent is that no single vendor can hold the program hostage on either axis.
The Business Model Angle
This is the defense industry’s version of unbundling, and it rhymes with what happened to every other integrated hardware business in the last thirty years.
The cost-plus prime model is durable because switching costs are enormous. When the software, the airframe and the sustainment tail are one indivisible purchase, the buyer’s leverage collapses the moment the contract is signed. Every upgrade is a sole-source negotiation. That is the structural feature Anduril built its business model to attack, and the Air Force has now adopted the same logic as procurement policy.
Look at what a government-owned reference architecture actually does to the economics. It converts autonomy software from a captive component into a contestable market. The airframe becomes closer to a commodity platform competing on unit cost and delivery rate. The margin migrates to the software layer, where it can be recompeted every few years rather than locked for a program lifetime. That is not a defense procurement structure. That is a platform-and-vendor structure, and the closest existing analogue in the sector is Palantir’s government software model rather than anything in the traditional prime playbook.
Note who is positioned on both sides. Anduril won an airframe production contract and a seat in the software competition. General Atomics won an airframe contract and a place in the six-vendor software pool. Lockheed Martin and Northrop Grumman, two of the incumbent primes, are in the software pool without an airframe. The vertical integration that defined the incumbents is exactly the thing the new contract structure declines to reward.
There is also a manufacturing story inside the hardware bid. The Fury uses aluminum rather than titanium, composite techniques adapted from recreational boat building, and a commercial business jet engine chosen partly because its supply chain and maintenance network already exist at volume. Those are consumer hardware cost decisions applied to a combat aircraft, and they are what make a sub-$30 million target plausible at all. Compare that against the aerospace incumbents’ approach, where bespoke materials and single-source suppliers are the norm and a defensible source of pricing power.
The unresolved question is what the sustainment economics look like. Primes have historically made their durable money on the decades of maintenance, spares and upgrades that follow the sale, not on the airframe itself. A modular, recompeted, commodity-engine aircraft threatens that annuity. Nobody has shown yet what replaces it.
The Risk
The obvious risk is that unbundling is easier to announce than to sustain. Integration complexity is the reason vertical bundles exist in the first place. Every interface the Air Force opens is an interface someone has to own when a software update and an airframe revision collide in flight test. Reference architectures have a long history of eroding quietly under schedule pressure.
The commercial risk sits with Anduril. Winning a production contract is not the same as winning volume. The Air Force explicitly declined to say how lots will be divided, and made allocation contingent on delivery performance. Arsenal-1 was built for 150 aircraft a year against a program that needs 150 total across two suppliers by 2030. That is a lot of idle capacity if the split runs against them, and the factory was financed on the assumption it will not.
There is a budget risk too. The first lot award waits on fiscal 2027 appropriations. Nearly $1 billion requested is not $1 billion obligated, and CCA is competing inside a Pentagon budget that is absorbing large autonomous-systems commitments across multiple services simultaneously.
And there is a policy risk that sits outside the business case entirely. Autonomous weapons remain the subject of active international debate, with the International Committee of the Red Cross calling for binding restrictions and 156 countries signing a U.N. General Assembly resolution in November expressing concern about A.I.-enabled weapons. The United States, China and Russia were among the countries that declined to support it. Legislation has been introduced in the Senate that would write current Defense Department human-oversight policy into federal law. Any of that could change what these aircraft are permitted to do, which changes what they are worth.
Quick Questions
Who won the Air Force CCA production contracts? General Atomics for the FQ-42A Dark Merlin and Anduril for the FQ-44A Fury, both awarded June 17, 2026, four months ahead of schedule.
How much does a CCA drone cost? The Air Force is targeting under $30 million per aircraft, roughly a third of the $82.5 million average flyaway cost of an F-35A.
How many will be built? At least 150 combined by 2030, with the program eventually scaling toward roughly 1,000 aircraft.
Why is the software contracted separately? The Air Force uses a government-owned standard, the Autonomy Government Reference Architecture, that lets any vendor’s autonomy software run on any vendor’s airframe. Six companies compete for the software, with a primary provider selected by summer 2027.
Does a human still control the weapons? In the current design, yes. Air Force officials describe the aircraft as semi-autonomous, with a human pilot approving any weapons release and able to abort the mission.
The Business Model Analyst Take
The headline story is drones. The business story is that the Pentagon just demonstrated it can buy a weapons platform the way a company buys enterprise infrastructure: standardized interfaces, competed layers, multiple suppliers, recompeted contracts.
If it holds, the sixty-year prime contractor moat gets shallower, because the moat was never manufacturing capability. It was bundling. Incumbents kept customers by making the switch unthinkable, and a government-owned reference architecture is a direct assault on that.
The caution is that one program is not a doctrine. CCA is a favorable test case: new mission, no legacy fleet to protect, a service under acute fleet-size pressure and political appetite for supplier diversification. The real evidence arrives when the same structure is attempted on a program with an incumbent already installed and thirty years of sustainment revenue to defend. That is when we find out whether the Air Force unbundled the fighter jet or just unbundled the one it had not built yet.
For founders, the transferable lesson is the one Anduril just proved at scale. It spent close to $1 billion on capacity before it had a customer commitment, in an industry where the entire incumbent playbook is to invest only after the contract is signed. That inverted the sales conversation. When the Air Force needed to accelerate by four months, only the company with a running line could absorb the pull-forward. Capacity ahead of demand is a terrible general rule and an excellent specific bet when you know the buyer’s binding constraint is time.
Reporting on the Mojave Desert flight tests and the broader autonomous weapons debate: W.J. Hennigan, The New York Times Opinion, July 20, 2026. Contract details: U.S. Air Force announcements of June 17, 2026, as reported by Air & Space Forces Magazine, DefenseScoop, Aviation Week and FlightGlobal.