Investors stopped paying for a story about the 2030s. Now they want to know who sells electricity to data centers today.
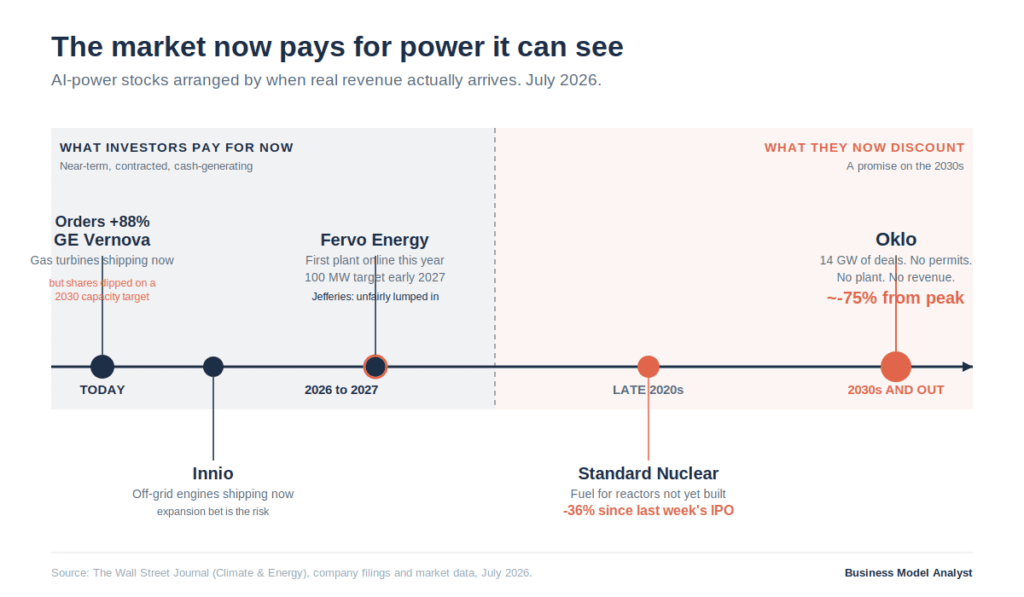
Not long ago, any stock with a data-center power story went up. That trade is over. In 2026 the market is sorting AI-power companies by a single question: when does the revenue actually arrive? Names that sell today are holding. Names whose payoff sits in the 2030s are being repriced hard, with Oklo down roughly 75% from its peak.
For about a year, the fastest way to add a zero to your valuation was to promise electrons to a data center. It did not matter much whether you had a plant, a permit, or a single paying customer. The narrative was enough. Sam Altman-backed Oklo briefly carried a valuation north of $25 billion last October on exactly that promise. This week it is a case study in what happens when investors stop buying the promise and start pricing the delivery date.
What Happened
Power stocks that rode the artificial intelligence boom are being sorted into two piles, and the sorting is brutal.
Oklo, the small modular reactor developer, has lost roughly three quarters of its value since its October peak. The company holds deals to supply more than 14 gigawatts of power to Meta and others, yet it has not secured the key permits it needs, let alone poured concrete on a commercial plant. It remains a pre-revenue company.
The pain is not limited to Oklo. Standard Nuclear, a uranium fuel producer that could one day feed novel reactors, has dropped about 36% since its initial public offering last week. It raised $150 million only after cutting its target because demand was soft. Innio, which sells reciprocating engines for off-grid power and competes with Caterpillar, has slipped as investors question whether its plan to expand manufacturing capacity will pay off if the market grows slower than hoped.
Even the clearest winner of the boom got a warning shot. GE Vernova, the gas-turbine maker, reported an 88% jump in orders this week. Its shares dipped anyway, right after it set a fresh target to expand manufacturing capacity by 2030.
The Backstory
To understand the whiplash, rewind to late 2025. Electricity demand from AI data centers was the hottest theme on the market, and it lifted anything adjacent to it. A uranium miner, a reactor blueprint, a geothermal startup, an engine manufacturer: if the pitch deck mentioned data centers, the stock moved.
That worked while investors were willing to underwrite the far future. The logic went like this: data-center demand in the 2030s will be enormous and supply will be tight, so whoever can sell power into that shortage will print money. Selling into a scarce market years from now became a perfectly good reason to fund a company today.
The mood has cooled for a simple reason. Building data centers is running into real-world limits. Skilled labor is scarce, supply chains are stretched, and construction is already lagging the most aggressive forecasts. As one analyst at Melius Research put it, at some point you have to ask who is actually selling to data centers right now, not in a decade. Demand does not have to collapse for these bets to disappoint. It just has to arrive slower than the hype assumed.
The Plan
Each of these companies is running the same basic playbook: raise money now against a demand curve that bends up sharply in the 2030s, then spend years building the capacity to serve it.
Oklo is targeting its first self-sustaining reaction this month as an early technical milestone, and it has stacked up letters of intent measured in gigawatts. Standard Nuclear wants to supply fuel for a reactor fleet that mostly does not exist yet. Fervo Energy, which adapts fracking techniques to tap geothermal heat, is further along: its first plant is due to start up this year and reach 100 megawatts of capacity in early 2027. GE Vernova, already selling turbines at scale, is betting big capital on a 2030 capacity expansion.
The common thread is that the reward is scheduled for later, and the spending is required now. That is a fine plan when capital is patient. It is a dangerous one when capital suddenly is not.
The Business Model Angle
Here is what the market is really repricing, and it is not “nuclear” or “AI.” It is the duration and the certainty of a revenue promise.
Strip away the technology and every one of these companies is selling the same product to investors: a claim on future cash flow. What changed in 2026 is the discount rate the market applies to that claim. When sentiment was hot, a dollar of 2032 revenue was worth almost a dollar today. Now it is worth a fraction, and the further out and less certain the dollar, the harder the haircut.
That reframes the entire sector into a clean spectrum. On one end sit the sellers, companies booking real revenue this year. GE Vernova is the archetype, and its 88% order growth is cash you can see. On the other end sit the storytellers, companies whose product is still a slide deck and a permit application. Oklo is the archetype there, and 14 gigawatts of signed deals is the tell, because a signed deal is not revenue. A letter of intent without a permit is an option, not a contract, and the market has decided to price it like one.
The most instructive data point is GE Vernova, though. It is the one selling today, and it still got dinged, purely because it attached a 2030 promise to its story. That is the whole lesson in one stock. In this tape, the market rewards the near-term cash and taxes the far-future ambition, even when they sit inside the same company.
This is the supply-side mirror of a story we have been tracking on the demand side. OpenAI now spends like a utility while it is still valued like software, having committed over $1 trillion against roughly $25 billion in annual revenue. The buyers of AI power are stretching their own business models to the limit to fund the buildout. It should not surprise anyone that the sellers of that power are being stress-tested just as hard. Even Meta, an Oklo customer, is trying to monetize its infrastructure buildout today rather than wait for the payoff. The instinct is identical up and down the chain: get paid now, discount the promise.
The Risk
The obvious risk is that the market is right and several of these companies never reach the finish line. Permits get denied, timelines slip, capital dries up before the first commercial megawatt ships, and a 14-gigawatt pipeline quietly becomes a footnote.
But there is a subtler risk that cuts the other way, and it is the one founders should sit with. The market is now so allergic to far-future revenue that it may punish good businesses for being early. Analysts at Jefferies made exactly this argument this week, saying it is unfair to lump Fervo Energy in with the out-of-favor reactor names, because Fervo actually has a plant coming online this year. When the discount rate on the future spikes, the market stops distinguishing between a company that is three years from revenue and one that is ten years from a permit. Both get sold. That is how genuinely good long-duration businesses get starved of capital in a repricing, and it is why “the market hates my sector” is not the same as “my business model is broken.”
Quick Questions
Why is Oklo stock down so much if the company is making progress? Because the progress is operational, not financial. Oklo is advancing its reactor design and targeting an early technical milestone, but it is still pre-revenue, still unpermitted for commercial operation, and its payoff sits years out. The market did not sour on the technology. It repriced how long investors must wait and how uncertain the wait is.
Is the AI data-center boom over? Not necessarily. The point analysts are making is narrower: construction does not have to collapse to disappoint investors, it just has to grow slower than the most aggressive forecasts. Labor shortages and supply bottlenecks are already capping the pace, which is enough to deflate stocks priced for a flawless boom.
Why did Fervo Energy hold up better than the reactor stocks? Timing. Fervo’s first geothermal plant is due to start up this year and hit 100 megawatts in early 2027, which is near-term by the standards of this sector. Jefferies argues it is unfair to group it with reactor developers whose revenue is a decade away.
What does “selling into a tight market in the 2030s” mean? It is the core bet behind most of these companies. The wager is that AI will make electricity scarce and expensive years from now, so building power capacity today means selling into a shortage later. It is a good story. The problem is that investors have to fund the wait, and they have decided the wait is too long and too uncertain to pay full price for.
The Business Model Analyst Take
The tidy headline is “AI power bubble deflates.” That framing is lazy, and it will cost you money if you believe it.
What is actually happening is a repricing of revenue duration, and it is one of the most useful signals a founder can watch. For roughly a year, the market let companies monetize a narrative about the 2030s. That window is closed. Capital has swung back to a boring, durable question: what are you selling this year, to whom, under a contract that clears? A BNP Paribas analyst framed it precisely, noting that investors now want to pay for the pre-2030 story and put far less weight on the 2030s.
The strategic lesson generalizes well beyond nuclear reactors. In a cheap-capital environment, the business model that wins is the one with the biggest, boldest future. In a picky-capital environment, the winner is the one with the shortest, most certain path to cash. Same company, same technology, wildly different valuation depending only on which regime you are in. If your model depends on investors underwriting a payoff many years out, you are not running an energy company or an AI company. You are running a bet on the market’s patience, and that patience just got a lot shorter.
The counterpoint is worth holding too. Repricings overshoot. When the market refuses to distinguish Fervo’s 2027 plant from Oklo’s 2030s permit, it is creating exactly the mispricing that patient operators and investors get paid to exploit. The trade is not “avoid the future.” It is “know precisely how far away your revenue is, and never let anyone confuse a signed deal with a paid invoice.”
Reporting and figures via The Wall Street Journal (Climate & Energy, July 23, 2026), with company filings and market data. Analysis and framing by Business Model Analyst.