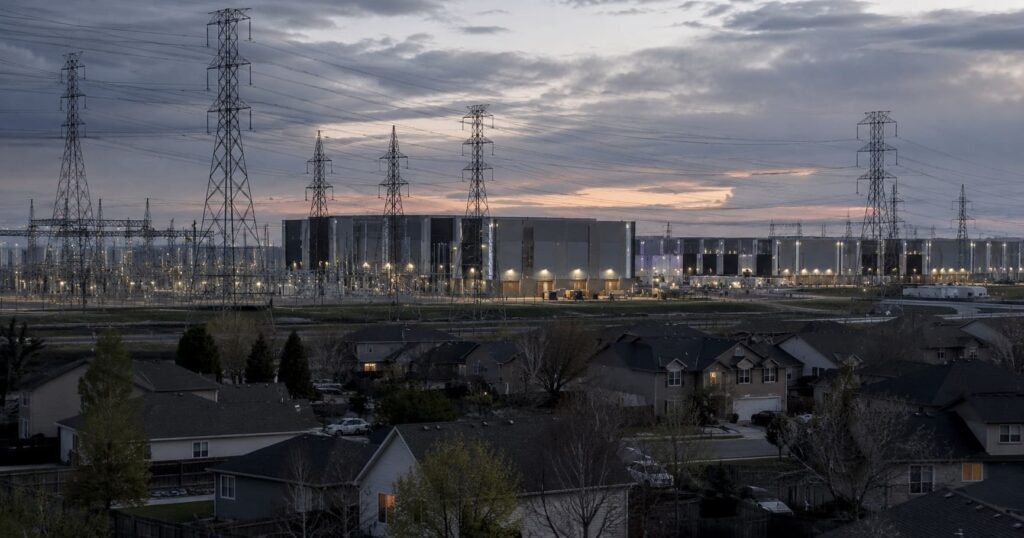

The AI infrastructure boom has collided with a power system that was never designed to absorb it. In 2026, the bottleneck for the largest tech companies on earth is no longer chips or capital. It is megawatts. And the strain is now showing up where voters feel it most: their monthly electricity bills.
Definition Box: What does “breaking the grid” actually mean? The phrase is shorthand for three connected problems. First, AI data centers add huge, concentrated, around-the-clock electricity demand to local grids faster than new power generation can be built. Second, that demand inflates wholesale power prices and forces costly transmission upgrades. Third, the cost of those upgrades is frequently spread across all ratepayers, not just the data centers driving them. The grid is not collapsing. It is being financially and physically overloaded in specific regions.
The Scale of the Problem
Start with the demand curve. Lawrence Berkeley National Laboratory projects that U.S. data center electricity demand will grow from roughly 176 terawatt-hours in 2023, about 4.4% of national consumption, to between 325 and 580 TWh by 2028, or 6.7% to 12% of the total. Goldman Sachs Research forecasts a 165% jump in global data center power demand by 2030 versus 2023.
The issue is not just the total. It is the concentration. A single hyperscale data center can consume as much power as 100,000 households, and the next-generation campuses now under construction will demand roughly twenty times that. According to the Electric Power Research Institute, data centers already consumed about 26% of all electricity supplied in Virginia in 2023. EPRI’s 2026 update projects that share could climb to between 41% and 59% by 2030.
One number captures why this is different from past demand growth: a single AI task can use up to 1,000 times more electricity than a traditional web search. That intensity lets a handful of facilities destabilize a regional grid in ways that hundreds of conventional data centers never could.
| Metric | Figure | Source |
|---|---|---|
| U.S. data center demand, 2023 | 176 TWh (4.4% of total) | LBNL |
| Projected U.S. demand, 2028 | 325 to 580 TWh (6.7% to 12%) | LBNL |
| Global demand growth by 2030 | +165% vs 2023 | Goldman Sachs |
| Virginia data center share, 2023 | ~26% of electricity | EPRI |
| Projected Virginia share, 2030 | 41% to 59% | EPRI |
| Single AI task vs web search | Up to 1,000x more power | Multiple |
Why the Bill Lands on Households
This is the part that turned an engineering story into a political one. Utilities requested more than $29 billion in rate increases in the first half of 2025, double the figure from the same period a year earlier. By the end of 2025, average U.S. electricity prices had reached about 19 cents per kilowatt-hour, roughly 27% higher than in 2019 after more than a decade of flat pricing.
Two mechanisms push those costs onto ordinary consumers. New data centers require new generation, and the U.S. still faces a projected generation shortfall of about 49 gigawatts through 2028. They also force expensive transmission and distribution upgrades, such as high-voltage lines and substations. Under most utility structures, those infrastructure costs get socialized across the entire customer base.
Capacity auctions make the squeeze concrete. The PJM Interconnection auction, which serves a 13-state region, cleared at its maximum allowed price for the second year running, with data centers cited as the majority driver of a projected 5,400-megawatt demand increase. Consumers in that region face bill increases of 1.5% to 5% starting in summer 2026.
The political reaction has been swift. In 2026 alone, lawmakers in more than 30 states introduced over 300 bills touching data centers, from moratoriums to tax-incentive rollbacks. At the federal level, the SHIELD Act and the Power for the People Act both aim to force large energy users to pay for the grid infrastructure they require. In early 2026, major AI firms signed a nonbinding “ratepayer protection pledge” at the White House, committing to “build, bring, or buy” their own power. Microsoft and Anthropic separately pledged to cover electricity cost increases tied to their facilities.
The Skeptic’s Case: Is the Grid Really Breaking?
Here is where most coverage gets lazy, and where a sharper read matters. Not everyone agrees the grid is breaking, and the contrarian argument is strong enough to take seriously.
The core counterpoint: a data center announcement is not electricity consumption. It is a claim on power, land, equipment, and interconnection that may never materialize. New data center deals fell more than 40% between the third and fourth quarters of 2025. Of roughly 240 GW of announced construction, only about one-third is actually being built, and hyperscaler capital spending could fall by half in 2026. OpenAI’s flagship Stargate project in Texas reportedly stalled amid partner disputes.
There is also a fact-check worth noting. When Senator Elizabeth Warren claimed people near data centers pay up to 267% more for electricity, PolitiFact rated it “Mostly False,” because that figure referred to wholesale prices, not residential bills. Data centers are a real driver of rising costs, but they are not the sole cause. Aging infrastructure, equipment costs, and clean energy mandates all contribute. SemiAnalysis has argued that market design and policy decisions matter more than AI buildout alone.
The honest framing is this: the grid is not uniformly breaking. It is breaking in specific places, at specific times, under specific market rules. That distinction is exactly where the fixes live.
How to Fix It
The solutions fall into four buckets, and the smart money is pursuing all of them at once.
1. Bring your own power. The fastest-growing response is behind-the-meter generation, where data centers self-generate rather than wait in interconnection queues. The Foley 2026 Data Center Survey found that 56% of developers are exploring on-site or co-located power. Research suggests a 500 MW data center using a flexible behind-the-meter approach can reach full operation three to five years faster than via traditional interconnection. Talen Energy’s data center co-located with the Susquehanna nuclear plant is the model taken to its logical endpoint.
2. Firm clean power, especially nuclear. AI’s 24/7 load profile is a near-perfect match for nuclear baseload. Small modular reactors and microreactors have moved from long-range aspiration to near-term candidate. Meta has signed 20-year nuclear purchase agreements and joined SMR development projects with Oklo and TerraPower. The catch is timeline and regulation: SMRs will not arrive at scale before the early-to-mid 2030s, and a single high-profile incident could reverse momentum overnight.
3. Natural gas as the bridge. Most experts expect natural gas to be the dominant near-term answer because it provides reliable, dispatchable power that handles the fluctuating loads of AI campuses. Encouragingly, the latest PJM auction saw several generators reverse planned retirements, the first real supply response in four auctions.
4. Demand flexibility. The cheapest megawatt is the one you do not need at peak. By agreeing to curtail or shift load during grid stress, data centers can win faster grid access. The problem is regulatory: outside of Google, almost no operator has integrated load flexibility at scale, and most markets do not yet offer a faster connection path for flexible loads.
| Solution | Speed to deploy | Main constraint |
|---|---|---|
| Behind-the-meter generation | Fast (1 to 3 years) | Site and capital intensity |
| Nuclear (SMR / microreactor) | Slow (early-to-mid 2030s) | Regulation and timeline |
| Natural gas bridge | Fast | Emissions and policy |
| Demand flexibility | Immediate in theory | Market rules undefined |
What This Means for the AI Business Model
The strategic shift is profound. Data centers are moving from passive energy consumers to active grid stakeholders that co-invest in infrastructure, deploy on-site generation, and absorb delivery risk. Power procurement is becoming a core competitive moat, not a back-office line item. The hyperscalers and chipmakers driving this buildout, from NVIDIA to OpenAI, now compete on access to electrons as much as on models and silicon.
That has direct implications for valuations and risk. The companies best positioned are those that can secure firm, affordable, low-carbon power on their own terms. The ones most exposed are those betting on grid interconnection timelines they do not control. For a deeper look at how energy strategy is reshaping competitive positioning, see our analysis of NVIDIA’s strengths and threats and the best AI companies to watch in 2026.
The Business Model Analyst Take
The “breaking the grid” framing is half right, and the half it gets wrong is the more useful half. The grid is not failing as a system. It is being overloaded in concentrated pockets under outdated market rules that let large users socialize their costs. That is a policy and procurement problem, not a physics dead end.
The winners of the next phase will not be whoever announces the biggest gigawatt figure. Announcements are cheap, and roughly two-thirds of them will not get built. The winners will be the operators who treat power as a strategic asset: locking in firm clean supply, building behind the meter, and absorbing delivery risk to jump the interconnection queue. The companies still treating electricity as someone else’s problem are the ones whose AI ambitions will quietly stall, not because the models failed, but because the megawatts never showed up.