
Chipmakers and cloud providers have rebuilt their business models around long-dated contracts. The last time the industry tried this, the contracts quietly dissolved.
Contracts have become the load-bearing wall of the AI boom. Micron has signed 16 take-or-pay supply agreements worth roughly $100 billion in minimum contracted revenue. Oracle closed fiscal 2026 with $638 billion in remaining performance obligations, up 363% in a year. Executives call it visibility. History calls it something less flattering: a backlog that gets renegotiated the moment demand softens.
Every boom eventually invents a financial instrument to make itself feel permanent. This one picked the supply contract. Across memory, cloud, chips, and manufacturing equipment, the entire AI stack has spent the past twelve months converting handshake demand into signed, multi-year, non-cancellable paper. The paper is now the asset. Lenders finance against it, investors multiply it, and capacity gets built on the strength of it. The awkward question nobody wants to ask out loud is what a take-or-pay contract is actually worth when your customer no longer wants the product.
What Happened
The Wall Street Journal’s Heard on the Street column flagged the problem on July 20: the long-term arrangements underpinning the AI trade are far less solid than the companies touting them suggest.
The numbers behind that warning are enormous. Micron reported fiscal Q3 2026 revenue of $41.46 billion, more than quadruple the $9.3 billion it posted a year earlier, and disclosed 16 Strategic Customer Agreements covering roughly 20% of its DRAM volume and about a third of its NAND volume. CEO Sanjay Mehrotra told analysts that once complete, roughly half or more of company revenue will sit under these agreements. The contracts run five years, from calendar 2026 through 2030, with three-year terms for automotive customers. They carry binding volume commitments, negotiated quarterly pricing inside floor and ceiling bands, and more than $22 billion in customer cash and financial commitments, including nearly $18 billion in deposits.
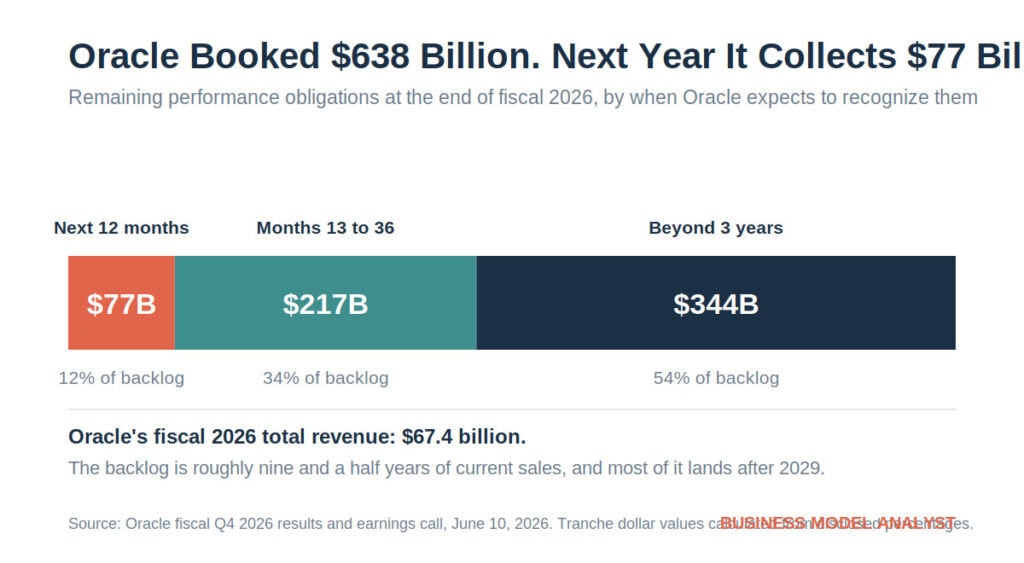
Oracle’s version is larger still. Remaining performance obligations hit $638 billion at the end of its fiscal year, up $85 billion in a single quarter. Finance chief Hilary Maxson described that figure as exceptional visibility into future revenue growth, supported by long-term contractual commitments. Bank of America analysts estimate more than half of it traces back to a single customer: OpenAI.
The same structure repeats down the chain. AI developers contract with clouds like Oracle and CoreWeave. Those clouds contract for chips. Chip designers contract with TSMC. TSMC contracts with ASML. Each link books the next link’s promise as its own certainty.
The Backstory
We have run this experiment before, and recently. We covered the equity-market version of this debate in why Wall Street calls Micron the next Nvidia. This is the supply-chain version.
During the pandemic chip shortage, Microchip Technology launched its Preferred Supply Program in February 2021. The trade was simple: customers committed to 12 months of continuous, non-cancellable, non-reschedulable orders, and in exchange got priority capacity six months out. It worked spectacularly at first. By the March 2021 quarter, about 44% of Microchip’s backlog sat inside the program, and close to 100% in the most constrained product areas.
Then the shortage became a glut. The program was scrapped. Contracts were pushed out by years. Customers received exemptions from commitments they had signed in writing. CEO Steve Sanghi later described the company’s own order program as inflexible in a way that limited cancellations and pushouts, and said it prolonged Microchip’s downturn rather than cushioning it. The non-cancellable backlog did not protect the supplier. It trapped it in a relationship where enforcement would have cost more than forgiveness.
That is the precedent sitting underneath every take-or-pay agreement signed in the past year.
The Plan
Memory makers are explicit about what they are trying to do: kill the cycle.
For four decades, DRAM has followed one script. Boom, build, flood, collapse, nurse losses, repeat. Samsung, SK Hynix, and Micron are all posting record profits and pointing to a shortage they expect to persist into 2028. SK Hynix listed shares in New York this month to monetize the enthusiasm. The contracts are the mechanism meant to make this time different, converting a spot-priced commodity into something resembling contracted, margin-floored backlog.
Oracle’s plan is a variation on the same theme. It has demanded long-term capacity commitments and, notably, restructured how the hardware gets paid for. Prepaid and customer-supplied GPU portions of its large AI contracts now total $75 billion, which reduces the capital Oracle itself must raise. Even so, fiscal 2026 capital expenditure hit $55.7 billion and free cash flow came in at negative $23.7 billion. Oracle raised $43 billion in debt during the year and expects roughly $40 billion more in fiscal 2027.
Build ahead of the contract, fund the build with debt, service the debt with the contract. That is the model.
The Business Model Angle
Here is the part worth sitting with, because it is a business model question dressed as an accounting one.
A backlog is not cash. It is a claim on a customer’s future willingness to pay, and that willingness is contingent on the customer’s own business working. Take-or-pay language changes the legal position, not the commercial one. If demand for memory or compute rolls over, suppliers face a genuinely bad choice: enforce the contract and ship product into a customer that will warehouse it, or renegotiate and preserve the relationship.
Enforcement is worse than it looks. Chips shipped into an unwilling customer sit as inventory. That inventory gets drawn down before any new orders arrive, which pushes the supplier’s next revenue cycle further out. The supplier wins the invoice and loses the following two years of demand. And if a competitor offers flexibility while you litigate, you have traded a customer for a payment.
So the rational move in a downturn is almost always to blink. Which means the contract’s real function is not enforcement. It is signaling. It tells capital markets that revenue is de-risked, which lowers the cost of funding the capacity, which is the thing the supplier actually wanted. Micron’s 16 agreements did not just lock in volume, they unlocked $18 billion in deposits and the confidence to raise fiscal 2026 capex to roughly $27 billion.
That is a legitimately clever piece of financial engineering. It is not the same thing as demand.
The chart below is the cleanest illustration of the gap. Oracle’s $638 billion backlog is roughly nine and a half times its entire fiscal 2026 revenue, and management expects only 12% of it to convert within twelve months. More than half lands beyond three years, in a market nobody can forecast.
The Risk
The Bank for International Settlements, the central bank for central banks, put the systemic version of this in its 2026 Annual Economic Report, published June 28. Temporary shortages, it warned, may amplify overinvestment as firms attempt to lock in future capacity through long-dated contracts that further expose them to any disappointments in demand.
That is the whole risk in one sentence. The contract designed to reduce risk is the mechanism that concentrates it.
The BIS put the five largest hyperscalers on track to spend more than $1 trillion on AI capital expenditure across 2025 and 2026 combined, exceeding their earnings and free cash flow and pushing some to issue debt. It drew explicit parallels to canal mania, the British railway bubble, and the dot-com boom, each a real technological breakthrough that attracted more capital than returns could justify.
Three specific exposures follow. Concentration risk, where over half of Oracle’s backlog reportedly depends on one cash-burning customer. Financing risk, where lenders have extended credit against contracts whose enforceability is commercially theoretical. And circularity risk, where suppliers, customers, and investors in these deals are increasingly the same small group of companies, meaning a single disappointment propagates through the chain instead of being absorbed by it.
Quick Questions
What is a take-or-pay contract? An agreement where the buyer commits to pay for a minimum volume whether or not they take delivery. It shifts volume risk from the seller to the buyer, at least on paper.
What are remaining performance obligations? RPO is the total contracted revenue a company has signed but not yet delivered. It is a disclosed accounting figure, not cash in hand, and it can be renegotiated, extended, or restructured.
Are these contracts legally enforceable? Generally yes. The question is whether suppliers will enforce them. Historical precedent from the 2021 to 2023 chip cycle suggests they usually will not, because enforcement damages the customer relationship and delays the next demand cycle.
Does this mean memory stocks are overvalued? Not necessarily. It means the revenue visibility premium built into those valuations rests on an assumption that has not been tested in a downturn.
Who is most exposed if AI demand slows? Companies that financed capacity with debt against contracted backlog, rather than those with prepaid cash. Deposits are real money. Signed obligations are not, until they are collected.
The Business Model Analyst Take
The AI supply chain has quietly rebuilt itself around a single assumption: that a signed contract is a substitute for demand. It is not. It is a substitute for uncertainty, and only in the direction that flatters the seller.
The tell is that every party in the chain is booking the same dollar as certainty. The developer counts its reserved compute as capacity secured. The cloud counts the same deal as backlog. The chipmaker counts the cloud’s order as contracted revenue. The equipment maker counts the chipmaker’s order the same way. One dollar of AI demand gets recognized as confidence four or five times over. That is not fraud, it is just how supply chains account for themselves. It becomes a problem when the underlying dollar is contingent and everyone has already spent against it. The demand-side bill is already visible in consumer pricing, as we traced in Apple’s memory-driven price hikes.
For founders, the transferable lesson has nothing to do with semiconductors. When a customer commits to a long contract during a shortage, you have not acquired durable revenue. You have acquired a strong negotiating position that decays the moment conditions loosen. Price that decay in. Take the deposit over the term, because cash collected is the only part of a contract that survives a downturn intact.
Micron understood this better than most, which is why it took $18 billion up front. The companies that took the term without the cash are the ones to watch.
Reporting based on The Wall Street Journal’s Heard on the Street column of July 20, 2026, Oracle’s fiscal Q4 2026 results and earnings call, Micron’s fiscal Q3 2026 results and 10-Q, Microchip Technology disclosures, and the Bank for International Settlements Annual Economic Report 2026.