
A 2009 self-help concept is spreading across tech as workers brace for AI. The industry selling it cannot agree on whether it is a $1.2 billion market or a $113 billion one.
The New York Times reported on July 19, 2026 that “zone of genius,” a term from Gay Hendricks’ 2009 book The Big Leap, is circulating widely across tech as AI reshapes careers. The revival is less a philosophical shift than a demand signal for the professional coaching industry, whose own published market-size estimates diverge by roughly 94 times.
There is a tell buried in the reporting, and it is not the phrase itself. It is the fact that Andreessen Horowitz named a podcast after it in 2023. When a venture firm borrows a self-help vocabulary word for its content marketing, the word has stopped being an idea and started being a customer acquisition channel.
What Happened
The Times documented “zone of genius” cropping up across X, LinkedIn, tech podcasts, and newsletters, driven by workers anticipating AI’s arrival in their careers. The concept describes the overlap between what a person is skilled at and what they are passionate about. Hendricks, now a career coach with decades of practice and more than 40 books behind him, described the state as freedom, zest, and energy rather than mere workplace satisfaction.
The reach extends past Silicon Valley. Toastmaster Magazine ran a feature on it. The Tory Burch Foundation hosted a founders’ webinar. Gwyneth Paltrow deployed it on Goop in March to describe her stylist’s red carpet work.
Nobody involved is selling philosophy. Hendricks sells books and coaching. Andreessen Horowitz sells access to founders. Goop sells everything.
The Backstory
The Big Leap landed in 2009, at the bottom of a recession, with a simple four-tier model: zones of incompetence, competence, excellence, and genius. Its actual load-bearing idea is the “Upper Limit Problem,” the claim that people self-sabotage once they exceed an internal ceiling on how much success they will tolerate.
The framework has never had an evidence base. Reviewers have consistently flagged the same gap: no data supporting the mechanism, and no concrete process for escaping it. Hendricks published a follow-up, The Genius Zone, in 2021, which is the standard tell that the first book left a gap the market was still paying to close.
That is not an insult to the book. It is a description of the product. Self-help frameworks are not falsifiable, and their unfalsifiability is a feature of the business model, not a defect in the writing.
The Plan
The playbook here is well established and does not require anyone to coordinate.
A term gains cultural velocity. Coaches adopt it as positioning language, because a coaching practice has no credential moat and language is the only differentiator available. Platforms adopt it as content marketing. Media covers the adoption, which accelerates the velocity. Search volume rises. New coaches enter to serve the demand, and the fastest way to enter is to buy a certification from an existing coach.
The International Coaching Federation counted roughly 122,974 practitioners globally in its 2025 study, up 54% in six years. Practitioner supply is compounding faster than most of the underlying client demand, which is exactly what you would expect from an industry where the highest-margin product is training the next cohort of competitors.
The Business Model Angle
Coaching is a service business with no licensure, no revenue floor, and no agreed definition of its own product. Those three facts explain the entire market structure.
Start with the numbers. The ICF, working from practitioner-reported revenue, put the global coaching market at $5.34 billion in 2025. Mordor Intelligence priced “executive coaching and leadership development” at $112.98 billion for 2026. A widely recirculated MarketWatch-derived figure puts global executive coaching at $1.2 billion by 2026. ResearchAndMarkets valued the US professional coaching market alone at roughly $16 billion.
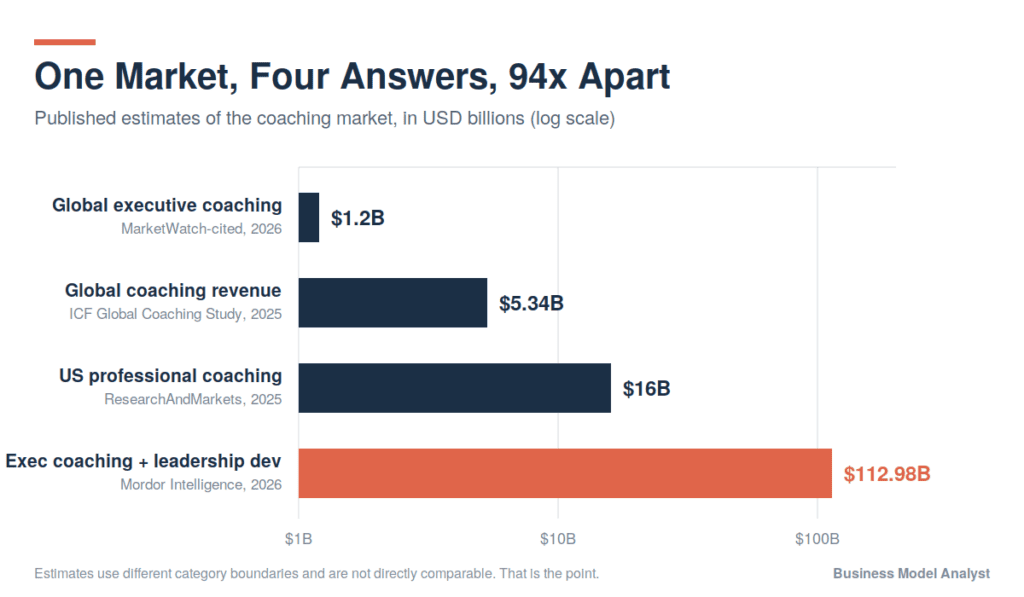
Those estimates are not measuring the same thing, and each firm draws the category boundary where its own funnel benefits. That is the finding. In a market with real unit economics, the boundary is set by what customers buy. Here it is set by what the estimator sells.
The revenue architecture splits cleanly into two models. The first is direct service: a coach charges $250 to $500 an hour, works independently, and is capped hard by hours in the day. Roughly 65% of coaches work solo, which means most of the industry is a freelance business with a ceiling.
The second model is where the money is. Sell the method, not the sessions. Books, certifications, licensed frameworks, and cohort programs all convert a labor business into an intellectual property business with genuine operating leverage. Hendricks did not build a coaching practice at scale. He built a vocabulary, and then sold access to it 40 books at a time. This is the same structural move MasterClass made when it turned individual expertise into a subscription catalog, except that a coaching certification also converts each buyer into a distribution node.
The enterprise layer sits above both. BetterUp and CoachHub route coaching through HR budgets instead of individual credit cards, which solves the two problems that cripple solo practitioners: customer acquisition cost and contract length. An employer buying coaching for 4,000 people is a fundamentally different business from a coach selling to one anxious product manager.
AI anxiety is the acquisition engine underneath all three layers. It does not sell a specific coaching product. It sells the premise that your current skills may not be the ones that matter in two years, which is the most efficient demand generator this industry has had since the 2008 layoffs.
The Risk
The obvious risk is that AI eats the low end of the category it is currently inflating. A large share of entry-level coaching is structured questioning, goal tracking, and accountability check-ins. That is a workflow, and workflows are exactly what language models absorb first. Roughly 54% of coaches already offer some AI-assisted service, which is less a strategy than a concession.
The subtler risk is supply. If practitioner count keeps compounding at recent rates while enterprise budgets consolidate around a handful of platforms, the middle of the market gets hollowed out. What survives is enterprise platforms at the top and named IP owners like Hendricks at the bottom of the cost curve. The independent coach with a certification and a LinkedIn presence is squeezed from both ends.
And the term itself carries reputational risk for the buyer. Once a concept travels from a psychology book to a VC podcast to a celebrity lifestyle site inside three years, its half-life as a serious positioning tool is short. The coaches building practices on “zone of genius” language in 2026 are building on a phrase that will read as dated by 2028.
Quick Questions
What is the zone of genius? It is the overlap between what someone is skilled at and what genuinely energizes them, one of four zones described in Gay Hendricks’ 2009 book The Big Leap. The other three are incompetence, competence, and excellence.
Why is it trending again in 2026? Workers anticipating AI disruption are reassessing what parts of their jobs are durable. The framework offers a vocabulary for that reassessment, and tech media, VC content marketing, and LinkedIn amplified it.
How big is the coaching industry actually? There is no reliable single answer. Published estimates for 2025 and 2026 range from $1.2 billion to $112.98 billion depending on whether the definition covers only practitioner fees or the full corporate leadership development budget.
Is there evidence the zone of genius framework works? No controlled evidence supports the underlying “Upper Limit Problem” mechanism. Reviewers have consistently noted the absence of data and of a concrete process.
Who makes the most money from coaching? Not individual coaches. The margin sits with certification sellers, framework licensors, and enterprise platforms that sell into HR budgets rather than to individuals.
The Business Model Analyst Take
Every recession and every technology shock produces a vocabulary boom in the advice industry, and the vocabulary is always the product. In 2009 the anxiety was financial and the word was “genius.” In 2026 the anxiety is automation and the word is still “genius,” which tells you how little the underlying demand has changed and how much the packaging matters.
The lesson for founders is not about coaching. It is about what happens when you own a category’s language. Hendricks did not build the largest coaching practice in the world. He built a term that other people’s businesses now depend on, which means his framework gets distributed for free by thousands of practitioners who have no other way to differentiate. That is a licensing business disguised as a book.
The lesson for buyers is simpler. When an industry cannot measure itself to within two orders of magnitude, that is not a data problem. It is a structural signal that the product has no fixed definition, and anything without a fixed definition is priced by narrative rather than by outcome. Ask what specifically changes, by when, and how it gets measured. If the answer is zest, you are buying a vocabulary.