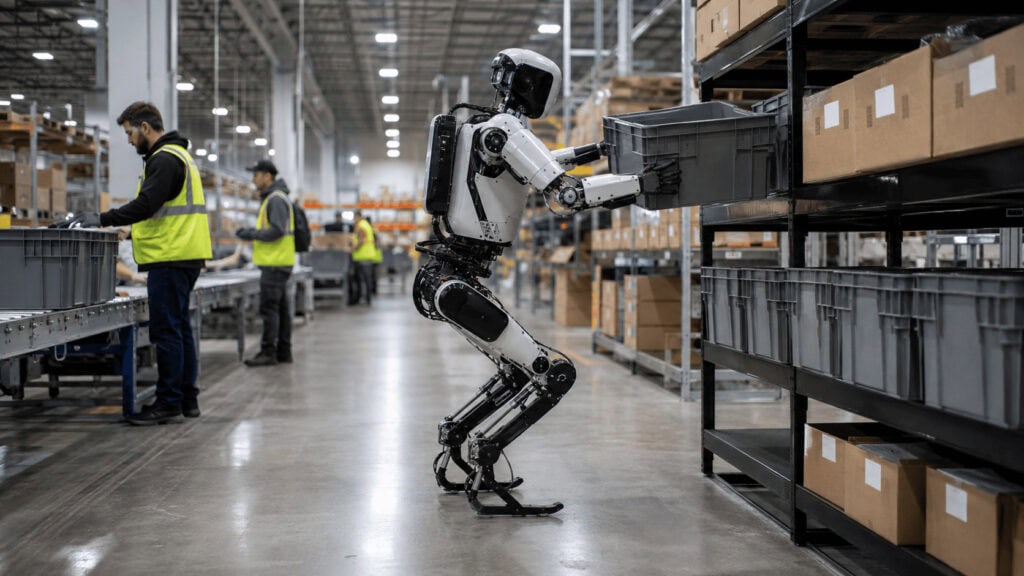

The first US humanoid listing rests on a 1,000-robot order from an unnamed customer who got warrants for signing. Agility now has to produce 185 times more robot-hours than it has ever logged.
Agility Robotics is going public through Michael Klein’s Churchill Capital Corp XI at a $2.5 billion pre-money value, carrying an order book of more than $300 million. That order book is one three-year robots-as-a-service contract for 1,000 machines, placed by a customer Agility will not name, sweetened with warrants that vest as the robots roll out. The robots in question ship in December. Agility priced each one at roughly what a fully loaded warehouse worker costs per hour, which means the entire investment case turns on how many hours the machines run.
Peggy Johnson has spent the summer telling anyone who will listen that humanoid robotics left the demo stage. She is right, and the filings prove it in a way the marketing does not. Agility’s Digit has logged more than 65,000 operating hours across nine facilities. The order it just signed commits the company to about 12 million.
What Happened
Johnson told the Wall Street Journal’s CEO Brief this week that today’s bipedal robots go well beyond back flips and making coffee, and that humanoid robotics has moved into real paid deployments. She named the roster: Amazon, car-parts maker Schaeffler, GXO Logistics, Mercado Libre, and Toyota Motor Manufacturing Canada.
The deal underneath that pitch was announced on 24 June. Agility merges into Churchill Capital Corp XI, trades as AGLT, and expects more than $620 million in gross proceeds. About $421 million sits in Churchill’s trust, assuming nobody redeems. Another $201 million comes from a PIPE priced at $10 a share and led by Foxconn. Churchill Sponsor XI LLC holds 25.7% of the shell. Every existing Agility shareholder rolls into the combined company under a 180-day lockup, and the parties are targeting a fourth-quarter close. They submitted a confidential draft Form S-4 on 14 July.
Churchill shares closed around $16 this week against a 52-week range of $10.07 to $19.69. Buyers at that level are paying roughly 60% above the price the deal was struck at, which puts the market’s implied value on Agility closer to $4 billion than $2.5 billion.
The Backstory
Agility spun out of Oregon State University in 2015. Its first product, Cassie, was a pair of legs sold to robotics labs. Digit followed in 2017, also sold to academic buyers, then to Ford for last-mile delivery experiments. The company’s first real commercial deal came through GXO, moving plastic totes around a Spanx factory in Georgia, leased rather than sold.
That history matters because Agility already made the crossing that Unitree is asking Shanghai investors to fund. Unitree ships more humanoids than anyone and sells most of them to research budgets. Agility started in research budgets and left. Johnson arrived from Microsoft in March 2024, after six years running business development under Satya Nadella and a long run at Qualcomm under Irwin Jacobs, and pointed the company at payrolls.
She has been careful in interviews, which is unusual in this category. Asked about the wreckage of the 2021 SPAC class, she said Agility would keep its head down and deliver customer by customer. She has also brought in a public-company finance bench: Michael Beer, previously CFO at Energy Vault Holdings, took the CFO seat in July, freeing Jennifer Hunter to run operations as a dedicated COO.
The rules Agility is listing under are stricter than the ones that produced the 2021 blowups. The SEC adopted its SPAC rules in January 2024 on a 3-2 vote, effective that July. Target companies now sign the registration statement as co-registrants and carry Section 11 liability. The PSLRA safe harbor for forward-looking statements no longer covers de-SPAC projections. And any projected figure that is not grounded in historical results has to be distinguished from one that is, with the historical numbers shown at equal or greater prominence.
Read the fine print on Agility’s $300 million with that rule in mind and it stops looking like boilerplate.
The Plan
Proceeds go toward fulfilling the order book, scaling Digit v5 production at the 70,000-square-foot RoboFab plant in Salem, Oregon, and continued platform investment. Agility says that plant can build up to 10,000 humanoids a year. A second site in Fremont, California, 60,000 square feet and about 200 people, handles the software and skills work.
Digit v5 is the product the order was written against, and it launches in December. Chief business officer Daniel Diez has been arguing that the constraint on humanoid deployment was never skills or batteries but cages: every prior Digit ran inside fenced work cells that kept people out. V5 is designed for cooperative safety, meaning it works in the aisle alongside staff, with swappable end effectors and what Agility describes as 20-hour operational days.
Take the safety claim seriously. Fenced automation requires the customer to rebuild the floor. Unfenced automation drops into a building that already exists. That difference is worth more to a logistics operator than any dexterity benchmark.
The Business Model Angle
Do the arithmetic the filings invite. More than $300 million across 1,000 robots on a three-year term works out to $300,000 per robot, or $100,000 per robot-year, or about $8,333 a month.
Now price the hour. Agility’s own contract materials put Digit’s service life near 20,000 hours over roughly five years, which implies 4,000 hours of work a year. Divide $100,000 by 4,000 and a Digit costs $25.00 an hour.
A warehouse worker costs $25.92. That is the BLS median annual wage for hand laborers and material movers, grossed up by the benefits share the BLS reports for private industry, spread over a 2,080-hour year. Amazon puts its own frontline fulfillment total compensation above $29.
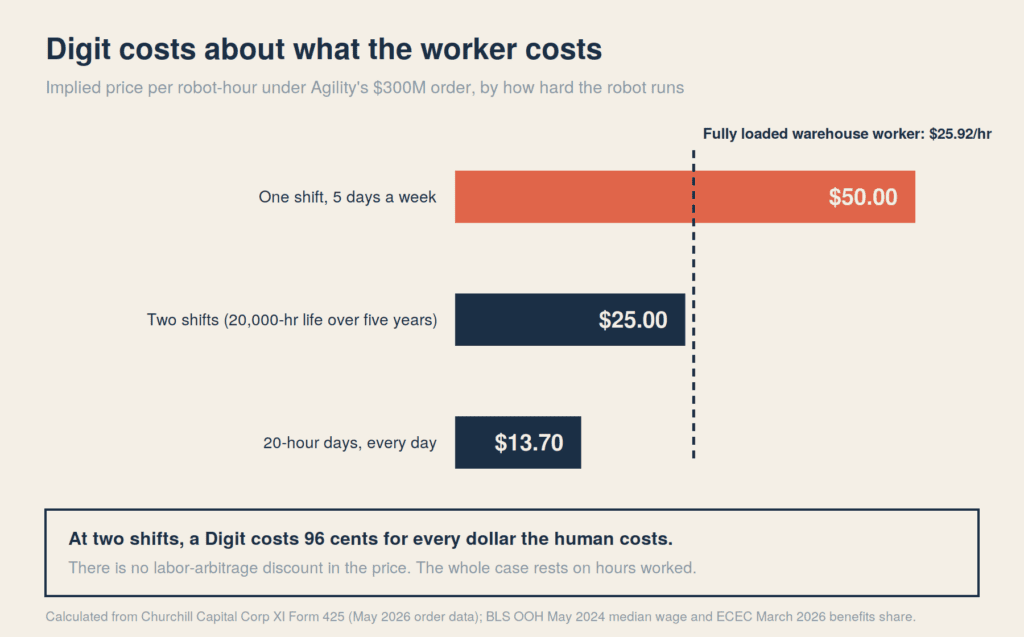
Agility priced Digit at 96 cents on the human dollar. There is no labor arbitrage in the number. Run the machine one shift and it costs $50 an hour, double the worker. Run it 20 hours a day and it costs $13.70, but at that pace it burns through its 20,000-hour service life in 2.7 years and dies inside its own three-year contract.
Every argument about this company is an argument about duty cycle.
Which is what makes the RaaS choice interesting rather than merely trendy. Selling a robot outright hands the utilization problem, the maintenance bill and the residual value to the buyer. Leasing it keeps all three. Agility now owns the downtime, the service calls, the replacement parts and whatever a three-year-old Digit is worth when the contract ends. The $620 million is not growth capital in the software sense. It is the balance sheet a leasing company needs to carry a fleet it manufactures itself.
The reward for taking that on is real. If Agility halves its bill of materials over the next four years, the customer’s alternative has not gotten any cheaper, because warehouse wages do not fall. Under a lease, that whole cost curve lands in Agility’s gross margin instead of being competed away in price. Unitree, which sells units outright and watched its humanoid average price fall 72% in two years, has no such shelter.
Then there is the footnote. Churchill’s own filing describes the order as relating to 1,000 Digit v5 robots on a three-year RaaS term “which includes warrants issued to purchaser vesting proportionately to robots deployed.” The anchor customer did not simply agree to rent robots. It received equity in the company whose valuation that agreement now supports.
Amazon has run this play on its logistics partners for years, and it is a rational way for a young supplier to buy a marquee reference. It also means the single largest piece of commercial evidence in this deal was partly purchased with the stock the evidence is being used to price.
The Risk
The concentration is close to total. Agility’s initial filings put 2025 operating expenses near $111 million, up from about $71 million, with roughly $100 million of cash burned and revenue not disclosed. Against that, one unnamed counterparty accounts for essentially the entire order book. If that customer slows its rollout, the milestones stop converting, and the filings already warn that the $300 million depends on hitting them.
The 65,000 hours were logged by Digit v4. The order is for v5, a machine that has not shipped, running unfenced next to people for the first time. Agility is asking buyers to underwrite a 185-fold scale-up on a product with zero commercial hours.
Amazon is the awkward name on the customer list. It passed one million deployed robots in July 2025, almost none of them shaped like people, and it keeps building its own. Amazon is a proof point and a competitor holding a decade of automation data.
On price, Apptronik has told reporters it expects to deliver Apollo in volume for roughly $80,000 a year, about 20% under Agility’s implied rate, with $5.5 billion of private capital behind it. Figure carries a $39 billion mark. Agility’s $2.5 billion looks cheap next to both, though the comparison cuts the other way too: Figure and Apptronik are priced on stories, and Agility is about to be priced on an audited P&L. Under the 2024 rules, its executives sign that document and carry Section 11 liability for it.
Quick Questions
Is the $300 million revenue? No. Churchill’s filing states it is not a measure of current period revenue, that it depends on contractual milestones, and that it reflects orders as of May 2026.
Who is the customer? Agility has not said. The named roster covers deployments, not this contract.
When does it close? Fourth quarter 2026, subject to a shareholder vote, SEC review of the S-4, HSR clearance and a minimum of $200 million available at closing.
Can you buy AGLT today? No. Churchill trades as CCXI and converts at close.
Is Digit v5 shipping? Agility has guided to December.
The Business Model Analyst Take
Johnson’s advice in the WSJ interview was to start with problems out in the world and work backward, and Agility followed it further than most people notice. Warehouses do not have a robot problem. They have a coverage problem: peak seasons, night shifts, turnover, injuries. Agility answered by selling coverage instead of hardware, priced by the month.
That answer created the hardest version of this business. A robot sale is a transaction that ends at the loading dock. A robot lease is a promise you keep for three years, and Agility just made 1,000 of them against a machine that has not shipped, on a fleet whose hours it must produce rather than project.
Watch two numbers when the S-4 goes public. The first is realized utilization per deployed robot, because the difference between one shift and two is the difference between costing double a human and costing slightly less. The second is service cost as a share of RaaS revenue, which tells you whether Agility is running a fleet or subsidizing one.
Johnson’s other lesson from the Qualcomm years was that her team once capped the mobile phone market at a million units because nobody gave themselves permission to think bigger. She is right that the ceiling here is high. The floor is the part that gets audited.