
ADP moved $3.5 trillion of other people’s money in fiscal 2026 and kept $21.9 billion of it. The interesting part is not the size. It is that ADP runs one payroll engine and sells access to it through two legal structures, and the structure you pick changes the price by a factor of nine.
What ADP actually sells
Automatic Data Processing runs payroll, tax filing, benefits administration, time tracking and HR software for more than 1.1 million clients in over 140 countries. It pays more than 42 million workers, about 26 million of them in the United States, which works out to roughly one in six American workers on ADP’s own count.
The company reports two segments. Employer Services sells software and outsourcing to employers who remain the employer. PEO Services, branded ADP TotalSource, is a professional employer organization: ADP becomes a co-employer of record alongside the client, and the client’s staff become worksite employees on ADP’s books for benefits and tax purposes.
Same payroll runs. Same tax filings. Same platform underneath. Different legal position, and a very different invoice.
Definition box. ADP’s business model is a per-employee recurring fee business layered on top of a payment flow. Employers pay a subscription plus per-transaction fees to have ADP compute, file and remit payroll. ADP holds the payroll cash for a few days between funding and disbursement and earns interest on it. For clients who want the liability and the insurance buying moved off their own balance sheet, ADP sells a second version of the same service in which it becomes the co-employer and bills a much larger fee that includes health premiums it collects and passes to carriers.
| Fiscal 2026 (year to 30 June) | FY2026 | FY2025 | Change |
|---|---|---|---|
| Total revenue | $21,947.4M | $20,560.9M | +6.7% |
| Employer Services | $14,831.4M | $13,883.1M | +6.8% |
| PEO Services | $7,128.1M | $6,690.4M | +6.5% |
| Interest on funds held for clients | $1,354.8M | $1,189.1M | +13.9% |
| Pretax earnings | $5,730.3M | $5,310.1M | +7.9% |
| Net earnings | $4,413.5M | $4,079.7M | +8.2% |
| Diluted EPS | $10.94 | $9.98 | +9.6% |
The PEO looks like a bad business, and it is not
Read any profile of ADP and you will find the same line: Employer Services carries a 36.7% margin, PEO Services carries 13.1%, so the PEO drags the company down. ADP reported exactly those numbers for fiscal 2026, and PEO segment earnings fell 2% on revenue that grew 7%.
That comparison breaks on a disclosure ADP puts in its own earnings release. Inside the $7,128.1M of PEO revenue sits $4,607.3M of what ADP calls zero-margin benefits pass-through costs. Those are health insurance premiums. ADP collects them from clients, books them as revenue, hands them to carriers, and books an identical amount as expense. Every dollar of it lands in the margin denominator and contributes nothing to the numerator.
Strip it out and ADP tells you the answer itself: PEO revenue excluding zero-margin benefits pass-throughs was $2,521M. Set that against the $936.1M the segment earned.
| Margin measure | FY2025 | FY2026 | Change |
|---|---|---|---|
| PEO margin as reported | 14.2% | 13.1% | -107 bp |
| PEO margin on the revenue ADP keeps | 39.6% | 37.1% | -245 bp |
| Employer Services margin | 36.1% | 36.7% | +58 bp |
The PEO earns 37.1% on the money it keeps. Employer Services earns 36.7%. The segment that half the internet calls low margin out-earns the core business by 48 basis points.
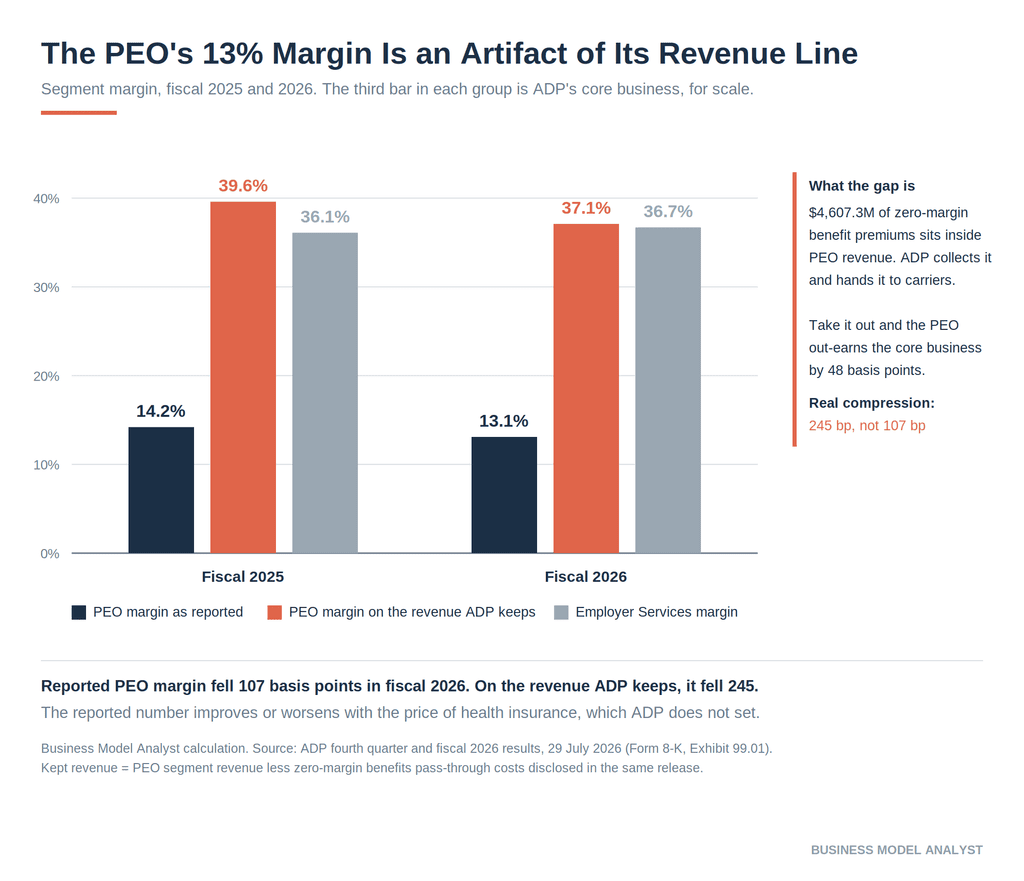
The second finding in that table matters more for anyone forecasting ADP. Reported PEO margin fell 107 basis points in fiscal 2026. On the revenue ADP keeps, it fell 245. The reported figure understated the real compression by 2.3 times, because the pass-through base grew 7.4% while the revenue ADP keeps grew 5.0%. A denominator inflating faster than the numerator pushes the reported margin down on its own, with no change in how well ADP runs the business.
This cuts both ways, and it is worth being precise about it. If health insurance inflation slows, ADP’s reported PEO margin will improve without ADP doing anything. If premiums spike, it will fall. The headline PEO margin is a partial read on medical trend, not on ADP’s execution.
The cleanest way to see it: measure both segments on the revenue ADP keeps rather than the revenue it bills. Employer Services takes 85.5% of kept revenue and delivers 85.3% of segment earnings. The PEO takes 14.5% and delivers 14.7%. Those pairs sit 16 basis points apart. ADP earns the same margin on both wrappers, which is the tell that the wrapper is a pricing decision rather than a different business.
What the nine times buys
Once the pass-throughs come out, the price comparison gets stark. Outside the PEO, ADP collected about $360 per worker over the year, roughly $30 a month. Inside the PEO, it kept $3,308 per worksite employee, about $276 a month. That is a 9.2x gap, and it drops to 6.6x if you also remove the workers’ compensation and state unemployment costs ADP carries for worksite employees.
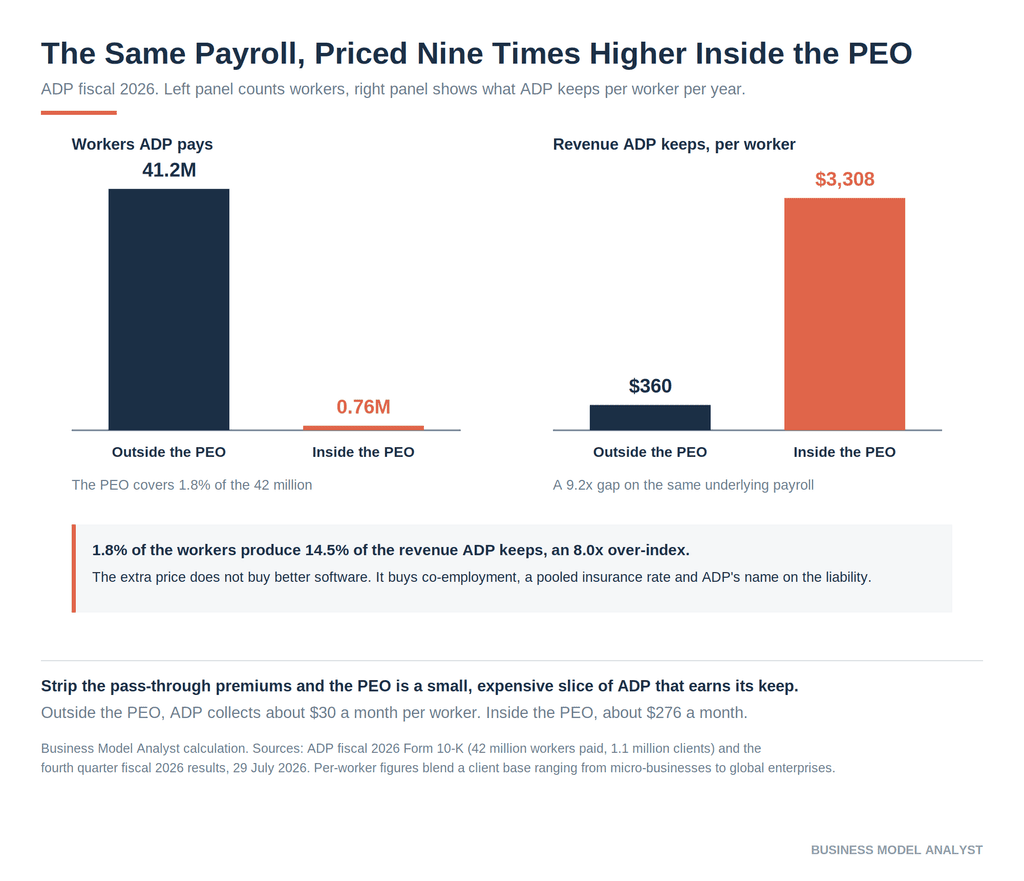
Treat the multiple as directional rather than exact. The $360 blends a client base that runs from one-person shops to global enterprises across 140 countries, and the $3,308 covers American small and mid-sized businesses only. The direction is not in doubt, though, and the same gap shows up on a cleaner denominator: ADP keeps 3.11% of the $81.1 billion of wages and payroll taxes flowing through the PEO, against 0.43% of the payroll dollars it moves everywhere else. Call it seven times on like-for-like terms.
A 40-person design agency is not paying that premium for better software. It is buying three things it cannot buy alone:
Insurance rates it has no scale to negotiate. ADP pools 775,000 worksite employees into master health and workers’ compensation programs. A small employer walking into the fully insured small group market alone gets priced on its own claims experience with a handful of lives. The pooling logic is the same one that drives captive insurance structures, reached through a vendor instead of a licensed subsidiary.
Employment liability that moves off the client’s books. As co-employer, ADP files the employment tax returns, carries the workers’ compensation policy, and shares exposure on a range of employment claims. Founders buy that to stop being the party with sole responsibility for a compliance regime spanning federal, state and local rules.
A benefits menu that helps them recruit. A 40-person firm offering the benefits package of a 775,000-person employer competes for staff differently.
None of that is software. It is a legal position plus a purchasing pool, and ADP charges for it accordingly.
The rival case for this structure shows up at TriNet, which sells almost nothing else. TriNet guided 2026 total revenue to $4.75B to $4.9B with professional services revenue of only $625M to $645M. Insurance billings make up about 87% of what it invoices, and its insurance cost ratio runs near 90%, meaning it retains roughly a tenth of the insurance dollar. When TriNet repriced health benefits, worksite employees fell 12% year over year. In a PEO, the price of health insurance is the churn variable. ADP carries the same exposure at a smaller share of its total.
The third engine nobody buys on purpose
Between the moment an employer funds payroll and the moment the money reaches a worker or a tax authority, it sits with ADP. Across fiscal 2026 that averaged $40.4 billion. ADP invested it at an average yield of 3.4% and earned $1,354.8M.
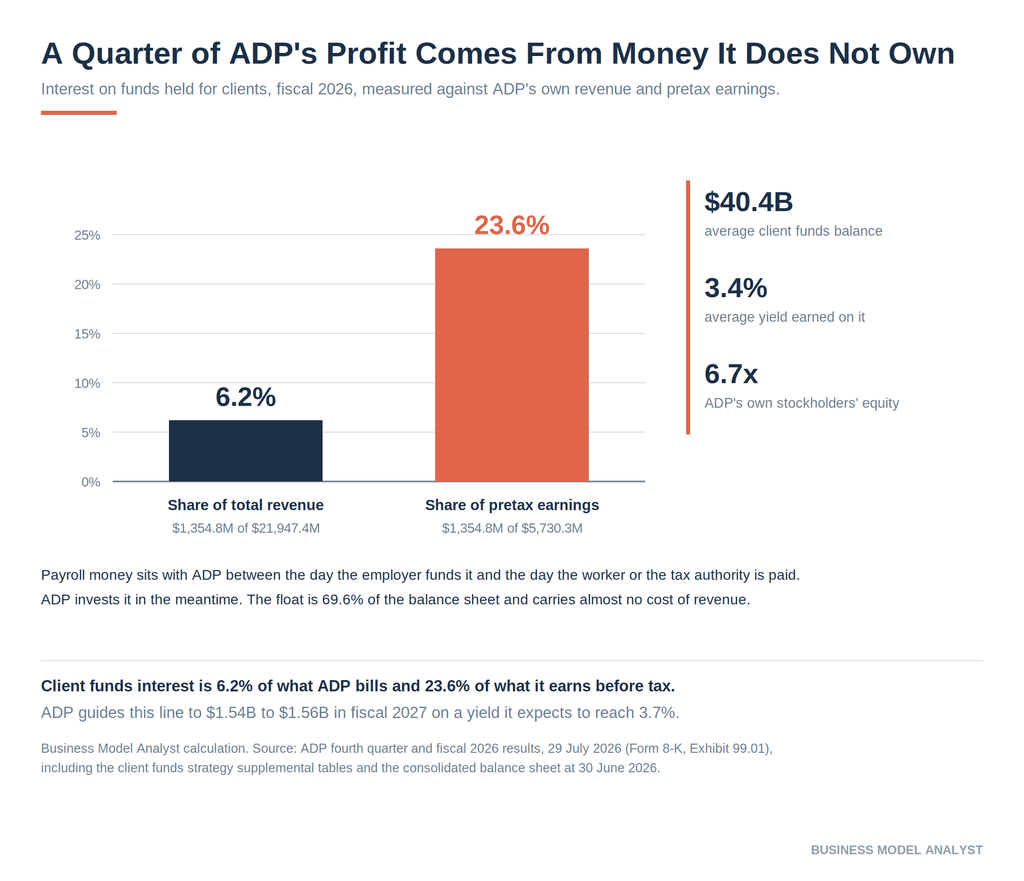
That line is 6.2% of revenue and 23.6% of pretax earnings. It carries almost no cost of revenue, so it converts to profit at a rate nothing else at ADP matches. At 30 June 2026, funds held for clients stood at $43,957.8M against stockholders’ equity of $6,031.2M. Client money is 69.6% of the balance sheet and 7.3 times the equity of the company holding it.
ADP layers a second trade on top. It extends the maturity of the client portfolio and funds the short end with commercial paper and reverse repo, a structure it calls the client funds extended investment strategy. In fiscal 2026 that added $278.1M of corporate extended interest income against $318.3M of short-term financing cost, and the whole program contributed $1,314.6M. ADP guides it to $1.545B to $1.565B in fiscal 2027 on a yield reaching 3.7%.
Money in transit as a profit center is a recurring pattern in financial software. Intuit runs a version of it inside QuickBooks, where funds held for customers swing by billions between quarters, and the Intuit business model teardown walks through how that balance sheet works. The general shape appears across the sector, covered in more depth in how fintechs make money.
The risk here is symmetrical and outside ADP’s control. Rate cuts compress it. So does a shrinking payroll base, since balances scale with employment and wages together.
Growth is a treadmill, and the belt is speeding up
ADP grew Employer Services 5% on an organic constant currency basis in fiscal 2026. Only one of those points came from clients hiring. US pays per control, ADP’s same-store measure of employees on client payrolls, rose 1%. It rose 2% in fiscal 2024 and 1% in fiscal 2025, and ADP guides 0% to 1% for fiscal 2027. In the first quarter of fiscal 2026 it printed flat, and management cut the year’s outlook on the spot.
A per-employee subscription business whose seat count is decided by other companies’ hiring managers has an obvious exposure. When American employers stop adding staff, ADP’s easiest growth lever goes quiet, and price increases plus net new logos have to carry the rest.
Net new logos are harder than the bookings number suggests. Client revenue retention held at 92.1%, which ADP presents as a win. Read the complement: 7.9% of the revenue base leaves every year. Against the fiscal 2025 Employer Services base of $13,883.1M, that is $1,097M walking out the door.
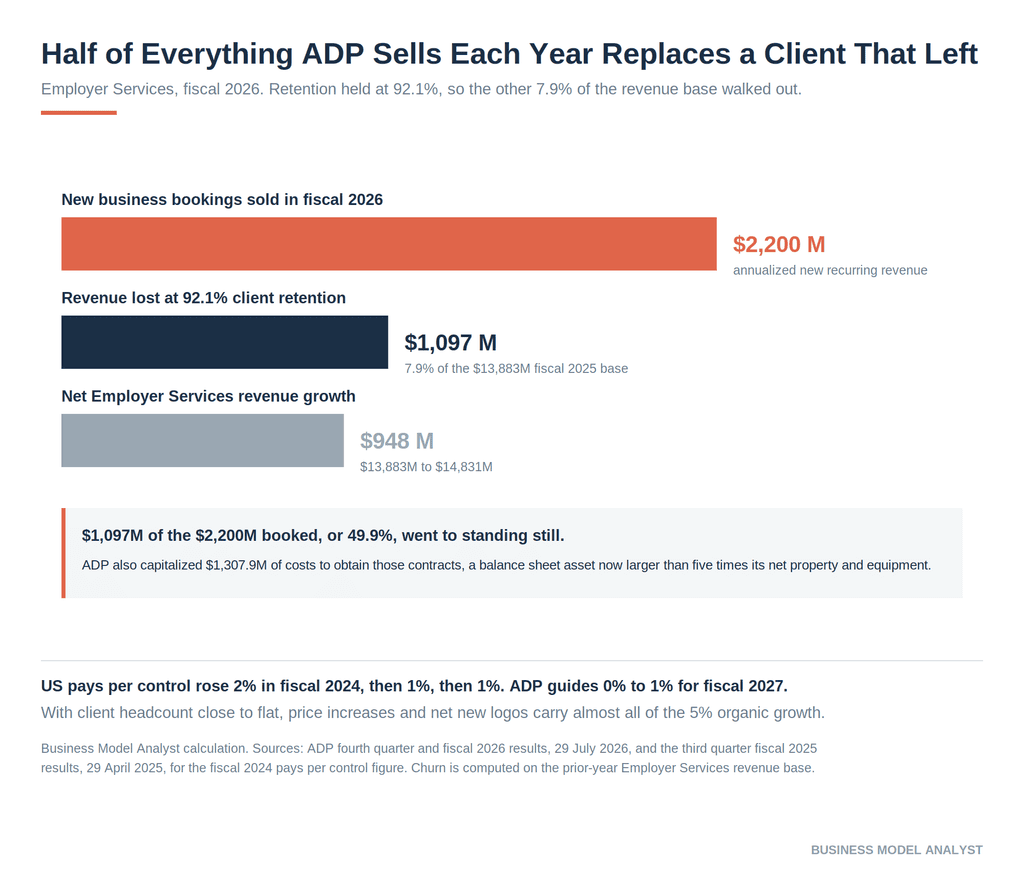
ADP sold $2.2 billion of new business bookings that year. Just under half of it replaced clients who left. Segment revenue grew $948M net.
The cost of running that treadmill shows up in a balance sheet line most readers skip. ADP capitalized $1,307.9M of costs to obtain contracts in fiscal 2026 and amortized $1,200.5M of prior years’ costs. The asset now stands at $3,244.1M, more than five times ADP’s net property and equipment of $641.3M and within a rounding error of its entire goodwill balance of $3,284.4M. Against an income statement research and development line of $1,028.8M, ADP put 27% more onto its balance sheet for winning clients than it expensed on building the product. The 10-K cites a broader R&D figure of $1.405 billion including capitalized software, which lands the two roughly level. Either way, distribution and engineering are the same size at ADP, and that is what you would expect from a company whose pricing power rests on structure and switching costs rather than product differentiation.
And switching costs are the moat. Moving payroll providers means re-parallel-running tax filings, migrating year-to-date wage histories, re-enrolling benefits and risking a late deposit penalty from a tax authority. Employers do it, at a rate of about 8% a year, and most of them do it when something breaks.
Where the money goes
ADP spent $10,240.6M on operating expenses, $4,408.2M on selling, general and administrative, and $1,028.8M on research and development in fiscal 2026, running a workforce of about 67,000. Pretax margin came in at 26.1% and adjusted EBIT margin at 26.8%, up 80 basis points.
The margin expansion has a cost attached. In the fourth quarter ADP booked a $91.1M charge for a business alignment program, of which $89.1M was severance, and excluded it from adjusted results. Management credits AI tools across product, service and sales for the productivity gains, and reports 3.1 million users holding 12 million conversations with its ADP Assist agents during the year. The severance line and the AI line arrived in the same quarter, which is the pattern worth watching rather than either number alone.
Capital allocation is the least ambiguous thing about ADP. The company generated $5,441.2M of operating cash flow, spent $196.6M on capital expenditure, then returned $2,626.3M in dividends and $2,083.3M in buybacks. That is $4,709.6M against $4,413.5M of net earnings, or 107% of profit paid out. Equity fell from $6,188.0M to $6,031.2M despite the year’s earnings, and return on equity came in above 70%. ADP is a mature annuity that has been raising its dividend for five decades and does not pretend otherwise.
The risk
Four things could break this model, in rough order of likelihood.
Rates fall and take the float with them. A 100 basis point move across the portfolio is worth roughly $400M of near-pure profit on a $40.4B balance, against $5,730.3M of pretax earnings.
Employment stalls. Pays per control at zero for a year turns a 5% organic grower into a 3% to 4% one, and the fiscal 2027 guide of 0% to 1% already assumes something close to that.
Health insurance inflation reprices the PEO. TriNet lost 12% of its worksite employees after a repricing round. ADP’s PEO grew worksite employees only 2% in fiscal 2026 and guides to about 2% again, which is not a business absorbing large price increases comfortably.
The small end erodes. Gusto, Rippling and Paychex compete for exactly the sub-50-employee clients where ADP’s retention is weakest and its per-employee pricing is thinnest. ADP’s answer is bundling and AI-driven service cost reduction. That answer has held for a decade. It has not been tested against tools that cut the cost of running compliant multi-state payroll to near zero.
The counter-argument deserves its due. ADP has grown revenue 7% for three consecutive years, expanded adjusted margin 80 basis points, held retention flat at a level most software companies would take, and guides fiscal 2027 to 5% to 6% revenue growth with 9% to 11% adjusted EPS growth. None of that is the profile of a business under structural attack. The float, the pass-through optics and the flat pays per control are things to understand, not alarms.
Quick questions
How does ADP make money? Four ways: recurring per-employee subscription and transaction fees in Employer Services, a much larger per-employee fee in the PEO that bundles insurance and co-employment liability, interest on the $40.4 billion of client payroll cash it holds in transit, and a small amount of other income. Employer Services was 67.6% of fiscal 2026 revenue, PEO 32.5%, and client funds interest 6.2% sitting inside those segment totals.
Why is ADP’s PEO margin so low? It is not. The reported 13.1% includes $4,607.3M of health insurance premiums ADP collects and hands to carriers with no markup. On the revenue ADP keeps, the PEO earned 37.1% in fiscal 2026, slightly ahead of Employer Services at 36.7%.
What is a PEO and why would a business use one? A professional employer organization co-employs your staff. You keep day-to-day direction of the work; the PEO becomes employer of record for payroll taxes, benefits and workers’ compensation. Small employers use it to buy insurance at large-group rates and to move employment compliance risk off their own books.
Does ADP keep the interest on payroll money? Yes. Client funds are held in trust and the obligations are matched on the balance sheet, but ADP earns and keeps the investment income. That produced $1,354.8M in fiscal 2026, 23.6% of pretax earnings.
Is ADP a software company? Its economics say otherwise. ADP reported $1,028.8M of research and development against $4,408.2M of selling and administrative expense, capitalized $1,307.9M of contract acquisition costs, and derives close to a quarter of its profit from an investment portfolio. It sells compliance, insurance access and money movement, with software as the delivery mechanism.
The Business Model Analyst Take
ADP is a pricing architecture wearing a payroll company’s clothes. One engine, two wrappers, and the wrapper does the work. Move a client from Employer Services into TotalSource and the revenue per head goes up ninefold while the margin ADP earns stays where it was, because the extra money buys insurance access and a legal position rather than product.
For founders, the transferable lesson is the second one, not the first. ADP’s reported PEO margin has been telling investors a story about operational weakness for years when the number was mostly reporting the price of American health insurance. If you resell something at cost inside your own revenue line, your margin becomes a measure of your supplier’s pricing rather than your own performance. ADP handles this by disclosing the pass-through figure clearly enough that anyone can back it out. Most companies with a pass-through problem do not.
Two numbers to watch from here. Pays per control, because ADP’s cheapest growth comes from its clients hiring and that engine has been running near zero for two years. And the yield on client funds, because a business that earns 23.6% of its pretax profit on somebody else’s cash is a rates business wearing a subscription label, and rates move faster than payroll does.
Read next: the Intuit business model and how fintechs make money.