
Record sales, record marketing, and the fifth-worst day in the stock’s history. The World Cup quarter exposed a cost problem that has nothing to do with football.
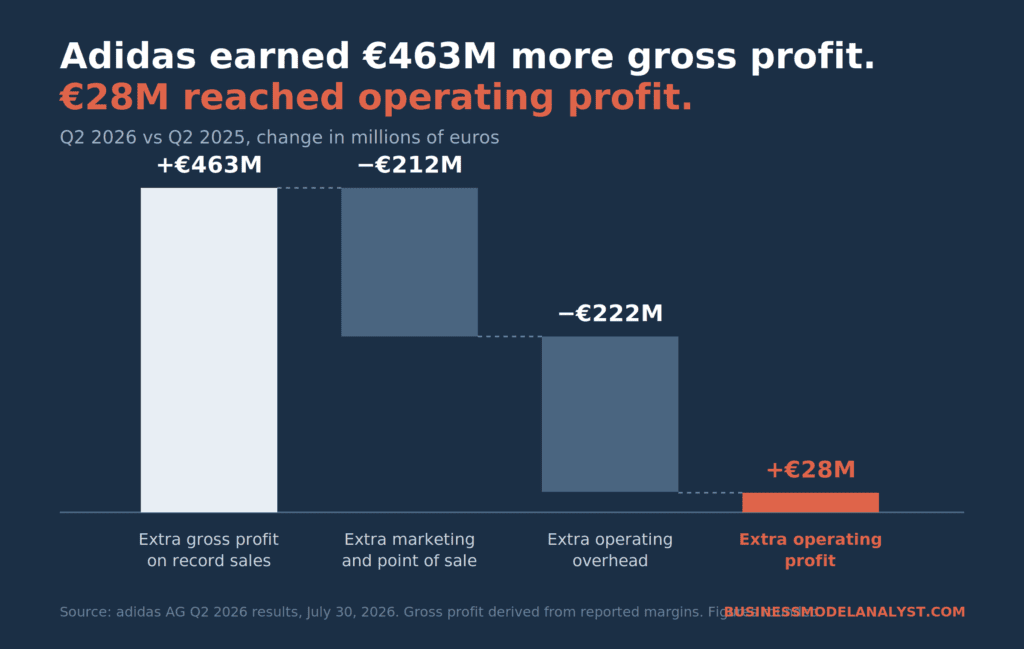
Adidas posted record second-quarter sales of €6.74 billion and gx’xenerated €463 million in additional gross profit. Only €28 million of it reached operating profit. Marketing absorbed €212 million and distribution overhead absorbed €222 million. Shares closed down 11.5% after management raised revenue guidance and left the profit target alone.
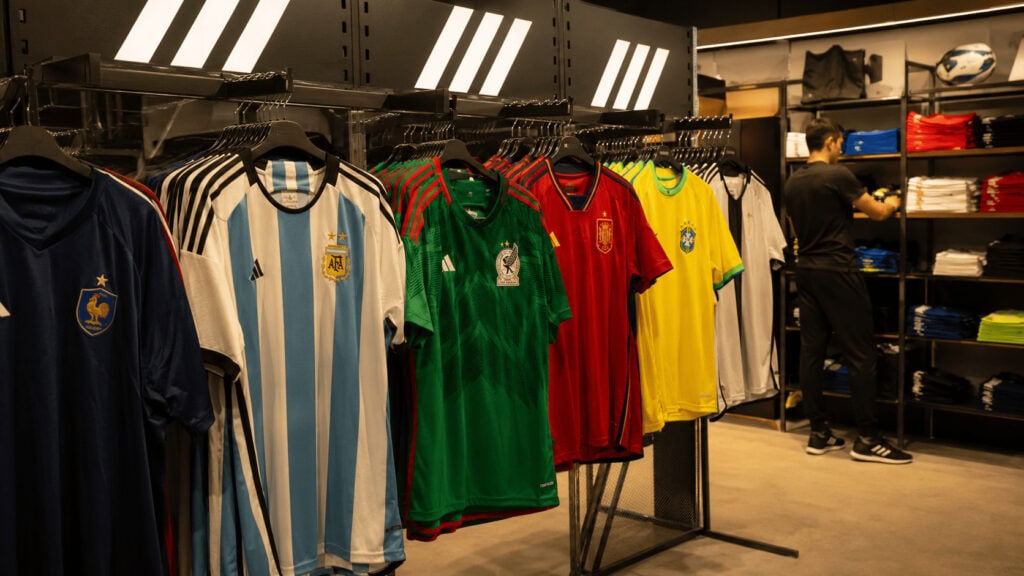
Bjørn Gulden spent Thursday morning telling analysts he could not have scripted the quarter better. Argentina and Spain played the final in his jerseys. The referees wore three stripes for the first time. Adidas moved more than 17 million shirts, four times the Qatar total, with Mexico outselling every other nation. Then the stock fell as much as 19% in Frankfurt and he told the call he was surprised.
He should not have been. The tournament worked. The P&L is where the argument sits.
What Happened
Adidas reported Q2 revenue of €6,743 million against €5,952 million a year earlier, up 14% on a currency-neutral basis and the highest quarterly figure the company has ever recorded. Gross margin improved 0.8 percentage points to 52.5%, helped by full-price selling and a better channel mix.
Operating profit rose 5% to €574 million. Analysts had modeled roughly €623 million, and Bloomberg’s consensus sat near €616 million. Operating margin fell to 8.5% from 9.2%.
Marketing and point-of-sale spending reached €924 million, up 30% from €712 million, which took it to 13.7% of sales from 12.0%. Adidas outfitted 14 of the 48 national teams, kitted the officials, supplied the Trionda match ball, and ran the Backyard Legends campaign with Timothée Chalamet, Lionel Messi, Lamine Yamal, Jude Bellingham and Bad Bunny. The company counted more than 9 billion views and over 400 million engagements, its most successful campaign on record. World Cup related sales came in around €1.5 billion.
Management lifted full-year currency-neutral revenue growth guidance to a range of 9% to 10% from high-single-digit. Operating profit guidance stayed at around €2.3 billion. Investors wanted the second number moved and did not get it. The shares recovered some ground into the close and finished down 11.5%, the fifth-largest one-day fall since the November 1995 listing.
Adidas also named Birgit Kretschmer to succeed Harm Ohlmeyer as CFO. She joins the executive board on September 1 and takes the role at year end.
The Backstory
Gulden inherited a wreck in 2023. The Ye split had killed Yeezy, buried the company in unsellable inventory, and produced a loss. His repair job leaned on owned franchises, sport credibility and full-price discipline, and it worked: currency-neutral growth of 13% in 2024, another 13% in 2025, and full-year 2025 operating profit of €2,056 million against €1,337 million the year before. The Adidas marketing strategy breakdown traces how that flywheel was rebuilt.
The World Cup was supposed to be the reward. North America is where Adidas has never won. The brand holds roughly 7% of the US sportswear market against Nike’s 27%, a gap laid out in the Adidas SWOT analysis. Staging football’s biggest tournament across the United States, Canada and Mexico handed Gulden a shot at that gap on home turf.
History offered a warning nobody quoted. On July 31, 2014, three weeks after Germany won the World Cup in Adidas kit, the company cut its profit forecast and the stock dropped as much as 16%. The causes then were Russia and golf equipment. The pattern is the same: the quarter after a triumphant tournament is where this stock gets hurt.
The Plan
Gulden’s defense on the call was straightforward. Adidas chose to spend into a rare window. Ohlmeyer put it as investing short term to open a longer opportunity. Neither man argues the money was wasted, and the sell-through data supports them. US store traffic jumped 44.7% year over year during the first full week of group-stage matches, according to Placer.ai. Adidas also loaded up on availability rather than optimizing inventory, which is why stock sits 13% higher at €5,969 million.
The forward math is where investors got stuck. First-half operating profit hit €1,279 million. A full-year target of around €2.3 billion leaves roughly €1.02 billion for the second half, on revenue Gulden says grows about 6%. That figure beats the €900 million Adidas earned in the back half of 2025, so the guide is not a warning. It is a refusal to underwrite the halo. If the tournament converts into footwear demand and US share, the payoff shows up in 2027, not in the number management just declined to raise.
Two options sit outside the guidance. Adidas booked a small refund of US tariffs it considers unlawfully imposed and estimates $250 million to $300 million more may be recoverable. And Kretschmer arrives with a résumé Gulden described in cost terms: 25 years inside Adidas, then six years as CFO of C&A, a vertical retailer where controlling store and distribution expense is the job.
The Business Model Angle
Split the incremental gross profit and the story changes.
Adidas generated €463 million of extra gross profit in the quarter. Marketing and point of sale took €212 million. Operating overhead took €222 million. Every headline blamed the World Cup, and marketing was the smaller of the two lines.
Overhead rose 12% to €2,059 million from €1,837 million. Adidas explains the increase without ambiguity: shipping costs from e-commerce volume, extra staffing in its own stores and warehouses, and pop-up locations. Those costs attach to a direct-to-consumer channel that grew 25% in the quarter, with e-commerce up 27% and own retail up 23%, while wholesale grew 6%.
That is the trade every vertical retailer makes. DTC buys gross margin and charges operating expense. The 0.8 point gross margin gain Adidas reported came from full-price DTC selling and channel mix. The 0.7 point operating margin loss came from paying for the channel. Wholesale ships a pallet and lets the retailer carry the staff, the rent and the last mile. Own retail moves all of it onto your income statement, permanently. Marketing you can switch off in Q3. Warehouses you cannot. The Adidas business model has been drifting toward vertical retail for years, and this quarter priced the drift.
The product mix compounds it. Apparel revenue jumped 35% currency-neutral to €2,721 million from €2,029 million. Footwear grew 1%. Football rose 74%, motorsport 69%, running 28%. Basketball fell 21%, US Sports 4% and golf 10%. Lifestyle managed 2% in a market Gulden calls heavily discounted, especially in men’s.
Footwear is the larger half of the business and the half with franchise economics, repeat purchase and pricing power. Adidas bought a jersey quarter with a footwear-sized cheque. A World Cup shirt is a four-year purchase. The strategic case for €212 million was always that tournament heat converts into shoes, and Gulden told the call footwear stays flat in Q3 before returning to growth in Q4. The conversion has not happened yet.
Then there is the timing. Nike spent the last two years unwinding the DTC-first strategy that broke its own model, with Elliott Hill rebuilding wholesale relationships under the Win Now plan. Adidas is accelerating into the channel Nike is retreating from. The Adidas vs Nike comparison has run for decades on the two companies copying each other with a lag. This time they are moving in opposite directions.
The Risk
Footwear is the number to watch, not marketing. Flat footwear in a record quarter means the brand heat lives in apparel, and apparel carries shorter product cycles and thinner defensibility. Samba and Gazelle drove the recovery. Terrace demand held up this quarter, but a lifestyle market grinding through promotional inventory is where the last Adidas cycle turned.
Working capital tells its own story. Average operating working capital reached 24.0% of sales against 20.7%, a 3.3 point deterioration, and inventory sits 13% higher. Adidas chose availability over efficiency for the tournament. Jerseys for eliminated nations do not sell at full price in September.
Europe grew 6% while every other market grew double digits, and Adidas is holding wholesale sell-in back there because of promotional pressure. That is a deliberate choice, and it also removes the cheapest source of operating leverage the company has.
The counterargument deserves space. Skipping the biggest football event ever staged in your weakest large market would have been the more expensive error, and no accounting rule lets you capitalize brand affinity. Gulden built the last three years on marketing spend that competitors read as reckless and shareholders later repriced upward. Jefferies called the quarter a disappointing lack of margin leverage. Bloomberg Intelligence called the spending sensible support for demand beyond the tournament. Both can be right, and the tiebreaker is footwear growth in Q4.
Quick Questions
Why did Adidas stock fall after record sales?
Operating profit came in at €574 million against expectations near €623 million, and management raised revenue guidance while leaving the €2.3 billion operating profit target unchanged. Investors had priced in a profit upgrade after the World Cup and did not get one. Shares closed down 11.5%.
How much did Adidas spend on World Cup marketing?
Marketing and point-of-sale expenses reached €924 million in Q2 2026, up €212 million or 30% year over year. That equals 13.7% of sales, up from 12.0% a year earlier.
Did the World Cup make money for Adidas?
The tournament generated around €1.5 billion in related sales and more than 17 million jersey sales, four times the 2022 total. Group operating profit still rose only 5%, because marketing and distribution costs together consumed 94% of the additional gross profit the quarter produced.
Who is the new Adidas CFO?
Birgit Kretschmer joins the executive board on September 1, 2026 and succeeds Harm Ohlmeyer as CFO at year end. She spent 25 years at Adidas before serving six years as CFO of retailer C&A. Ohlmeyer, CFO since 2017, chose not to extend his mandate and helped run the succession process.
Is Adidas beating Nike?
Adidas grew 14% currency-neutral in Q2 2026 while Nike works through a turnaround under Elliott Hill after fiscal 2025 revenue fell 10% to $46.3 billion. Adidas still holds roughly 7% of the US sportswear market against Nike’s 27%, so the gap in the market that matters most remains wide.
The Business Model Analyst Take
Strip out the football and one line stays on the board: €463 million of extra gross profit produced €28 million of extra operating profit. That is six cents surviving on the euro, in the best quarter Adidas has ever printed.
The World Cup is the visible half of that. Marketing runs on a switch, and Q3 will show a smaller number. The half nobody wrote about is the €222 million of extra overhead, and that one runs on a contract. Warehouse workers, store staff, e-commerce shipping and pop-up leases arrive with a direct-to-consumer channel growing 25%, and they stay after the trophy goes back in the case.
For anyone building a brand, the lesson is about where you book the win. Adidas has a demand problem it solved and a cost structure it has not. Selling direct raises your gross margin and hands you a payroll. Gross margin flatters the deck. Operating margin pays the bills. Adidas improved the first by 0.8 points and gave back 0.7 on the second, in the quarter its brand ran hottest in a decade.
Gulden told analysts he delivered what he promised. He did. The market was not repricing the tournament. It was repricing what Adidas now costs to run, and Gulden handed it the evidence himself by refusing to raise the profit line. Watch footwear in Q4. If tournament heat converts into shoes, this quarter reads as an investment. If it does not, Adidas paid a footwear price for an apparel quarter, and the overhead stays either way.
Reporting based on adidas AG Q2 2026 results (July 30, 2026), The Wall Street Journal, Bloomberg, Reuters, Adweek, Jefferies and Bloomberg Intelligence commentary, Placer.ai foot traffic data, and adidas full-year 2025 reporting.